Diversifying Investment Portfolios Across Economic Sectors
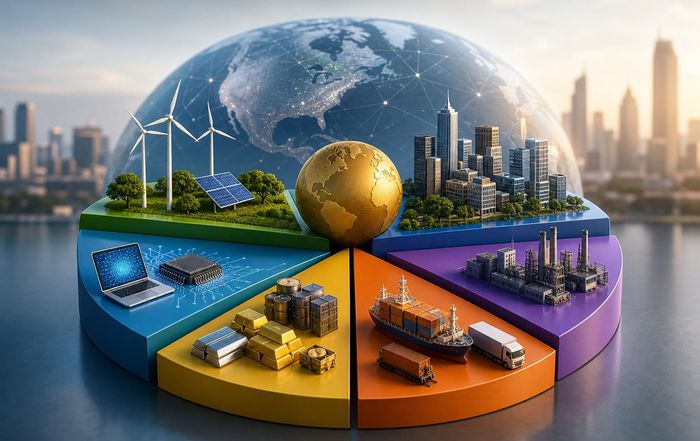
Building a resilient investment portfolio is less about finding a single "perfect" stock and more about balancing exposure across different parts of the economy. Sector diversification-spreading investments across industries such as technology, healthcare, energy, and consumer goods-can reduce the impact of any one area's downturn and position investors to benefit from multiple sources of growth.
This page examines why sector diversification matters, how major sectors behave at different points in the economic cycle, and practical ways investors can construct and maintain a balanced, globally aware portfolio.
Why sector diversification matters more than ever
Diversification is often discussed in terms of asset classes-equities, bonds, cash, real estate, and alternatives. Yet within equities, concentration risk frequently hides at the sector level. Many investors, for example, discovered during the 2022-2023 market swings that their "diversified" portfolios were heavily tilted toward a handful of large-cap US technology and communication-services stocks. When these names corrected at the same time, the portfolio behaved as if it were much less diversified than it appeared on paper.
Sector diversification aims to mitigate this by spreading equity exposure across parts of the economy that respond differently to interest rates, inflation, regulation, technological change, and consumer demand. Research from firms such as MSCI and S&P Dow Jones Indices shows that sector rotation-periodic leadership changes among sectors-is a persistent feature of equity markets over long periods, with different industries leading and lagging at various points in economic cycles. Having exposure across sectors means investors are less dependent on correctly predicting which industry will lead next.
At the same time, diversification is not simply about owning a little of everything. Over-diversification can dilute returns, increase complexity, and make risk management harder. The challenge is to identify a sector mix that reduces concentration risk while remaining aligned with an investor's time horizon, risk tolerance, and views on structural trends such as digitization, decarbonization, and demographic change. That balance is particularly important for readers following developments in global markets and long-term investment themes.
Understanding economic sectors and their role in a portfolio
Global equity markets are typically grouped into standardized sector classifications. The Global Industry Classification Standard (GICS), maintained by MSCI and S&P Global, divides listed companies into 11 primary sectors, including information technology, healthcare, financials, consumer discretionary, consumer staples, industrials, energy, materials, utilities, real estate, and communication services. These broad categories help investors understand where their capital is concentrated and how their portfolio may behave under different macroeconomic conditions.
Each sector tends to have characteristic drivers of revenue and profit. Information technology companies are often sensitive to innovation cycles, corporate IT spending, and valuations linked to growth expectations. Financials react strongly to interest rate changes, credit conditions, and regulatory shifts. Consumer staples, such as food and household goods, are more tied to population and income stability than to economic booms, which can make them relatively defensive in downturns. By mapping holdings to sectors, investors can see whether they are inadvertently making big macro bets-for example, on low interest rates, high commodity prices, or rapid consumer spending growth-without having consciously chosen to do so.
Sector classification also underpins many index-based products and benchmarks used by asset managers, pension funds, and ETFs. Major index providers such as S&P Global and FTSE Russell construct sector indices that track the performance of each segment, while broad-market indices like the S&P 500 or MSCI World publish sector breakdowns that investors can use as reference points. Understanding these frameworks helps investors compare their own allocations against the market and decide whether they want to be overweight or underweight particular sectors.
Cyclical vs defensive sectors: how they behave in different environments
A useful way to think about sector diversification is to distinguish between cyclical and defensive sectors. Cyclical sectors, such as consumer discretionary, industrials, energy, and materials, tend to perform better when economic growth is strong, unemployment is low, and business and consumer confidence are rising. These sectors benefit from higher demand for travel, durable goods, construction, capital equipment, and energy. However, they can be more volatile and vulnerable during recessions or periods of tightening financial conditions.
Defensive sectors, including consumer staples, healthcare, and utilities, are generally less sensitive to the economic cycle. People still need food, medicine, and electricity even in downturns, so revenue streams can be more stable. As a result, these sectors often experience smaller drawdowns in recessions, although they may lag during strong bull markets. For investors focused on capital preservation or on smoothing returns over time, maintaining a meaningful allocation to defensive areas can be an important risk-management tool.
Interest rates and inflation add another layer of complexity. For instance, banks and insurers in the financials sector can benefit from higher interest rates if they are able to widen net interest margins, although rising rates may also pressure borrowers and asset values. Growth-oriented sectors such as technology and parts of communication services often see valuations compressed when rates rise, because future cash flows are discounted more heavily. Real assets such as energy and materials may benefit from inflation, but they are also exposed to commodity price swings, geopolitical tensions, and environmental policy. Monitoring how these macro drivers affect sectors helps investors adjust allocations rather than reacting purely to short-term price moves.
Sector concentration risk: lessons from recent market cycles
The last decade has illustrated both the benefits and risks of sector concentration. In the US, a small group of large-cap technology and communication-services companies contributed a disproportionately large share of index returns, particularly in the years leading up to and following the pandemic. Investors who were heavily concentrated in these names enjoyed strong gains, but they also became exposed to policy risks, regulatory scrutiny, and valuation corrections in a narrow slice of the market.
Regulators such as the U.S. Securities and Exchange Commission (SEC) and the European Securities and Markets Authority (ESMA) do not prescribe specific sector limits for individual investors, but they have highlighted concentration risk in the context of funds and benchmarks. When a portfolio's performance is driven by a handful of correlated stocks in the same sector, shocks-such as changes in antitrust policy, data privacy rules, or sector-specific taxes-can have outsized effects.
Concentration risk is not limited to technology. Energy-heavy markets are exposed to oil price cycles and climate policy; bank-dominated indices are vulnerable to credit events and regulatory changes; and property-heavy portfolios can be hit by interest-rate spikes or structural shifts in office and retail demand. For readers following world and economics coverage, these sector-specific vulnerabilities often intersect with broader macro stories, such as monetary policy, trade tensions, and the energy transition.
Global diversification: sectors look different across regions
Sector diversification is also geographic diversification. Different markets have very different sector compositions, meaning that investing globally can change not only country exposure but also the sector mix. For example, the US equity market has a high weighting to information technology and communication services, while some European markets have larger exposures to financials, industrials, and consumer staples. Many emerging markets have heavier weights in energy, materials, and state-linked financial institutions.
Organizations such as the OECD and World Bank publish sectoral breakdowns and structural data that show how economies differ in their industrial composition. For investors, this means that owning a broad international index fund or ETF often provides both geographic and sector diversification relative to a home-market portfolio. It also means that macro events-such as commodity price swings, supply-chain reconfiguration, or industrial policy in China, the EU, or the US-can have uneven effects on portfolios depending on their regional and sector exposures.
Global sector diversification does, however, introduce additional layers of risk and opportunity: currency movements, regulatory differences, political risk, and divergent climate policies can all affect sector performance. For instance, utilities and energy companies in Europe may face different decarbonization timetables and carbon pricing regimes than their counterparts in North America or Asia. Technology firms may be subject to distinct data localization rules or competition laws across jurisdictions. Investors seeking to diversify across sectors globally must therefore consider both sector fundamentals and regional policy environments, topics frequently explored in trade and business coverage.
Structural themes: technology, AI, sustainability, and demographics
Beyond the traditional cyclical/defensive framework, several long-term structural trends are reshaping sector prospects. One is the spread of digital technologies and artificial intelligence across the economy. While the most visible beneficiaries are in the information technology and communication-services sectors, productivity gains and business-model changes are also affecting industrials, financials, healthcare, and consumer-facing industries. Organizations such as OECD, IMF, and World Economic Forum have highlighted how AI and digitalization could alter employment structures, productivity, and competitive dynamics across sectors.
Another powerful theme is the transition to a low-carbon economy. Climate-related policies, investor preferences, and technological innovation are influencing energy, utilities, materials, industrials, and parts of the financial sector. Initiatives tracked by bodies such as the International Energy Agency (IEA) and frameworks from the Task Force on Climate-related Financial Disclosures (TCFD) encourage investors and companies to assess climate risks and opportunities at the sector level. For example, utilities and energy companies with credible transition plans may face different risk profiles from those heavily dependent on fossil fuels without clear decarbonization strategies.
Demographic change also matters. Ageing populations in many developed markets support long-term demand for healthcare, pharmaceuticals, and certain financial products such as retirement solutions, while younger populations in parts of Asia and Africa may underpin growth in consumer discretionary, communications, and education-related services. For folks interested in sustainable and long-horizon investing, incorporating these structural themes into sector allocations can complement traditional diversification.
Practical ways to diversify across sectors
For most individual investors, the practical question is how to translate sector theory into an implementable portfolio. One straightforward approach is to use broad-market index funds or ETFs that track diversified benchmarks such as the MSCI World, MSCI ACWI, or S&P 500. These instruments, typically offered by large providers like Vanguard, BlackRock's iShares, and State Street Global Advisors, give exposure to multiple sectors in proportions reflecting the underlying market. Investors can then adjust around this baseline if they want to overweight or underweight certain sectors based on their own views and risk appetite.
Another approach is to use sector-specific funds or ETFs to tilt exposure. For example, an investor might hold a core global equity fund and then add dedicated allocations to healthcare or technology if they believe those sectors have superior long-term prospects, while still maintaining exposure to other industries. Sector funds can also be used tactically, such as increasing defensive exposure during late-cycle conditions or adding cyclical exposure early in a recovery. However, sector rotation strategies require discipline and a clear framework to avoid frequent, emotionally driven trading.
Investors who prefer to select individual stocks can use sector weights from major indices as reference points. If an investor's portfolio has a 50% allocation to technology and communication services while the benchmark is closer to 30%, they should be aware that they are making a significant active bet. Tools provided by many brokers and data platforms allow users to see sector breakdowns of their holdings. For those following new times in tech, AI, or crypto, this is particularly relevant, as enthusiasm for high-growth areas can quickly lead to concentrated sector exposure.
Balancing growth, income, and stability across sectors
Different sectors contribute differently to total return. Some are typically associated with capital growth, others with income, and some with relative stability. Technology, communication services, and parts of consumer discretionary are often seen as growth-oriented, reinvesting earnings to expand rather than paying high dividends. Utilities, consumer staples, and certain real estate segments tend to offer higher dividend yields but slower growth. Financials, healthcare, and industrials may sit somewhere in between, depending on the specific business models and regulatory environments.
Constructing a balanced sector allocation therefore involves aligning sector exposures with an investor's objectives. A younger investor with a long time horizon and higher risk tolerance may be comfortable with a larger allocation to growth sectors, accepting higher volatility in pursuit of greater long-term appreciation. An investor focused on income or capital preservation may lean more heavily on dividend-paying and defensive sectors, while still maintaining some exposure to growth areas to protect against inflation and technological disruption.
It is also important to consider correlations between sectors. While defensive sectors can reduce volatility, they may be more sensitive to interest-rate changes because their cash flows resemble bond-like income streams. High-dividend utilities and real estate, for instance, can face pressure when yields on government bonds or investment-grade credit rise. Growth sectors may be more sensitive to equity risk premia and changes in risk appetite. A well-diversified portfolio blends these characteristics rather than relying on any single sector to deliver all three goals of growth, income, and stability.
Monitoring, rebalancing, and avoiding unintended bets
Sector diversification is not a one-off decision; it requires ongoing monitoring and periodic rebalancing. Over time, sectors that outperform will naturally become a larger share of the portfolio, while underperforming sectors will shrink. If left unchecked, this can lead to renewed concentration risk, even in a portfolio that started out balanced. Many institutional investors and wealth managers adopt rebalancing policies-such as reviewing allocations annually or when sector weights deviate by a certain percentage from targets-to keep risk within defined parameters.
Rebalancing can be psychologically challenging because it often involves trimming winners and adding to laggards. Yet this discipline is central to maintaining diversification and avoiding the trap of chasing recent performance. Investors can use sector data from index providers, research platforms, or their brokerage dashboards to track how their allocations evolve. They should also be attentive to changes in sector fundamentals: regulatory shifts, technological disruption, competitive landscapes, and balance-sheet strength can all influence whether a sector's risk-return profile has structurally changed.
Another key task is to identify and reduce unintended sector bets. For example, an investor might hold a technology index fund, a growth-focused active fund, and a thematic AI ETF, believing they are diversified across managers and styles, when in reality their underlying exposure is heavily concentrated in the same group of large-cap tech names. Similarly, a portfolio of dividend-focused funds might be overexposed to utilities, financials, and energy. Looking through to the sector breakdown of each holding can reveal overlaps and help investors adjust.
Sector diversification in a changing macro and regulatory landscape
The macroeconomic and regulatory environment continues to evolve, affecting sectors in different ways. Central banks such as the Federal Reserve, European Central Bank, and Bank of England are navigating the aftermath of pandemic-era policies, inflation dynamics, and changing growth prospects. Their decisions on interest rates, balance-sheet policies, and financial stability measures influence sectors differently, from rate-sensitive financials and real estate to growth-oriented technology and communications.
At the same time, regulators and standard-setters are expanding requirements around climate and sustainability disclosures, data privacy, and capital adequacy. Initiatives from bodies such as the Financial Stability Board (FSB) and national securities regulators are pushing companies to provide more detailed information on sector-specific risks, including climate transition risks for energy and industrials, cybersecurity for technology and financials, and demographic and pricing pressures for healthcare. For globally diversified investors, staying informed about these developments is increasingly part of sector-level risk assessment.
As the global economy adjusts to shifts in supply chains, geopolitics, and technology, some sectors may experience structurally higher volatility or more frequent policy intervention. That does not necessarily argue against investing in them; rather, it highlights the importance of diversification and of understanding how sector-specific risks interact with broader portfolio goals. For alert people tracking news and finance, this intersection of policy, economics, and sector performance is likely to remain a central theme.
Bringing it together: a disciplined, sector-aware approach
Diversifying across economic sectors is ultimately about resilience. No investor can reliably predict which sector will lead in every phase of the cycle, nor which industries will be most affected by the next policy shift, technological breakthrough, or geopolitical event. By spreading exposure across multiple sectors-balancing cyclical and defensive areas, growth and income, domestic and international markets-investors reduce the impact of being wrong about any single theme.
A disciplined approach typically includes understanding current sector exposures, using broad-market vehicles as a core, tilting selectively rather than betting the portfolio on a narrow theme, and rebalancing as markets move. It also involves staying informed about how structural trends such as AI, decarbonization, and demographic change may alter sector dynamics over time, without overreacting to short-term noise.
For individuals and institutions alike, sector diversification does not guarantee positive returns or eliminate risk. But as part of a broader asset-allocation framework, it can make portfolios more robust to uncertainty and better aligned with long-term financial objectives.
