Understanding Working Capital Cycles in Growing Companies
Growing companies often discover that "more sales" does not automatically mean "more cash." The missing link is the working capital cycle: the rhythm with which cash moves out of a business to fund operations and eventually flows back in. For fast-growing firms, especially in capital-intensive or inventory-heavy sectors, understanding and actively managing this cycle can be the difference between scaling successfully and running out of cash despite rising revenue. This new document explains what the working capital cycle is, how to calculate and interpret it, why growth usually makes it more demanding, and what practical levers finance leaders and founders can pull to keep cash flowing. It also looks at sector differences, financing options, and warning signs that the cycle is becoming a risk.
What the working capital cycle actually measures
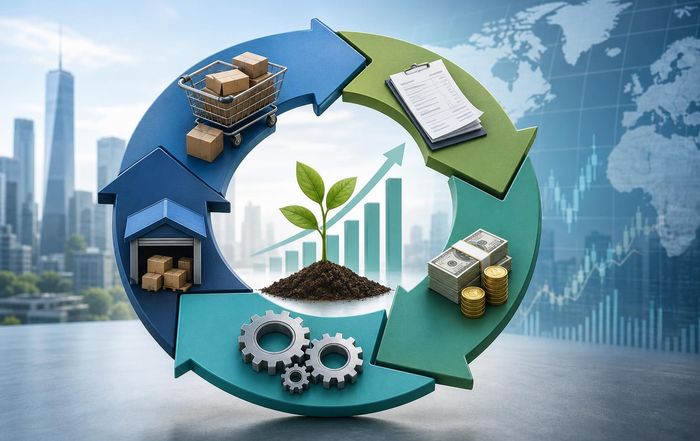
Working capital is commonly defined as current assets minus current liabilities. The working capital cycle (sometimes called the cash conversion cycle) goes a step further: it measures how many days it takes to convert cash paid out for operations back into cash received from customers. It focuses on three operational components: inventory, receivables, and payables.
A widely used formula combines three "days" metrics:
Days Inventory Outstanding (DIO) - average days inventory is held before it is sold.
Days Sales Outstanding (DSO) - average days customers take to pay.
Days Payables Outstanding (DPO) - average days the company takes to pay its suppliers.
The working capital cycle (WCC) is:
WCC (days) = DIO + DSO - DPO
A positive result means cash is tied up in operations for that number of days before returning. A shorter cycle generally indicates that a company is turning inputs into cash more quickly. A negative cycle, which some large retailers and platforms achieve, means the business receives cash from customers before it pays suppliers, effectively funding operations with supplier credit.
Accounting standards from bodies such as the International Accounting Standards Board at https://www.ifrs.org/ and the US Financial Accounting Standards Board at https://www.fasb.org/ shape how inventory, receivables, and payables are recognized, but the commercial dynamics behind the cycle are driven by contracts, operations, and customer behavior rather than rules alone. For entrepreneurs and professionals who want to place working capital in a broader corporate finance context, the concepts connect closely to topics covered in our finance, investment, and markets sections.
Why working capital cycles tighten as companies grow
Growth typically magnifies working capital needs because the amounts tied up in inventory and receivables scale with revenue. A company that doubles sales often needs more stock, more staff, and more credit extended to customers. Unless payment terms, pricing, and processes change, the number of days in the cycle may remain similar, but the absolute cash required to support it rises sharply.
Consider a manufacturer with a 70-day working capital cycle and monthly sales of $1 million. Roughly speaking, it needs to fund about 70 days of operating outflows, perhaps several million dollars, depending on margins and cost structure. If sales grow to $2 million per month while the cycle stays at 70 days, the working capital requirement roughly doubles. If the company does not secure additional funding or improve the cycle, it can experience a cash crunch even as revenue and profits grow.
This paradox is well documented in small business and mid-market finance research by institutions such as the World Bank at https://www.worldbank.org/, which notes that constrained access to working capital is a recurring barrier to growth in emerging and developed markets. Surveys from organizations like the OECD at https://www.oecd.org/ and central banks including the Bank of England at https://www.bankofengland.co.uk/ have also highlighted how tightening credit conditions or supply-chain disruptions can quickly lengthen working capital cycles, particularly for smaller firms with limited bargaining power.
Rapid growth can also create operational stress that indirectly lengthens the cycle. Stockouts and rushed purchasing may lead to higher safety inventories. Weak credit control during a sales push can increase overdue receivables. Supplier relationships may be strained by larger order volumes without clear payment frameworks. All of this means that growing companies need to treat working capital as a strategic issue, not a back-office detail.
Readers interested in how these dynamics intersect with macro trends such as inflation and interest rates may find additional context in our coverage of economics and world business news.
Breaking down the components: inventory, receivables, and payables
Each part of the working capital cycle reflects different operational realities and levers.
Inventory (DIO) captures how long products or materials sit before being sold or used. For manufacturers and retailers, inventory is often the largest component of working capital. High DIO can reflect deliberate strategy-such as holding buffer stock to protect against supply disruptions-or inefficiency, such as poor forecasting or slow-moving SKUs. Analytics, demand planning, and supply-chain visibility are critical here. Research by consulting firms and industry bodies, often summarized by sources like McKinsey & Company at https://www.mckinsey.com/ and Deloitte at https://www2.deloitte.com/, has shown that better forecasting and inventory segmentation can materially reduce DIO without harming service levels.
Receivables (DSO) reflect how long it takes to collect cash after revenue is recognized. DSO is shaped by contractual terms, customer credit quality, billing accuracy, and collection discipline. In many B2B sectors, standard terms of 30-60 days have been stretching, with some large buyers pushing for 90 days or more. Late payments are a persistent problem for SMEs; data from organizations such as the European Commission at https://commission.europa.eu/ and US Small Business Administration at https://www.sba.gov/ show that payment delays can be a major driver of insolvencies, even among otherwise viable firms.
Payables (DPO) represent the flip side: how long a company takes to pay its suppliers. Extending DPO improves cash in the short term, but aggressive stretching can damage supplier relationships, reduce bargaining power, or even lead to supply disruptions. Large corporates sometimes run structured "supplier financing" programs, where banks pay suppliers early in exchange for a fee while the corporate keeps longer terms; such arrangements have attracted scrutiny from regulators and standard setters, including the International Federation of Accountants at https://www.ifac.org/, because of transparency concerns.
The art of working capital management is balancing these three levers in a way that supports sustainable operations and growth, rather than maximizing one metric at the expense of others.
Sector differences: why cycles vary so widely
Working capital cycles can differ dramatically between industries, reflecting business models, bargaining power, and operational constraints.
Large supermarket chains and e-commerce marketplaces often enjoy negative working capital cycles. Customers typically pay immediately (online or at checkout), while suppliers may be on 30-90 day terms. This means the business effectively uses supplier credit and customer prepayments to fund operations. Public filings from retailers such as Walmart at https://www.walmart.com/ or Amazon at https://www.amazon.com/ illustrate this dynamic in their cash flow statements and notes.
In contrast, manufacturers and construction companies often face long positive cycles. They may buy raw materials months before products are completed, hold work-in-progress inventory, and then offer extended credit to customers on large contracts. While milestone billing and deposits can partially offset this, the net effect is often a heavy working capital burden, particularly when projects grow in size.
Software-as-a-service (SaaS) and subscription businesses, when structured with upfront annual payments, can have very short or negative cycles. Cash is collected before services are fully delivered, and direct cost of sales may be relatively low. However, high customer acquisition costs and deferred revenue accounting can complicate the picture. Investors and analysts typically look at cash burn and customer lifetime value alongside working capital metrics in such models.
Export-oriented businesses or those selling into markets with weaker legal enforcement may experience longer DSO due to cross-border logistics, currency issues, and collection challenges. Trade finance tools, such as letters of credit and export credit insurance, provided by institutions like export credit agencies and supported by bodies such as the World Trade Organization at https://www.wto.org/, play an important role in mitigating these risks but can add complexity and cost.
Understanding the norms and constraints of a specific sector is essential before judging whether a company's working capital cycle is healthy. Benchmarks from industry groups, banks, and research houses can be useful, but management needs to interpret them in light of the firm's own strategy and risk appetite.
Practical levers to improve the working capital cycle
Growing companies have more influence over their working capital cycle than they often realize. While some factors are structural, many are operational or contractual and can be changed with focused effort.
On the inventory side, businesses can invest in better demand forecasting, SKU rationalization, and supply-chain collaboration. Techniques such as just-in-time replenishment, vendor-managed inventory, and sales and operations planning (S&OP) can reduce DIO, though they may require robust data and close supplier relationships. Digital tools, including AI-driven forecasting and real-time inventory tracking, are increasingly accessible even to mid-sized firms, a trend covered frequently in our tech and ai sections.
For receivables, tightening credit policies, conducting credit checks on new customers, and segmenting terms based on risk can help. Clear contracts, accurate and timely invoicing, and proactive follow-up on overdue accounts are basic but often under-resourced disciplines. Some companies introduce small discounts for early payment or use electronic invoicing and automated reminders to accelerate cash collection. External guidance from professional bodies such as Chartered Institute of Management Accountants (CIMA) at https://www.cimaglobal.com/ and Association of Chartered Certified Accountants (ACCA) at https://www.accaglobal.com/ often emphasizes embedding receivables management in sales and customer-service processes rather than treating it as a purely back-office function.
On the payables front, negotiating longer but realistic terms with suppliers, aligning payment runs with cash inflows, and consolidating purchases to gain bargaining power can all extend DPO responsibly. However, companies should be cautious not to damage critical supplier relationships or reputation by unilaterally stretching payments. Collaborative approaches, such as agreeing volume-based discounts or participating in supply-chain finance programs, can improve both parties' positions.
Ultimately, effective working capital management requires cross-functional collaboration. Sales, operations, procurement, and finance need to share data and incentives. Linking performance metrics and bonuses to cash conversion, not just revenue or profit, is one way to embed this mindset.
Financing tools: bridging gaps in the cycle
Even with strong internal management, many growing companies need external financing to bridge the gap between cash outflows and inflows. A range of instruments exists, each with trade-offs in cost, flexibility, and risk.
Traditional bank overdrafts and working capital lines of credit remain common, particularly for firms with solid banking relationships and collateral. Banks and regulators such as the European Central Bank at https://www.ecb.europa.eu/ and the US Federal Reserve at https://www.federalreserve.gov/ monitor these exposures closely, especially for smaller and more leveraged borrowers.
Invoice financing and factoring allow companies to unlock cash tied up in receivables by selling invoices or borrowing against them. This can shorten the effective DSO but comes with fees and, in some structures, potential customer-perception issues. Supply-chain finance or reverse factoring, often arranged by large buyers in partnership with banks or fintechs, can help suppliers receive early payment while buyers maintain longer terms.
Inventory finance enables borrowing against stock, particularly in sectors with standardized, easily valued goods. However, lenders may require tight controls and regular reporting. For export-driven firms, trade finance instruments, including letters of credit and export working capital guarantees, supported by agencies like the US Export-Import Bank at https://www.exim.gov/, can mitigate risk and improve liquidity.
Equity and quasi-equity funding-venture capital, private equity, or convertible instruments-do not directly shorten the working capital cycle but can provide the capital cushion needed to sustain a long cycle during rapid expansion. Investors, however, increasingly scrutinize cash conversion and working capital discipline as part of due diligence, especially in capital-intensive or lower-margin businesses.
For founders and finance leaders evaluating these options, the key is to model how each instrument affects cash flow, covenants, and control under different growth and stress scenarios, rather than focusing solely on headline interest rates.
Governance, forecasting, and early warning signs
Robust working capital management relies on governance and forward-looking analysis, not just historical ratios. Growing companies benefit from integrating working capital metrics into their regular management reporting and board discussions.
Rolling 13-week cash flow forecasts, updated frequently, can reveal upcoming pinch points well before they become crises. Scenario analysis-testing the impact of longer customer payment times, inventory shocks, or supplier term changes-helps management plan contingencies. Many best-practice guides from organizations such as the Institute of Chartered Accountants in England and Wales (ICAEW) at https://www.icaew.com/ emphasize aligning short-term cash forecasting with longer-term strategic planning and capital budgeting.
Warning signs that a working capital cycle is becoming problematic include persistent increases in DSO or DIO without a clear strategic rationale, growing overdue receivables, rising reliance on emergency overdrafts, or frequent pressure from key suppliers over late payments. A disconnect between reported profit growth and weak or negative operating cash flows is another red flag that investors and lenders watch closely.
Boards and founders should also be alert to cultural signals: if sales teams routinely promise extended terms to close deals, or if procurement stretches suppliers beyond agreed terms, underlying incentives and governance may need re-design. Linking performance indicators to cash generation and embedding working capital considerations in pricing, contracting, and operational decisions can reduce these tensions.
How working capital cycles shape strategic choices
For growing companies, the working capital cycle is not merely an efficiency metric; it shapes strategic options. A business with a short or negative cycle can often self-fund a significant portion of its growth, reinvesting customer cash into expansion. This can support aggressive pricing, faster market entry, or higher R&D spending without equivalent reliance on external capital.
By contrast, a company with a long, capital-intensive cycle needs to be more selective about growth pace, contract structure, and customer mix. It may prioritize customers with stronger payment discipline, insist on deposits or milestone billing, or seek long-term committed financing before taking on large projects. Strategic partnerships, joint ventures, or asset-light models can be ways to reduce working capital intensity while still accessing growth.
In an environment of higher interest rates and tighter credit, which many economies have experienced in recent years, the cost of carrying large working capital balances rises. This can tilt competitive advantage toward firms that manage their cycles better. It also increases the importance of macro-economic awareness-tracking inflation, rates, and credit conditions-topics regularly covered in our business, news, and trade reporting.
Ultimately, understanding and actively managing the working capital cycle allows growing companies to align their financial engine with their strategic ambitions. Rather than being surprised by cash strains in the middle of a growth spurt, management can design commercial terms, operations, and financing structures that support sustainable expansion, even in more volatile global markets.
