How AI is Reshaping Global Supply Chain Management

Last updated by Editorial team at dailybusinesss.com on Thursday 16 July 2026
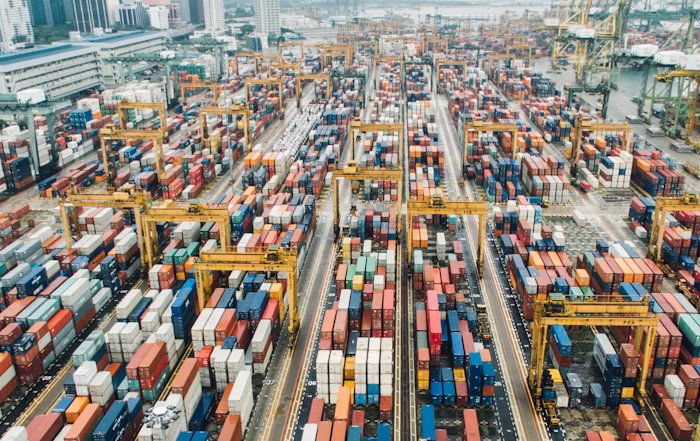
Article Image for How AI is Reshaping Global Supply Chain Management

How AI is Reshaping Global Supply Chain Management

A New Operating System for Global Commerce

Oh, and now artificial intelligence has moved from experimental pilot projects to the core operating system of global supply chains, quietly orchestrating how raw materials, components and finished products move between continents, industries and consumers. For the business news and latest fact seeking community of DailyBusinesss.com, which usually includes executives, investors, founders and policymakers across North America, Europe, Asia and beyond, the transformation is no longer theoretical; it is visible in the way forecasts are made, factories are scheduled, ships are routed, inventories are financed and risks are priced. What was once a back-office function has become a strategic capability that directly shapes competitiveness, profitability and resilience.

This shift has been accelerated by a series of shocks and structural changes that exposed the fragility of traditional supply chain models, including the pandemic-era disruptions, geopolitical tensions, climate-related events and the rapid digitization of commerce. In response, leading organizations have turned to AI not as a standalone technology but as an integrated layer across planning, procurement, logistics, finance and customer service. For decision-makers following the evolving coverage on global business and trade at DailyBusinesss.com, understanding how AI is rewiring these systems has become essential for strategy, investment and risk management.

From Linear Chains to Intelligent, Adaptive Networks

The classic linear supply chain model, moving from supplier to manufacturer to distributor to retailer, has been replaced by complex, multi-tier networks that span thousands of suppliers across dozens of countries. In this environment, human planners using spreadsheets and static enterprise systems could not keep pace with the volatility in demand, transportation capacity, commodity prices and regulatory changes. AI, particularly machine learning and advanced analytics, has emerged as the only viable way to interpret the enormous volume of signals flowing through these networks and convert them into timely, actionable decisions.

Modern AI-driven platforms ingest data from internal systems such as ERP and warehouse management tools, as well as external sources including port congestion data, weather forecasts, geopolitical risk feeds and even social media sentiment. Organizations that once relied on monthly or weekly planning cycles are now moving toward near real-time decision-making, in which AI continuously updates demand forecasts, recommends production adjustments and reroutes shipments based on the latest conditions. Readers who follow technology and AI developments on DailyBusinesss.com will recognize this as part of a broader trend toward intelligent automation across the enterprise, but in supply chain management the impact is particularly profound because small improvements in accuracy and timing can translate into substantial financial and operational gains.

Demand Forecasting in an Unpredictable World

Demand forecasting has historically been one of the most challenging aspects of supply chain management, especially for businesses operating across the United States, Europe and Asia where consumer preferences, regulatory environments and macroeconomic conditions differ significantly. AI-based forecasting models now combine traditional time-series analysis with machine learning techniques that can detect nonlinear patterns, seasonality shifts and emerging trends that conventional methods often miss. These systems draw on data such as online search trends, point-of-sale transactions, marketing campaigns, macroeconomic indicators and even mobility data to generate more granular, location-specific forecasts.

For global companies, this means they can better anticipate demand fluctuations in markets like Germany, the United Kingdom, Canada or Japan and align inventory, production and logistics accordingly. Organizations such as Amazon, Walmart and Alibaba have publicized their use of AI to improve forecast accuracy, but the same capabilities are increasingly accessible to mid-sized manufacturers and retailers through cloud-based solutions. Platforms from Microsoft Azure, Google Cloud and Amazon Web Services now offer advanced forecasting tools that can be integrated into existing systems, while research from institutions such as the MIT Center for Transportation & Logistics and the Stanford Digital Economy Lab continues to refine best practices for AI-enabled planning.

The financial implications of improved forecasting are significant. By reducing forecast error, companies can lower safety stock levels, cut working capital requirements and reduce the risk of stockouts or markdowns. For investors and finance professionals following markets and corporate performance through DailyBusinesss.com, AI-driven forecasting is increasingly viewed as a key differentiator in sectors ranging from consumer goods to automotive and electronics, influencing valuations and capital allocation decisions.

Intelligent Planning, Production and Inventory Optimization

Beyond forecasting, AI is reshaping how companies plan production, allocate capacity and manage inventory across global networks. Traditional planning tools struggled to account for the intricate constraints of modern operations, such as varying lead times, supplier reliability, transportation bottlenecks and regulatory requirements across multiple jurisdictions. AI-based optimization engines can now model these complex systems in far greater detail, running thousands of scenarios to identify the most efficient and resilient plans.

Manufacturers in Germany, South Korea, the United States and other industrial powerhouses are using AI to synchronize production schedules with supplier deliveries, labor availability and energy prices. By leveraging predictive models that anticipate machine failures, quality deviations or labor shortages, they can proactively adjust production plans to minimize disruptions. Organizations like Siemens, Bosch and Toyota have invested heavily in AI-enabled "digital twins" of their factories and supply chains, allowing them to simulate the impact of changes in demand, supplier performance or transportation conditions before implementing them in the real world. Learn more about how digital twins are evolving in industrial settings through resources from the World Economic Forum.

Inventory optimization has also been transformed. AI systems can segment inventory by demand volatility, margin contribution and criticality, then recommend differentiated strategies for each category. For example, slow-moving but critical components for aerospace or medical devices may warrant higher safety stock, while fast-moving consumer goods in stable markets might be managed through just-in-time replenishment. These approaches are being documented and refined by organizations such as the Council of Supply Chain Management Professionals and the APICS/ASCM, which have become important reference points for practitioners seeking to modernize their operations.

For the readership of DailyBusinesss.com, many of whom oversee cross-border operations or investments, the key takeaway is that AI-enabled planning is not just about efficiency but also about resilience. In an era of frequent disruptions, the ability to re-plan rapidly based on new data has become a core strategic capability, influencing where companies locate production, how they structure supplier relationships and how they manage capital-intensive assets.

Logistics, Routing and Real-Time Visibility

Perhaps the most visible impact of AI in supply chain management is in logistics, where the technology is being applied to routing, capacity management, last-mile delivery and real-time visibility. Global shipping lanes, air freight networks and trucking routes have become more unpredictable due to climate events, labor disputes and geopolitical tensions, as seen in disruptions to major ports and canals in recent years. AI-driven systems analyze vessel positions, port congestion, customs clearance times and weather forecasts to recommend optimal routing decisions that balance speed, cost and risk.

Major logistics providers such as DHL, UPS and Maersk have deployed AI to predict arrival times more accurately, optimize container utilization and reduce fuel consumption. Startups in Singapore, the Netherlands and the United States are using machine learning to match freight loads with available capacity in real time, improving asset utilization and reducing empty miles. For last-mile delivery in dense urban areas like London, New York, Tokyo or Paris, AI is used to cluster deliveries, optimize driver routes and dynamically adjust to traffic conditions, a trend documented by organizations like the International Transport Forum.

Real-time visibility platforms have become central to this transformation. By combining IoT sensors, telematics data and AI-based anomaly detection, these platforms provide end-to-end tracking of shipments, temperature conditions for sensitive goods, and potential delays at borders or warehouses. Businesses that rely on complex international flows, from pharmaceutical companies to electronics manufacturers, now expect this level of transparency as standard. Readers interested in the broader implications of this data-rich environment can explore technology and logistics coverage at DailyBusinesss.com, where the convergence of AI, IoT and cloud computing is a recurring theme.

Financial Flows, Trade Finance and Risk Pricing

AI's influence on supply chains is not limited to physical flows; it is increasingly central to the financial architecture that underpins global trade. Trade finance, supply chain finance and working capital optimization have traditionally depended on manual document processing, credit assessments and static risk models. AI is automating these processes, enabling faster, more accurate evaluation of counterparties and transactions, and opening new financing options for small and medium-sized suppliers across emerging markets in Asia, Africa and South America.

Banks and financial institutions, including HSBC, JPMorgan Chase and Standard Chartered, are using AI to analyze trade documents, shipping records and transactional histories to detect fraud, assess credit risk and structure financing facilities that align with actual supply chain performance. Blockchain-based platforms and digital trade documentation, supported by organizations such as the International Chamber of Commerce, are increasingly integrated with AI engines that monitor compliance, sanctions exposure and ESG-related risks.

For investors following finance and investment insights at DailyBusinesss.com, this convergence of AI, finance and supply chains is reshaping risk-return profiles across sectors. Companies that can demonstrate resilient, transparent and AI-optimized supply chains often secure more favorable financing terms, while those with opaque or fragile networks face higher capital costs. At the same time, the rise of trade-related digital assets and tokenized invoices intersects with developments in crypto and digital finance, creating new opportunities and regulatory questions for markets in the United States, Europe and Asia.

Workforce, Skills and the Future of Employment

The deployment of AI in supply chain management has significant implications for employment, workforce skills and organizational design. Contrary to simplistic narratives about automation replacing jobs, the reality observed across regions such as North America, Europe and East Asia is more nuanced. Routine, repetitive tasks in planning, data entry and transactional procurement are increasingly automated, but new roles are emerging in data science, AI model governance, exception management and cross-functional coordination.

Supply chain professionals are transitioning from manual planners to orchestrators who interpret AI-generated recommendations, manage trade-offs between cost, service and risk, and collaborate with stakeholders across finance, sales, sustainability and compliance. This shift requires new competencies in analytics, scenario thinking and digital literacy, prompting companies and educational institutions to redesign training programs. Organizations such as the World Bank and the OECD have highlighted the importance of upskilling for the future of work, particularly in logistics hubs across Europe, Asia and Africa.

For readers of DailyBusinesss.com focused on employment and talent trends, the message is clear: supply chain functions are becoming more strategic and data-driven, and the most successful professionals will be those who can blend operational experience with fluency in AI tools and data interpretation. Companies that invest in workforce development, rather than viewing AI solely as a cost-cutting tool, are better positioned to realize the full benefits of intelligent supply chains while maintaining employee engagement and institutional knowledge.

Sustainability, ESG and Responsible Supply Chains

Sustainability has moved from a peripheral concern to a central driver of supply chain strategy, especially for businesses operating in heavily regulated markets such as the European Union, the United Kingdom and increasingly in North America and parts of Asia-Pacific. AI plays a critical role in helping companies measure, manage and reduce the environmental and social impacts of their supply chains, aligning with regulations like the EU's Corporate Sustainability Reporting Directive and emerging due diligence laws in Germany, France and other jurisdictions.

AI systems can estimate carbon emissions across different transportation modes, suppliers and manufacturing processes, enabling companies to design lower-emission networks and optimize mode choices between air, sea, rail and road. They can also analyze supplier data, audit reports and open-source information to identify potential labor violations, deforestation risks or other ESG concerns deep within multi-tier supply chains. Organizations such as the UN Global Compact and the Ellen MacArthur Foundation have highlighted the importance of data and analytics in advancing circular economy and responsible sourcing initiatives, while AI provides the practical mechanism to operationalize these goals.

Readers who follow sustainable business practices on DailyBusinesss.com will recognize that AI-enabled transparency is becoming a competitive necessity, not merely a compliance exercise. Investors, customers and regulators are demanding verifiable data on emissions, human rights and ethical sourcing, and AI is often the only way to analyze and report on the vast, fragmented datasets involved. Companies that can demonstrate credible, AI-backed ESG performance are more likely to attract capital, secure premium contracts and maintain access to key markets in Europe, North America and Asia.

Cybersecurity, Resilience and Systemic Risk

As supply chains become more digitized and AI-dependent, they also become more exposed to cyber threats, data breaches and systemic vulnerabilities. The integration of AI with IoT devices, cloud platforms and third-party systems creates a complex attack surface that adversaries can exploit, potentially disrupting operations across multiple regions and sectors simultaneously. Incidents involving ransomware attacks on logistics providers and critical infrastructure have underscored the importance of robust cybersecurity and AI governance.

Organizations such as the Cybersecurity and Infrastructure Security Agency (CISA) in the United States and the European Union Agency for Cybersecurity (ENISA) have emphasized the need for secure-by-design architectures, continuous monitoring and incident response capabilities that leverage AI to detect anomalies and suspicious behavior. However, AI itself can introduce new risks, such as biased decision-making, opaque model behavior and vulnerabilities to data poisoning or adversarial attacks. Businesses must therefore implement strong governance frameworks, including model validation, access controls and clear accountability for AI-driven decisions.

For the global readership of DailyBusinesss.com, which includes leaders in technology, manufacturing, logistics and finance, resilience is now understood as a multi-dimensional concept encompassing physical, financial, cyber and reputational aspects. AI can enhance resilience by enabling faster detection of disruptions and more agile responses, but only if it is deployed within a robust governance and security framework that spans the entire ecosystem of suppliers, partners and service providers.

Regional Dynamics and Geopolitical Considerations

AI-driven supply chain management does not operate in a geopolitical vacuum. Governments in the United States, China, the European Union, Japan, South Korea and other major economies are actively shaping the regulatory and competitive landscape for AI and digital trade. Policies related to data localization, AI safety, export controls and industrial strategy influence how companies design their supply chain architectures, where they host data and which AI providers they can engage.

For example, initiatives in the European Union around trustworthy AI and digital sovereignty, as well as industrial policies in the United States and East Asia aimed at securing semiconductor, battery and critical mineral supply chains, are prompting companies to reconfigure sourcing strategies and manufacturing footprints. The World Trade Organization and regional trade agreements in Asia-Pacific, Europe and North America are grappling with how to incorporate digital trade, data flows and AI-enabled services into their frameworks, while national security concerns increasingly intersect with commercial decisions.

Executives and investors who rely on world and macroeconomic analysis from DailyBusinesss.com are acutely aware that supply chains are now central to national resilience strategies. AI, as the intelligence layer of these networks, is both a competitive asset and a potential point of leverage in geopolitical competition, making it essential for businesses to monitor regulatory developments, diversify risk and cultivate scenario planning capabilities that account for policy shifts as well as market dynamics.

Strategic Imperatives for Business Leaders

For the top corporate leadership community that turns to DailyBusinesss.com for well researched insights across business strategy, investment, technology and trade, the cumulative message from the AI-driven transformation of supply chains is clear. First, AI in supply chain management is no longer an optional enhancement but a foundational capability that influences cost structures, service levels, risk exposure and sustainability performance. Second, successful deployment requires more than technology acquisition; it demands a coherent strategy that integrates data infrastructure, organizational design, talent development, governance and ecosystem partnerships.

Companies across sectors and regions must assess their current digital maturity, identify high-impact use cases in forecasting, planning, logistics, finance and ESG, and then prioritize investments that build scalable, interoperable capabilities rather than isolated pilots. Collaboration with technology providers, academic institutions and industry consortia can accelerate learning and reduce implementation risk, while cross-functional governance structures ensure that AI deployment aligns with corporate values, regulatory requirements and stakeholder expectations. Resources from organizations such as the Gartner Supply Chain practice and the Harvard Business Review provide additional perspectives on leading practices and emerging trends.

Finally, as AI continues to evolve, the competitive frontier will shift from basic automation toward more advanced capabilities in scenario-based planning, autonomous decision-making and self-optimizing networks. Businesses that cultivate a culture of experimentation, transparency and continuous improvement, while maintaining a clear focus on trust, ethics and human judgment, will be best positioned to capture the full value of AI-enabled supply chains. For the rapid growing community of DailyBusinesss.com, like founders, executives, investors and policymakers from the United States to Singapore, from Germany to Brazil and South Africa, the question is no longer whether AI will reshape supply chain management, but how quickly they can adapt their strategies, organizations and investments to thrive in this new era of intelligent, interconnected commerce.

Thanks for taking the time to read the full article today, make sure you bookmark us and subscribe and come back here tomorrow!

The New Era of Climate-Focused Investment Banking

Last updated by Editorial team at dailybusinesss.com on Wednesday 15 July 2026
Article Image for The New Era of Climate-Focused Investment Banking

The New Era of Climate-Focused Investment Banking

Climate Finance Moves to the Center of Global Capital Markets

Finally climate finance has moved from a ignored niche concern to a central organizing force in global capital markets, and nowhere is this shift more visible than in the transformation of investment banking. What began a decade ago as a wave of green bonds and sustainability reports has evolved into a structural realignment of how capital is raised, allocated, priced, and regulated across major financial centers in the United States, Europe, and Asia, with growing momentum in emerging markets from Brazil to South Africa. For the top readers of DailyBusinesss and its global audience of company decision-makers, the new era of climate-focused investment banking is not a distant trend but a direct influence on corporate strategy, portfolio construction, regulatory risk, and long-term competitiveness in a decarbonizing world.

Climate-aligned capital is now shaped by a confluence of forces: increasingly stringent policy frameworks such as the European Union's Green Deal and Carbon Border Adjustment Mechanism, evolving disclosure mandates from regulators including the U.S. Securities and Exchange Commission, rapid advances in clean technology, and rising expectations from institutional investors and asset owners who are integrating climate risk into fiduciary duty. As leading institutions such as Goldman Sachs, J.P. Morgan, HSBC, and BNP Paribas recalibrate their business models around decarbonization, climate transition, and resilience, investment banking is becoming a primary engine of the net-zero transition rather than a peripheral commentator on it.

Readers following the broader evolution of markets on DailyBusinesss markets coverage will recognize that this is no longer a story about isolated green products; instead, climate is now embedded in valuations, covenants, credit spreads, M&A strategy, and even talent recruitment and retention, reshaping the competitive landscape across sectors from energy and transport to real estate, technology, and consumer goods.

From Green Niche to Core Banking Strategy

The first phase of climate-related finance, which peaked in the late 2010s, was characterized by a proliferation of green bonds, sustainability-linked loans, and ESG-branded funds. These instruments, often guided by frameworks from organizations such as the International Capital Market Association, helped mobilize capital for renewable energy, energy efficiency, and low-carbon infrastructure, and they provided a testing ground for standards and verification practices. However, they also revealed challenges around greenwashing, inconsistent taxonomies, and limited impact measurement.

By the early 2020s, as climate science and policy hardened, the narrative shifted from incremental "green" additions to a broader question of how entire balance sheets, portfolios, and corporate strategies could align with a 1.5°C trajectory as articulated by the Intergovernmental Panel on Climate Change and reflected in the Paris Agreement. Institutional investors, guided by initiatives such as the Glasgow Financial Alliance for Net Zero, began to expect banks to move beyond marketing labels and embed climate considerations in core risk management, underwriting standards, and capital allocation.

This pressure coincided with surging innovation in clean technologies and digital tools. The declining cost curves of solar, wind, and battery storage documented by the International Energy Agency and the rise of green hydrogen, carbon capture, and industrial decarbonization solutions created a substantial pipeline of bankable projects. At the same time, advances in data analytics and artificial intelligence enabled more sophisticated modeling of climate risk and opportunity, a theme explored frequently in DailyBusinesss AI analysis, where climate-tech applications of machine learning are increasingly central to investment theses.

In this environment, leading investment banks began to reposition their climate activities from side-lines to strategy. Dedicated sustainable finance units evolved into cross-bank platforms influencing sector coverage, product design, and capital allocation, while climate targets became integrated into executive compensation, client selection, and risk appetite frameworks across North America, Europe, and Asia-Pacific.

Regulatory and Policy Forces Redefining Climate Risk

The regulatory environment has been a decisive catalyst in the evolution of climate-focused investment banking. In the United States, proposals and subsequent rules from the SEC on climate-related disclosures, coupled with stress-testing and supervisory expectations from the Federal Reserve and other prudential regulators, have pushed banks to quantify physical and transition risks across their lending and underwriting portfolios. In Europe, the European Central Bank and national supervisors have gone further, embedding climate risk into the Supervisory Review and Evaluation Process and requiring banks to demonstrate credible plans for managing exposures to high-emitting sectors.

Globally, the emergence of the International Sustainability Standards Board has accelerated convergence around climate-related reporting, building on the earlier work of the Task Force on Climate-related Financial Disclosures. As more jurisdictions in Asia, including Singapore, Japan, and South Korea, move toward mandatory or quasi-mandatory climate disclosure regimes, cross-border capital flows are increasingly governed by a common language of climate risk metrics, scenario analysis, and transition plans. For executives and investors tracking these developments, resources from the OECD and World Bank offer valuable context on how climate policy and financial regulation interact with trade, development, and capital markets.

For a business audience, the implications are profound. Climate risk is no longer viewed as an optional ESG overlay but as a financial risk category comparable to credit, market, and operational risk. Investment banks are building dedicated climate risk teams, integrating climate scenarios into enterprise-wide stress testing, and recalibrating sector strategies in anticipation of policy shocks such as carbon pricing, fossil fuel phase-outs, and technology mandates. The coverage on DailyBusinesss economics insights frequently highlights how these regulatory shifts intersect with macroeconomic conditions, influencing inflation, industrial policy, and long-term growth trajectories in regions from the United States and European Union to China and Brazil.

New Products and Structures in Climate-Focused Investment Banking

The product toolkit of climate-focused investment banking has expanded significantly beyond traditional green bonds. Sustainability-linked bonds and loans tie financing costs to measurable climate or sustainability performance indicators, encouraging corporate issuers in sectors such as shipping, aviation, agriculture, and manufacturing to commit to science-based targets. Transition bonds, while still evolving in terms of standards, aim to finance decarbonization in hard-to-abate sectors like steel, cement, and chemicals, where immediate zero-carbon solutions may not yet be commercially viable.

In parallel, structured finance has adapted to support distributed and emerging climate solutions. Securitization of rooftop solar portfolios, energy-efficient mortgages, and electric vehicle leases has created new asset classes that appeal to institutional investors seeking yield with climate alignment. Blended finance structures, often involving multilateral development banks such as the World Bank or Asian Development Bank, have been used to de-risk climate projects in emerging markets across Africa, South America, and Southeast Asia, crowding in private capital where perceived risks would otherwise be prohibitive. Those following sustainable capital flows can learn more about sustainable business practices through the work of UNEP and its finance initiatives.

Equity capital markets have also been reshaped by climate themes. IPOs and follow-on offerings for climate-tech companies in fields such as grid optimization, battery technology, carbon management, and industrial automation have become major fixtures on exchanges in New York, London, Frankfurt, Toronto, Sydney, and Singapore. Private placements and late-stage growth financing are increasingly structured around climate-aligned metrics, with investment banks advising both founders and institutional investors on valuation, governance, and scaling strategies. Readers interested in how these dynamics intersect with entrepreneurship can explore DailyBusinesss founders coverage, where the stories of climate-focused founders in the United States, Europe, and Asia illustrate how investment banking expertise is being harnessed to accelerate commercialization and global expansion.

AI, Data, and the Quantification of Climate Risk

One of the defining features of the new era is the fusion of climate science, financial modeling, and artificial intelligence. Investment banks are deploying machine learning and advanced analytics to translate complex climate scenarios into financial impacts at the asset, portfolio, and systemic levels. By integrating geospatial data, satellite imagery, and climate models from research institutions and agencies such as NASA and the European Space Agency, banks can assess physical risks such as flooding, heat stress, and storm damage across real estate, infrastructure, and supply chains.

At the same time, natural language processing and large-scale data aggregation allow banks to analyze corporate disclosures, regulatory developments, and technological trends in real time, informing sector strategies and client engagement. For example, algorithms can detect shifts in policy sentiment around carbon pricing or identify emerging leaders in battery innovation, enabling investment bankers to advise clients on timing capital raises, acquisitions, or divestitures. The intersection of AI and climate finance is a recurring theme in DailyBusinesss technology reporting, where the focus is on how digital transformation is redefining both risk management and opportunity identification in financial services.

These capabilities are not merely technical enhancements; they are central to building trust with clients and regulators. Banks that can credibly quantify climate risk and opportunity, explain their methodologies, and demonstrate consistency across business lines are better positioned to win mandates, navigate supervisory scrutiny, and differentiate themselves in a crowded market for sustainable finance. The push from global standard-setting bodies such as the Financial Stability Board reinforces the expectation that climate risk analytics will become as integral to banking as credit scoring or market VaR.

Climate-Aligned M&A and Strategic Advisory

Beyond financing products, investment banks are playing an increasingly strategic role in advising corporations and investors on climate-driven mergers, acquisitions, divestitures, and partnerships. As governments from the United Kingdom and Germany to Japan, South Korea, and Canada roll out industrial policies and subsidies for clean technologies, companies are reconfiguring their portfolios to capture incentives, secure critical inputs, and manage regulatory exposure.

In sectors such as energy, utilities, and automotive, climate-aligned M&A is reshaping corporate structures. Traditional oil and gas majors are spinning off or acquiring renewable platforms, while utilities are consolidating around grid modernization, storage, and digital services. Automotive manufacturers are entering joint ventures for battery production, charging infrastructure, and software platforms, often guided by strategic advice from global investment banks that must balance climate objectives with shareholder value and competitive positioning. Readers exploring broader business strategy trends can find additional context in DailyBusinesss business analysis, where climate transition is treated as a structural force comparable to digitization or globalization.

Investment banks are also advising private equity firms and sovereign wealth funds as they recalibrate their portfolios in light of climate transition risks and opportunities. This includes identifying stranded asset risks in fossil-heavy holdings, structuring exits or transitions, and sourcing climate-themed investments in areas such as grid infrastructure, sustainable agriculture, green buildings, and circular economy models. Reports from organizations like the PRI and Ceres have underscored the growing expectation that long-term asset owners integrate climate considerations into stewardship and capital allocation, a trend that is now fully embedded in the advisory dialogues of leading investment banks.

Crypto, Carbon Markets, and Digital Climate Assets

For an audience attuned to digital assets and crypto through DailyBusinesss crypto coverage, the convergence of blockchain, tokenization, and climate finance is an area of intense interest and experimentation. While the early crypto ecosystem faced criticism for its energy intensity, particularly around proof-of-work mining, the past few years have seen a decisive shift toward proof-of-stake and other lower-carbon consensus mechanisms, as well as a surge of innovation in tokenized carbon credits, renewable energy certificates, and nature-based assets.

Investment banks are cautiously entering this space by exploring how distributed ledger technology can enhance transparency, traceability, and integrity in voluntary carbon markets and environmental commodities. Collaborations with organizations such as the World Bank's Climate Warehouse and initiatives under the World Economic Forum umbrella are testing how digital infrastructure can support cross-border carbon trading, avoid double counting, and align with emerging Article 6 mechanisms under the Paris Agreement. The goal is to create scalable, credible markets for carbon and environmental services that can complement traditional project finance and capital markets instruments.

However, the integration of crypto and climate finance also raises complex regulatory, reputational, and technical questions. Banks must navigate evolving rules from securities and commodities regulators in the United States, European Union, United Kingdom, Singapore, and other jurisdictions, while ensuring that digital climate assets meet robust standards for additionality, permanence, and social safeguards. This cautious but forward-looking engagement reflects a broader pattern in climate-focused investment banking: embracing innovation while maintaining rigorous standards of governance, risk management, and client protection.

Employment, Skills, and Organizational Change in Climate Banking

The transformation toward climate-focused investment banking is reshaping employment patterns, skills requirements, and organizational culture across global financial hubs. Banks are hiring climate scientists, data engineers, sustainability experts, and policy specialists alongside traditional financiers, creating multidisciplinary teams that can bridge the gap between climate science, regulation, and financial structuring. Cities such as New York, London, Frankfurt, Paris, Singapore, Hong Kong, and Sydney are becoming hubs for climate finance talent, with competition intensifying not only among banks but also with asset managers, consultancies, and technology firms.

At the same time, existing bankers are expected to upskill, integrating climate considerations into sector coverage, client dialogue, and deal structuring. Training programs, often developed in partnership with universities and organizations such as the CFA Institute, are becoming standard across large institutions. For professionals and students tracking these shifts, DailyBusinesss employment insights provide a lens on how climate and sustainability are influencing career paths in finance, consulting, technology, and corporate roles across North America, Europe, and Asia-Pacific.

Organizationally, banks are rethinking governance structures to ensure that climate strategy is coordinated across business lines. Board-level climate committees, chief sustainability officers with real authority, and cross-functional climate councils are now common in leading institutions. These structures aim to prevent fragmentation, align incentives, and ensure that climate commitments translate into concrete actions in lending, underwriting, and advisory activities rather than remaining confined to corporate communications.

Regional Dynamics: A Global but Uneven Transition

While climate-focused investment banking is a global phenomenon, it is unfolding unevenly across regions, reflecting differences in policy, market maturity, and industrial structures. In Europe, where the EU Green Deal, taxonomy regulations, and mandatory climate disclosure have advanced rapidly, banks in countries such as Germany, France, Netherlands, and the Nordic region have generally been at the forefront of climate integration, often collaborating closely with policymakers and development banks. The United Kingdom, post-Brexit, has sought to position London as a leading center for green and sustainable finance, leveraging its deep capital markets and regulatory innovation.

In North America, the United States and Canada have seen a more fragmented but accelerating trajectory, with federal policies, state-level initiatives, and market-driven pressures combining to push banks toward climate alignment. Large U.S. banks with global operations face particular scrutiny from both domestic regulators and international stakeholders, especially regarding their continued financing of fossil fuel activities. Meanwhile, in Asia, jurisdictions such as Singapore, Japan, South Korea, and increasingly China are building robust frameworks for green finance, often tied to broader industrial strategies in clean energy, electric vehicles, and advanced manufacturing.

Emerging markets in Africa, South America, and Southeast Asia present both immense opportunity and significant complexity. Countries such as Brazil, South Africa, Malaysia, and Thailand are critical for global climate goals due to their natural resources, biodiversity, and growing energy demand, but they often face higher financing costs and perceived risks. Investment banks are working with multilateral institutions, development finance entities, and local partners to design blended finance structures and risk-sharing mechanisms that can unlock climate investment at scale, a topic that intersects closely with DailyBusinesss world coverage on development, trade, and geopolitics.

Investment Strategies, Markets, and the Road to 2030

For institutional investors, corporates, and entrepreneurs who rely on DailyBusinesss for strategic insight, the evolution of climate-focused investment banking has direct implications for asset allocation, cost of capital, and competitive strategy through 2030 and beyond. Equity and credit markets are increasingly differentiating between companies with credible, well-governed transition plans and those exposed to regulatory, technological, or reputational climate risks. Index providers, rating agencies, and data firms are refining climate metrics, while stewardship and engagement expectations from asset owners in Europe, North America, and Asia are intensifying.

Investment banks sit at the intersection of these forces, shaping how capital flows into climate-aligned opportunities and how climate risks are priced. Their research arms are producing increasingly granular sectoral climate analyses, while their trading desks are building liquidity in green and sustainability-linked instruments. For investors seeking to position portfolios for the transition, understanding the evolving role of banks is as critical as following central bank policy or macroeconomic indicators, themes that are regularly explored in DailyBusinesss finance and investment sections and investment insights.

Looking ahead to 2030, the credibility of climate-focused investment banking will depend on demonstrable outcomes: measurable reductions in financed emissions, increased capital flows to emerging and developing markets, tangible progress in hard-to-abate sectors, and the integrity of new markets such as voluntary carbon and nature-based solutions. Organizations such as the UNFCCC, IEA, and NGFS will continue to provide benchmarks and oversight, but market participants themselves-banks, investors, corporates, and civil society-will determine whether the promises of climate finance translate into real-world decarbonization and resilience.

The Small Part of DailyBusinesss in a Climate-Driven Financial Future

As climate-focused investment banking becomes a defining feature of the global financial system, the need for clear, nuanced, and independent analysis grows ever more urgent. DailyBusinesss occupies a small but distinctive position in this landscape, serving readers who span corporate leadership, investment management, entrepreneurship, policy, and technology across the United States, United Kingdom, Europe, Asia, Africa, and the Americas. By connecting developments in climate finance with adjacent domains such as AI, crypto, trade, employment, and technology, the platform helps its audience navigate a transition that is as much about innovation and opportunity as it is about risk and regulation.

From in-depth reporting on sustainable finance and climate-aligned regulation to coverage of technological breakthroughs and founder stories, DailyBusinesss is committed to providing the experience-driven, expert, and trustworthy insights that business leaders and investors require today and beyond. Readers who wish to follow the continuing evolution of climate-focused investment banking and its implications for markets, economies, and societies can explore the broader ecosystem of coverage on DailyBusinesss tech and innovation pages and the main DailyBusinesss homepage, where climate, finance, and the future of business intersect every day. If you liked to what we had to say, make sure you check out our new content tomorrow, so don't forget to bookmark and subscribe today.

Why Founders Are Prioritizing Bootstrapped Growth

Last updated by Editorial team at dailybusinesss.com on Tuesday 14 July 2026
Article Image for Why Founders Are Prioritizing Bootstrapped Growth

Why Founders Are Prioritizing Bootstrapped Growth

A New Era of Founder Discipline

Well now a decisive shift has taken root in the global startup ecosystem: a growing number of founders across North America, Europe, Asia and beyond are deliberately turning away from the high-burn, venture-fueled playbook that dominated the 2010s and early 2020s, and are instead prioritizing bootstrapped growth as a strategic choice rather than a last resort. On dailybusinesss.com, this change is not viewed as a temporary reaction to tighter capital markets, but as a big realignment of incentives, risk appetite and entrepreneurial culture, as founders in the United States, the United Kingdom, Germany, Canada, Australia and other leading innovation hubs reassess what sustainable, resilient and personally rewarding company building really looks like.

This recalibration is unfolding against a backdrop of rising interest rates, more cautious institutional investors, a maturing technology stack and a more sophisticated global founder community that has learned from the excesses of the previous decade. As reports from organizations such as the World Bank and the International Monetary Fund show, global liquidity conditions have tightened and capital is no longer as forgiving as it once was, which has forced boards and management teams to reconsider the trade-offs between speed and durability. In parallel, the success stories of bootstrapped or lightly funded companies in software, fintech, e-commerce and B2B services have provided compelling evidence that disciplined growth, strong unit economics and a focus on profitability can coexist with innovation and market leadership, especially when founders retain control over their strategic direction and time horizons.

For readers of dailybusinesss.com who follow developments in business strategy and leadership, this shift toward bootstrapping is not simply about frugality; it is about experience, expertise, authoritativeness and trustworthiness being rewarded in the marketplace. Founders are discovering that capital efficiency is not merely a financial metric but a signal of operational excellence and strategic clarity that customers, partners and employees increasingly value.

Macroeconomic Headwinds and the Cost of Capital

The renewed interest in bootstrapped growth cannot be separated from the macroeconomic context that has defined the mid-2020s. The unprecedented monetary stimulus of the early 2020s, which had previously fueled record venture capital inflows and sky-high valuations, has given way to a more normalized interest rate environment in the United States, the Eurozone and many parts of Asia. Central banks, including the Federal Reserve in the United States and the European Central Bank in the Euro area, have signaled that the era of near-zero rates is definitively over, and this has had profound consequences for risk assets, including early-stage and growth-stage equity.

As yields on safer instruments have become more attractive, institutional investors from pension funds in Canada to sovereign wealth funds in Singapore have rebalanced their portfolios, demanding clearer pathways to profitability and more disciplined capital allocation from the private companies they back. The result, documented in global venture reports from organizations such as PitchBook and CB Insights, has been a reduction in mega-rounds, more down rounds, and a heightened scrutiny of business models that rely heavily on subsidies or aggressive discounting to gain market share. Learn more about the evolving dynamics of global markets and capital flows and their influence on founder decision-making.

In this environment, the cost of capital, both explicit and implicit, has risen. Equity financing now carries a higher expectation of governance oversight, performance milestones and exit timelines, which can compress the strategic flexibility of founders, especially in complex or emerging sectors such as artificial intelligence, climate tech and cross-border fintech. Many entrepreneurs in Germany, France, the Netherlands and the Nordic countries, who historically operated in ecosystems with strong public support for innovation, are finding that private capital has become more selective, which makes bootstrapping not only a viable path but in many cases a more attractive one.

The Strategic Appeal of Control and Optionality

Beyond macroeconomics, the surge in bootstrapped growth is driven by a strategic desire for control and optionality. Founders in markets as diverse as the United States, the United Kingdom, India, Singapore and Brazil increasingly recognize that the traditional venture-backed trajectory-rapid scaling, multiple funding rounds, and an eventual IPO or strategic sale-comes with a set of constraints that may not align with their personal or professional objectives.

When growth is funded primarily through revenue, customer prepayments and careful cash management, founders retain greater control over product roadmaps, hiring decisions and market positioning. They are less pressured to chase vanity metrics or to expand into new geographies prematurely, and more able to concentrate on building durable competitive advantages and strong customer relationships. For many readers of dailybusinesss.com who are founders or aspiring entrepreneurs, this resonates with a broader desire to build companies that can withstand economic cycles and regulatory shifts, particularly in sectors like finance and investment where trust and stability are paramount.

The concept of optionality is central here. Bootstrapped companies are not excluded from external capital; rather, they can approach investors from a position of strength, with proven revenue streams, validated products and more favorable negotiating leverage. This allows them to consider a wider range of financing instruments, including revenue-based financing, strategic minority stakes from corporate partners, or even selective private equity involvement at later stages, without ceding control or being forced into an exit timeline that does not serve the long-term interests of the business or its stakeholders.

Bootstrapping and the AI-Driven Productivity Revolution

One of the most important enablers of bootstrapped growth in 2026 is the extraordinary productivity leverage offered by artificial intelligence. Founders now have access to advanced AI infrastructure from providers such as OpenAI, Google Cloud, Microsoft Azure and Amazon Web Services, which allows lean teams to build, deploy and scale sophisticated products and internal tools with a fraction of the headcount and capital that would have been required only a few years ago. Learn more about how AI is reshaping technology and business models across industries.

In software development, AI-assisted coding tools have significantly reduced time-to-market and maintenance burdens, enabling bootstrapped startups in Canada, Australia and the Nordic countries to compete effectively with better-funded rivals. In marketing and sales, AI-driven personalization, automated outreach and predictive analytics have made it possible to run high-impact campaigns with minimal budgets, while customer support can increasingly be handled through intelligent chatbots and self-service portals, freeing human teams to focus on complex, high-value interactions.

Furthermore, AI has transformed internal decision-making processes. Founders can now rely on advanced analytics and forecasting to optimize pricing strategies, inventory levels, hiring plans and capital expenditures, improving cash flow management and reducing the risk of costly missteps. Organizations such as McKinsey & Company and the OECD have highlighted how AI-driven productivity gains are reshaping the global economy, and bootstrapped founders are among the most agile in harnessing these tools to build efficient, data-informed operations that scale responsibly.

Financial Discipline, Unit Economics and Sustainable Growth

Bootstrapped growth demands a level of financial discipline that, while challenging, can significantly increase the long-term resilience and credibility of a business. Founders who cannot rely on repeated equity injections must understand their unit economics in granular detail, carefully manage working capital and design business models that generate positive cash flow as early as possible. This is particularly evident in sectors such as B2B SaaS, professional services, e-commerce and niche manufacturing, where customer lifetime value, churn, gross margins and payback periods can be monitored and optimized with precision.

For readers of dailybusinesss.com who follow investment and valuation trends, this disciplined approach is increasingly appreciated by sophisticated investors who now prioritize sustainable revenue and profitability over sheer growth rates. Reports from organizations like Harvard Business School and INSEAD have emphasized that companies with strong unit economics and conservative balance sheets are better equipped to survive downturns, negotiate favorable terms with suppliers and partners, and seize opportunistic acquisitions when competitors falter.

In markets such as the United States, the United Kingdom and Germany, where regulatory scrutiny on financial reporting and consumer protection has intensified, bootstrapped companies often find that their conservative growth strategies align well with compliance requirements and stakeholder expectations. They are less exposed to accusations of predatory pricing, labor exploitation or misleading performance claims, which in turn strengthens their brand and makes them more attractive to enterprise customers, particularly in regulated sectors like financial services, healthcare and critical infrastructure.

Founder Well-Being, Culture and Long-Term Alignment

Another factor driving the adoption of bootstrapped strategies is a growing awareness of founder well-being and organizational culture. The hyper-growth model, with its relentless focus on fundraising, aggressive scaling and ambitious valuation targets, has been associated with burnout, ethical compromises and fragile cultures in high-profile cases from Silicon Valley to Berlin and Singapore. As research from institutions such as Stanford Graduate School of Business and London Business School has highlighted, the psychological toll of this approach can be substantial, affecting not only founders but entire leadership teams and workforces.

Bootstrapped founders, by contrast, often report a greater sense of autonomy and alignment between their personal values and business objectives. Without the constant pressure to meet external growth expectations, they can set more realistic milestones, invest in thoughtful hiring and prioritize long-term cultural health over short-term output. This is particularly relevant in knowledge-intensive sectors like AI, cybersecurity and advanced manufacturing, where attracting and retaining top talent in the United States, Canada, the United Kingdom, Germany and the Nordic countries requires a credible commitment to sustainable workloads and authentic mission-driven leadership.

For the audience of dailybusinesss.com, many of whom are founders or senior executives, this cultural dimension is closely connected to trustworthiness. Companies that grow at a measured pace, finance themselves responsibly and communicate transparently with employees, customers and partners are better positioned to build reputational capital that endures. Learn more about how these dynamics intersect with global employment and talent trends and the evolving expectations of highly skilled professionals.

Regional Perspectives: United States, Europe and Asia-Pacific

While the move toward bootstrapped growth is global, its expression varies across regions. In the United States, a robust ecosystem of accelerators, angel investors and revenue-based financing platforms has emerged to support founders who wish to grow primarily through customer revenue but still require targeted capital injections at key inflection points. Organizations such as Y Combinator and Techstars have refined their programs to emphasize sustainable business models and capital efficiency, reflecting a broader shift in Silicon Valley's narrative from growth-at-all-costs to responsible scaling.

In Europe, particularly in Germany, France, the Netherlands, Sweden and Denmark, the tradition of Mittelstand-style, family-owned enterprises and a strong emphasis on engineering excellence have made the bootstrapped ethos culturally resonant. Founders in these markets often build export-oriented B2B companies with a long-term horizon, and they are increasingly blending modern software and AI capabilities with conservative financial practices to create globally competitive yet resilient businesses. The European Investment Bank and national development banks have also played a role by offering debt instruments and guarantees that complement, rather than replace, revenue-driven growth.

Across Asia-Pacific, from Singapore and Japan to Australia and New Zealand, bootstrapped growth is often shaped by smaller domestic markets and the need to internationalize early. Founders in these regions are leveraging digital platforms, cross-border e-commerce and remote-first operations to access customers in North America and Europe without incurring heavy fixed costs. Organizations such as Enterprise Singapore and Austrade have supported these efforts through export promotion and innovation grants, but the core of many successful companies remains a disciplined, revenue-centric approach. Readers interested in the broader geopolitical and economic context can explore how these trends interact with world and trade developments and the evolving architecture of global commerce.

Crypto, Fintech and the Discipline of Market Cycles

The crypto and fintech sectors provide a particularly vivid illustration of why founders are prioritizing bootstrapped growth in 2026. The boom-and-bust cycles of digital assets, DeFi protocols and speculative token offerings in the early 2020s exposed the vulnerabilities of business models overly dependent on cheap capital and speculative enthusiasm. Regulatory interventions by authorities such as the U.S. Securities and Exchange Commission, the Financial Conduct Authority in the United Kingdom and the Monetary Authority of Singapore have further constrained unsustainable practices and pushed serious founders to adopt more conservative, revenue-focused strategies.

Today, successful fintech and crypto infrastructure companies in the United States, Europe and Asia are increasingly built on recurring revenue from institutional clients, enterprise-grade compliance and robust risk management frameworks, rather than on token appreciation alone. Bootstrapping or restrained fundraising has allowed these founders to focus on product reliability, security and regulatory alignment, which are essential for long-term survival in a sector where trust can evaporate quickly. For readers of dailybusinesss.com following crypto and digital asset innovation, this evolution underscores how market cycles can reinforce the value of prudence, governance and sustainable economics, even in highly disruptive industries.

Sustainability, Climate Risk and Responsible Capital Use

Environmental, social and governance considerations are also influencing founders' preference for bootstrapped growth. As climate risk becomes a central concern for regulators, investors and consumers in Europe, North America and Asia, companies are expected to demonstrate not only financial performance but also responsible resource use and long-term environmental stewardship. Organizations such as the United Nations Environment Programme, the World Economic Forum and the Task Force on Climate-related Financial Disclosures have highlighted the material risks associated with unsustainable practices, from supply chain disruptions to regulatory penalties and reputational damage.

Bootstrapped companies, which must be inherently frugal and efficient, are often well positioned to integrate sustainability into their core operations rather than treating it as an afterthought. Their need to minimize waste, optimize logistics and invest only in high-return projects naturally aligns with many principles of sustainable business, from energy efficiency to circular design. For founders and executives who follow sustainable business trends on dailybusinesss.com, this convergence of financial discipline and environmental responsibility offers a powerful narrative: building a lean company can be both economically and ethically advantageous, particularly in a world where regulators and customers in markets such as Germany, the Netherlands, Sweden and Japan are demanding demonstrable climate action.

The Evolving Role of Investors and Alternative Financing

The rise of bootstrapped growth does not imply the disappearance of external capital; rather, it is reshaping the role of investors and the structure of financing relationships. Venture capital firms in the United States, the United Kingdom, Germany and Singapore are increasingly positioning themselves as partners to already profitable or near-profitable companies, offering not only capital but also access to global networks, specialized expertise and strategic guidance. Private equity funds and family offices are likewise seeking opportunities to invest in founder-led, cash-generating businesses that have proven their models and are looking to accelerate expansion, professionalize governance or pursue acquisitions.

Alternative financing mechanisms have also gained prominence. Revenue-based financing, provided by firms such as Capchase and Pipe, allows companies with predictable recurring revenue to access growth capital without diluting ownership, repaying investors as a percentage of future revenue. Crowdfunding platforms, including Seedrs and Crowdcube in Europe, continue to offer community-oriented paths to capital that can complement bootstrapped growth, although regulatory frameworks vary by jurisdiction. For readers tracking financial innovation and capital markets, these developments illustrate how the boundaries between bootstrapped and funded companies are becoming more fluid, with a spectrum of options that founders can tailor to their risk tolerance and strategic ambitions.

Founders' Experience, Expertise and the Maturity of the Ecosystem

Perhaps the most underappreciated driver of the bootstrapped movement is the growing maturity of the global founder ecosystem itself. Many of today's entrepreneurs in the United States, the United Kingdom, Germany, India and Southeast Asia are second- or third-time founders, former senior executives of scale-ups, or alumni of large technology companies such as Google, Microsoft, Meta and Amazon, who bring deep operational experience and domain expertise to their ventures. Having witnessed both the benefits and pitfalls of aggressive fundraising, they are more inclined to design companies that can thrive on customer revenue and disciplined cost structures.

On dailybusinesss.com, this evolution is reflected in the stories of founders who have consciously chosen to raise minimal or no external capital, focusing instead on building profitable, enduring businesses in software, professional services, manufacturing, logistics and digital media. Many of these leaders emphasize that bootstrapping is not an ideology but a strategic framework that demands clarity of purpose, rigorous prioritization and a willingness to grow more slowly in exchange for greater resilience and autonomy. Readers interested in these journeys can explore more founder perspectives and case studies in the dedicated founders and entrepreneurship section, where the emphasis is on practical lessons, not just headline valuations.

Summary of the Future with Bootstrapping as a Competitive Advantage

As the global economy continues to adjust to new monetary regimes, geopolitical tensions and technological disruptions, the appeal of bootstrapped growth is unlikely to fade. In fact, for many sectors and regions, it is becoming a competitive advantage. Companies that learn to operate efficiently, prioritize profitable customer segments, leverage AI to augment lean teams and integrate sustainability into their core operations will be better equipped to withstand shocks, pivot when necessary and capitalize on opportunities that arise when less disciplined competitors falter.

For the business focused audience of dailybusinesss.com-from founders in San Francisco, London and Berlin to investors in Toronto, Singapore and Sydney, and policymakers in Brussels, Tokyo and Brasília-the message is clear: the narrative of entrepreneurial success is broadening. Hyper-growth and massive fundraising rounds will continue to exist, but they will no longer be the sole or even primary markers of excellence. Instead, experience, expertise, authoritativeness and trustworthiness, as demonstrated through consistent execution, prudent financial management and responsible governance, will define the next generation of enduring companies.

Readers who wish to deepen their understanding of how these themes intersect across macroeconomics, technology, labor markets and global trade can explore related curated editorial coverage in the economics, technology and trade and global business sections of dailybusinesss.com. At the present time and for the foreseeable future, the founders who prioritize bootstrapped growth are not stepping back from ambition; they are redefining what ambitious, sustainable and trustworthy entrepreneurship looks like in a complex, interconnected world.

Central Bank Strategies for Post-Inflation Stability

Last updated by Editorial team at dailybusinesss.com on Monday 13 July 2026
Article Image for Central Bank Strategies for Post-Inflation Stability

Central Bank Strategies for Post-Inflation Stability

A New Monetary Landscape After the Inflation Shock

Wow the global monetary landscape has been reshaped by the inflationary wave that followed the pandemic years, the energy and supply chain shocks linked to geopolitical tensions, and the rapid repricing of risk across financial markets. Central banks in the United States, Europe, Asia, and emerging markets have moved from an era of ultra-low interest rates and quantitative easing to a more complex regime focused on price stability, financial resilience, and credible communication. For the fast learning fresh content readers of dailybusinesss.com, whose interests span AI, finance, business, crypto, economics, employment, and markets, understanding how central banks are navigating the post-inflation environment is now a strategic necessity rather than an academic exercise.

The transition from high inflation to what policymakers hope will be a period of durable stability is not simply a matter of raising interest rates and waiting for prices to cool. It involves a careful recalibration of monetary tools, a reassessment of inflation targets, closer coordination with fiscal authorities, and an increasingly sophisticated approach to financial stability risks, including those emerging from digital assets and algorithmic trading. Institutions such as the Federal Reserve, the European Central Bank, the Bank of England, the Bank of Japan, and the People's Bank of China are all, in different ways, designing and implementing strategies that seek to anchor inflation expectations, protect employment, and avoid systemic crises in credit and asset markets.

For executives, investors, and founders tracking developments through resources like the business analysis on dailybusinesss.com and global updates on world and markets coverage, the key question is how these strategies will shape borrowing costs, risk premiums, asset valuations, and cross-border capital flows over the coming decade.

Re-Anchoring Inflation Expectations After the Surge

One of the central challenges facing monetary authorities in 2026 is the re-anchoring of inflation expectations after several years in which headline and core inflation in many advanced economies moved significantly above target. Research from institutions such as the Bank for International Settlements indicates that once expectations become unmoored, restoring credibility can require both tighter policy and clearer communication than would otherwise be needed, especially when supply-side factors such as energy shocks or geopolitical disruptions play a major role. Readers can explore BIS analysis on inflation dynamics to better understand how these expectations feed into wage bargaining and price-setting behavior.

The Federal Reserve and the European Central Bank have responded by combining relatively restrictive policy rates with forward guidance that emphasizes conditionality and data dependence. Rather than promising a rapid return to low interest rates, they have stressed their willingness to keep policy tight until inflation is firmly within target ranges and underlying measures of price growth, such as trimmed mean and median inflation, show sustained improvement. The Bank of England, facing unique post-Brexit frictions and domestic energy issues, has similarly underscored the importance of preventing a wage-price spiral, even as it remains attentive to the impact of higher rates on the United Kingdom's housing market and small business financing.

For business leaders and financial professionals who follow macroeconomic coverage on economics and finance at dailybusinesss.com, this renewed focus on expectations means that market narratives and central bank communication are now as important as the headline policy rate itself. Investors parsing statements from the Federal Open Market Committee or the ECB Governing Council understand that subtle shifts in language about "persistence," "broad-based pressures," or "symmetry" around targets can move bond yields, equity valuations, and currency pairs in ways that feed back into real economic conditions. Those who monitor Federal Reserve communications or review ECB press conferences on the European Central Bank website increasingly treat central bank rhetoric as a core input into strategy.

Calibrating Interest Rate Policy in a Higher-for-Longer World

The post-inflation environment has revived a question that many had stopped asking during the years of near-zero rates: what is the neutral interest rate that neither stimulates nor restrains the economy, and has it risen in a structurally meaningful way? Demographic shifts, productivity trends, and the global savings-investment balance all matter for this debate, and organizations such as the International Monetary Fund and the Organisation for Economic Co-operation and Development have devoted significant analytical resources to it. Business readers can review IMF discussions of r-star and neutral rates to understand how these concepts shape long-term projections for growth and inflation.

In 2026, many central banks have adopted a cautious stance that can best be described as "higher for longer, but not forever." Policy rates in the United States, the euro area, the United Kingdom, and Canada remain above the levels considered normal in the 2010s, but below the emergency peaks used to crush the initial inflation surge. This intermediate range is intended to keep real (inflation-adjusted) rates modestly positive, restraining demand without tipping economies into deep recessions. The Bank of Canada and the Reserve Bank of Australia have been particularly explicit in describing this balancing act, emphasizing that they will adjust as new data on productivity, labor force participation, and investment materialize.

For corporates and investors, the implication is that capital structures, valuation models, and risk management frameworks built around the assumption of permanently cheap money must be revisited. Readers of finance and investment coverage on dailybusinesss.com are already seeing a shift toward more conservative leverage ratios, a preference for longer-term fixed-rate financing where available, and greater scrutiny of projects whose returns depend heavily on low discount rates. Businesses operating in the United States, the United Kingdom, Germany, Canada, and Australia are recalibrating hurdle rates for new investments, while investors in Europe and Asia are reassessing the relative attractiveness of equities versus bonds in a world where safe yields are no longer negligible. Those seeking a deeper understanding of policy rate paths across countries often turn to resources such as the Bank of England monetary policy reports or the Reserve Bank of Australia statements to inform their global strategies.

Beyond Rates: The Evolution of Balance Sheet and Liquidity Tools

While interest rates remain the primary instrument for controlling inflation, the experience of the past decade has made it clear that central bank balance sheets and liquidity operations are now permanent features of the monetary architecture. The quantitative easing programs launched after the global financial crisis and expanded during the pandemic left the Federal Reserve, the ECB, the Bank of Japan, and others with vast holdings of government and corporate bonds. In the post-inflation phase, the challenge is to normalize these balance sheets without causing disorderly moves in bond markets or undermining financial stability.

The Federal Reserve's policy of quantitative tightening-allowing securities to roll off its balance sheet subject to monthly caps-has been mirrored, with local variations, by the Bank of England and the ECB, which have also experimented with outright sales. These operations must be sequenced carefully relative to rate decisions, as shrinking the balance sheet too quickly can tighten financial conditions more than intended, particularly in markets where banks and non-bank financial institutions rely heavily on central bank reserves for liquidity. The Bank of Japan, long an outlier with its yield curve control policy, has begun a cautious shift away from strict yield caps, recognizing that prolonged distortion of the government bond market can create vulnerabilities, especially as global yields rise.

For global investors and corporate treasurers who follow markets and news on dailybusinesss.com, the pace of balance sheet reduction matters for term premiums, credit spreads, and the functioning of repo and money markets. Liquidity stress episodes, such as the UK gilt market turmoil in 2022, have underscored how quickly leverage and duration mismatches in the non-bank sector can interact with central bank actions. Institutions like the Financial Stability Board and the Basel Committee on Banking Supervision have intensified their monitoring of these channels, and professionals can review FSB publications on non-bank financial intermediation to better appreciate the systemic implications.

Integrating Financial Stability into the Monetary Mandate

The inflation shock of the early 2020s coincided with a period of rapid asset price adjustments, raising the specter of financial instability at a time when central banks were already under pressure to tighten. The failures of certain regional banks in the United States and strains in European credit markets highlighted the risk that higher rates could expose vulnerabilities built up during the low-rate era. In response, central banks have increasingly integrated financial stability considerations into their policy frameworks, using macroprudential tools alongside interest rates to manage systemic risks.

Macroprudential measures such as countercyclical capital buffers, sectoral capital requirements, and limits on loan-to-value or debt-service ratios in mortgage markets are now more widely deployed in countries including the United Kingdom, Sweden, Norway, and South Korea. These tools allow authorities to lean against excessive credit growth or housing market froth without resorting to blunt changes in the policy rate that would affect the entire economy. The Bank of England's Financial Policy Committee and the Swedish Riksbank have been particularly active in this domain, and their experiences are closely watched by policymakers and investors worldwide. Those interested in the intersection of macroprudential policy and market dynamics often consult the Riksbank financial stability reports or the Bank of England's financial stability publications.

For the dailybusinesss.com audience engaged in global trade and world developments, this integration of financial stability into monetary strategy is critical. It affects the resilience of banking systems in Europe, North America, and Asia; the availability and cost of credit for businesses in Germany, France, Italy, and Spain; and the vulnerability of emerging markets in Africa, South America, and Southeast Asia to capital flow reversals. At the same time, central banks must navigate the moral hazard concern that extensive backstops could encourage excessive risk-taking, especially in segments such as high-yield credit, leveraged loans, and speculative real estate.

Digital Assets, Crypto, and the Central Bank Response

The post-inflation period has also coincided with a maturing yet still volatile crypto ecosystem, forcing central banks to refine their stance on digital assets, stablecoins, and central bank digital currencies (CBDCs). The boom-and-bust cycles in Bitcoin, Ethereum, and a range of altcoins, alongside high-profile failures of exchanges and lending platforms, have prompted regulators and central banks to prioritize consumer protection, market integrity, and systemic risk containment. While many crypto assets remain outside the traditional monetary policy toolkit, their growing links to conventional finance mean that central banks cannot ignore them.

The European Central Bank, the Bank of England, and the Monetary Authority of Singapore have all advanced regulatory frameworks for stablecoins and crypto service providers, emphasizing robust reserve management, transparency, and operational resilience. In the United States, coordination among the Federal Reserve, the Securities and Exchange Commission, and the Commodity Futures Trading Commission has sought to clarify the regulatory perimeter, although debates over jurisdiction and classification continue. For readers exploring crypto and digital finance coverage on dailybusinesss.com, the key takeaway is that central banks see crypto primarily through the lens of stability and transmission channels rather than as a core monetary instrument.

At the same time, central banks in China, the euro area, and several Nordic and Asian economies have accelerated work on CBDCs, experimenting with retail and wholesale models that could reshape payment systems and cross-border settlement. The People's Bank of China's digital yuan pilots and the European Central Bank's digital euro project are the most prominent examples, offering insights into how programmable money and tokenized deposits might interact with traditional bank intermediation. Professionals interested in these experiments can learn more about CBDC research at the Bank for International Settlements Innovation Hub, which hosts collaborative projects involving central banks from Europe, Asia, and North America.

Labor Markets, Employment, and the Dual Mandate Challenge

In many advanced economies, the inflation spike of the early 2020s coincided with tight labor markets, rising nominal wages, and significant sectoral mismatches driven by technological change, remote work, and demographic trends. Central banks with dual mandates, such as the Federal Reserve, have had to balance the goal of maximum employment with the imperative of price stability, recognizing that overly aggressive tightening could damage labor market outcomes, particularly for more vulnerable groups. At the same time, allowing inflation to remain elevated for too long would erode real wages and undermine living standards.

By 2026, the labor market landscape in countries such as the United States, the United Kingdom, Canada, and Australia remains relatively robust, though pockets of weakness have emerged in interest-rate-sensitive sectors like construction and real estate. The diffusion of AI and automation technologies, especially in services and white-collar functions, has introduced new uncertainties about the future of work, productivity, and wage dynamics. Central banks are increasingly incorporating labor market heterogeneity and technology-driven shifts into their models, recognizing that traditional indicators such as headline unemployment may not fully capture slack or structural change. Readers following employment and future-of-work coverage on dailybusinesss.com can see how these macro trends intersect with corporate strategies around reskilling, remote work, and talent allocation.

Institutions like the OECD and the World Bank provide extensive analysis on labor market adaptation, skills, and productivity, and their insights are being used by monetary authorities to refine forecasts and scenario planning. Business leaders and policymakers can explore OECD work on jobs and skills to understand how demographic and technological forces might influence equilibrium unemployment and wage growth in Europe, North America, and Asia. For central banks, a deeper understanding of these dynamics is essential to avoid misjudging the degree of slack in the economy and thereby miscalibrating policy in the post-inflation environment.

Sustainability, Climate Risk, and Green Monetary Frameworks

The drive toward sustainability and the growing materiality of climate-related financial risks have also begun to influence central bank strategies for post-inflation stability. While most central banks maintain that their primary mandate remains price stability, many now acknowledge that climate change and the transition to a low-carbon economy can affect inflation dynamics, credit risks, and financial stability. The Network for Greening the Financial System (NGFS), a coalition of central banks and supervisors, has played a leading role in developing climate scenarios and risk assessment methodologies, and interested readers can learn more about sustainable finance frameworks that inform these efforts.

In Europe, the ECB has integrated climate considerations into its collateral framework and asset purchase programs, tilting portfolios toward issuers with better climate performance and disclosure. The Bank of England and the Swiss National Bank have conducted climate stress tests of banks and insurers, examining how physical and transition risks could propagate through the financial system. For the dailybusinesss.com audience engaged with sustainable business and green investment themes, these developments underscore that climate risk is no longer a peripheral issue; it is increasingly embedded in the way central banks think about long-term stability.

From a business perspective, this integration has several implications. Companies in carbon-intensive sectors may face higher financing costs as central banks and regulators push for more transparent and climate-aligned portfolios. Conversely, firms in renewable energy, energy efficiency, and sustainable infrastructure may benefit from improved access to capital and supportive policy frameworks. International organizations such as the World Economic Forum and the United Nations Environment Programme Finance Initiative have highlighted the role of central banks in facilitating a smooth transition, and professionals can learn more about sustainable business practices to align corporate strategies with evolving monetary and regulatory environments.

Data, AI, and the Digital Transformation of Central Banking

The post-inflation era has accelerated the adoption of advanced analytics, machine learning, and AI within central banks themselves. Institutions such as the Federal Reserve, the ECB, and the Bank of Canada are deploying high-frequency data, natural language processing, and nowcasting models to track inflation, consumption, and labor market trends in near real time. This digital transformation is partly a response to the recognition that traditional models struggled to capture the unprecedented shocks of the early 2020s, and that more granular and adaptive tools are needed to guide policy in a volatile world.

For the technology-savvy audience of dailybusinesss.com, who follow AI and technology developments and tech sector coverage, the convergence between advanced analytics in the private sector and in central banking is particularly noteworthy. Central banks are experimenting with AI-driven scenario analysis, sentiment tracking of market communications, and network models of financial linkages, while simultaneously grappling with governance, transparency, and bias issues. Leading research institutions and think tanks, including the Brookings Institution and the Peterson Institute for International Economics, have begun to analyze the implications of AI-enhanced policymaking, and interested readers can explore analysis on AI in economic policy to understand how these tools may reshape the speed and precision of monetary responses.

At the same time, central banks remain cautious about over-reliance on opaque models, emphasizing the need for human judgment, robust validation, and clear communication. The challenge is to harness the power of AI and big data without sacrificing accountability or increasing the risk of model-driven policy errors. For businesses and investors, this evolution suggests that macroeconomic forecasting and risk management will increasingly operate in an environment where both public and private actors are using sophisticated, data-rich tools, raising the bar for competitive insight.

Implications for Global Business, Trade, and Investment

For companies, founders, and investors across the United States, Europe, Asia, and emerging markets, the central bank strategies described above are not abstract policy debates; they shape the concrete operating environment for capital allocation, pricing, and strategic planning. The shift toward a post-inflation stability regime implies that volatility in interest rates, exchange rates, and risk premiums may remain elevated relative to the pre-pandemic decade, even as headline inflation moderates. This requires more dynamic risk management, diversified funding sources, and closer monitoring of macro-financial linkages.

Readers of dailybusinesss.com who track trade and global value chains and investment opportunities across regions need to recognize that diverging monetary paths among the Federal Reserve, the ECB, the Bank of England, the Bank of Japan, and key emerging market central banks can create significant cross-border capital flows and currency swings. For example, if the United States maintains relatively higher real rates than the euro area or Japan, capital may flow toward dollar-denominated assets, affecting export competitiveness for European and Asian firms while tightening financial conditions in emerging markets with dollar-linked liabilities. Conversely, a synchronized easing cycle, if inflation remains contained, could support risk assets globally but might also reignite concerns about asset bubbles.

In this environment, businesses in Germany, France, Italy, Spain, the Netherlands, Switzerland, the United Kingdom, Canada, Australia, Singapore, South Korea, Japan, and beyond must integrate central bank scenarios into their strategic planning. This includes stress-testing balance sheets against interest rate and currency shocks, reassessing hedging strategies, and evaluating how changes in the cost of capital could alter the relative attractiveness of different markets and projects. Institutions such as the World Trade Organization and the World Bank provide valuable insights into how monetary policy interacts with trade, investment, and development, and professionals can review WTO analysis on trade and macroeconomic conditions to complement the detailed business-focused coverage available on dailybusinesss.com.

The Banking Choices Ahead: Credibility, Adaptability, and Trust

Looking more toward the remainder of the 2020s, central bank strategies for post-inflation stability will be judged above all on their ability to maintain credibility, adapt to new shocks, and sustain public trust. The inflation surge of the early 2020s exposed the limits of existing models and the challenges of balancing multiple objectives in the face of overlapping supply and demand shocks. In response, central banks have become more explicit about uncertainty, more open to revising their frameworks, and more engaged with stakeholders across business, finance, and civil society.

For the growing business community and the many readers of dailybusinesss.com, the key is to treat central bank policy not as a static backdrop but as an evolving, data-driven process that interacts continuously with corporate decisions, financial innovation, and geopolitical developments. By closely monitoring policy signals, understanding the tools and constraints facing institutions such as the Federal Reserve, the ECB, the Bank of England, the Bank of Japan, and major emerging market central banks, and integrating these insights into strategic planning, businesses and investors can navigate the post-inflation environment with greater resilience and foresight.

As the rest of the year unfolds, the interplay between monetary policy, financial stability, technological change, and sustainability will continue to shape the contours of global growth and opportunity. Central banks will remain at the center of this process, seeking to deliver price stability and robust financial systems in a world that is more interconnected, data-rich, and uncertain than ever before.

Crypto Adoption Trends in Traditional Finance Hubs

Last updated by Editorial team at dailybusinesss.com on Sunday 12 July 2026
Article Image for Crypto Adoption Trends in Traditional Finance Hubs

Crypto Adoption Trends in Traditional Finance Hubs

The Changing Face of Global Finance

So now the once-clear boundary between traditional finance and digital assets has blurred to the point of becoming a shared operating layer for global capital markets. In the world's leading financial centers, from New York and London to Singapore and Zurich, crypto adoption is no longer a speculative side story; it is a structural theme shaping regulation, infrastructure, employment, and strategic investment decisions. For the well informed readership of DailyBusinesss, which tracks developments across business, finance, markets, crypto, and technology, understanding how crypto is being integrated into traditional finance hubs has become essential for navigating the next decade of global economic transformation.

Traditional financial centers are not simply reacting to crypto innovation; they are increasingly shaping its direction. Regulatory regimes, institutional adoption patterns, and the emergence of compliant digital asset infrastructure are turning these hubs into laboratories for new forms of value transfer, investment products, and cross-border trade. As global bodies such as the Bank for International Settlements and International Monetary Fund refine their views on digital assets, and as leading banks and asset managers deploy capital and build platforms, crypto in 2026 is defined less by retail speculation and more by institutional integration, regulatory clarity, and strategic positioning.

Institutionalization of Crypto in Major Financial Centers

In the United States, the institutionalization of crypto has been driven by a combination of regulatory enforcement, clearer rulemaking, and intense market demand. New York, still one of the most influential financial hubs, has seen leading banks and broker-dealers launch tokenized versions of traditional instruments and develop custody solutions that meet the expectations of institutional investors. The evolution of the New York Department of Financial Services virtual currency framework has enabled a growing cohort of licensed entities to service large corporates and funds, while federal regulators refine their approaches to stablecoins, spot crypto exchange-traded products, and digital asset securities. Observers following developments through resources such as the U.S. Securities and Exchange Commission and Commodity Futures Trading Commission have noted a gradual shift from broad skepticism to more targeted oversight, with a focus on market integrity, consumer protection, and systemic risk.

London's role as a bridge between Europe, North America, and Asia has made its approach to crypto adoption particularly influential. The United Kingdom's efforts to position itself as a global hub for digital assets have included legislative efforts to bring crypto under the umbrella of financial services regulation, along with a push from HM Treasury and the Financial Conduct Authority to clarify rules for stablecoins and crypto-backed services. At the same time, leading UK-based institutions, including global banks, insurers, and asset managers, have been exploring tokenization of real-world assets and the integration of blockchain-based settlement into their operations. Readers who follow the evolution of global financial regulation through platforms like the Bank of England and Financial Stability Board can see how London's policy choices are influencing other jurisdictions.

In Europe's other major hubs, such as Frankfurt, Paris, Amsterdam, and Zurich, the Markets in Crypto-Assets (MiCA) framework has provided a unifying regulatory baseline that is catalyzing institutional adoption. Germany's large universal banks and specialized custodians have leveraged MiCA to build compliant crypto services for high-net-worth clients and institutional investors, while Switzerland, through FINMA and its long-standing crypto-friendly stance, has continued to attract digital asset foundations, tokenization platforms, and wealth managers. For a deeper understanding of how these regulatory frameworks are reshaping European capital markets, business leaders often turn to organizations such as the European Central Bank and European Banking Authority, which have increasingly focused on digital assets, tokenization, and central bank digital currency (CBDC) experiments.

The Regulatory Maturation of Crypto in 2026

By 2026, the narrative around crypto regulation has shifted from prohibition versus permission to calibration and integration. Traditional finance hubs have recognized that outright bans are neither practical nor conducive to innovation, while unregulated growth poses unacceptable risks to consumers and financial stability. This has led to a wave of regulatory maturation, with policymakers aiming to align digital assets with established financial principles such as transparency, risk management, and investor protection.

In North America, the United States and Canada have moved toward more harmonized approaches to custody, anti-money laundering controls, and disclosure requirements for digital asset service providers. Canadian regulators, long seen as more open to crypto-based investment products, have collaborated with banks, pension funds, and asset managers to establish frameworks for digital asset ETFs and tokenized fixed income instruments. Meanwhile, U.S. policymakers, influenced by extensive public consultations and market feedback, have refined their approach to stablecoins, treating systemically important issuers more like banks or money market funds. Decision makers monitoring these trends through sources such as the International Monetary Fund and Organisation for Economic Co-operation and Development have noted that North American regulatory practice is increasingly focused on integrating digital assets into the existing prudential and securities frameworks rather than designing entirely separate regimes.

In Asia, regulatory evolution has been particularly dynamic. Singapore, through the Monetary Authority of Singapore, has pursued a strategy that balances innovation with strict compliance expectations. The city-state has attracted leading global exchanges, tokenization ventures, and digital asset custodians, while simultaneously setting high standards for licensing, capital adequacy, and cyber resilience. Hong Kong, seeking to reassert itself as a premier financial hub, has reopened to regulated crypto trading and has introduced licensing regimes for retail-facing platforms, aiming to differentiate compliant operators from offshore entities that were involved in past market excesses. Market participants interested in Asia's digital asset frameworks often track developments via the Monetary Authority of Singapore and Hong Kong Monetary Authority, which provide insight into how leading Asian hubs are shaping institutional-grade crypto markets.

In the Middle East, Dubai and Abu Dhabi have emerged as important centers for regulated digital asset activity, with bespoke frameworks that aim to attract both infrastructure providers and institutional investors. Their approach, heavily focused on economic diversification and fintech innovation, has been closely watched by European and Asian policymakers who see the Gulf as a testbed for large-scale tokenization of real estate, trade finance, and commodities. As global investors compare regulatory environments and market depth across these hubs, platforms like World Bank and World Economic Forum offer useful context on how digital assets fit into broader development and competitiveness strategies.

Convergence of Crypto and Institutional Investment

For the audience of DailyBusinesss, which follows investment and markets trends closely, one of the most significant developments by 2026 has been the convergence of crypto with mainstream institutional portfolios. The narrative has shifted from whether institutions will participate to how they will manage exposure, risk, and infrastructure. Large asset managers, sovereign wealth funds, and pension schemes in the United States, United Kingdom, Canada, Australia, and parts of Europe have started to treat digital assets as one component of a broader alternative investment strategy, often alongside private equity, infrastructure, and real assets.

This convergence has been driven by several factors. The maturation of custody solutions, frequently built by or in partnership with major banks, has addressed long-standing concerns about safekeeping and operational risk. The growing availability of regulated exchange-traded products, structured notes, and tokenized funds has allowed institutions to gain exposure without having to manage private keys or navigate unregulated exchanges. At the same time, the development of robust derivatives markets for Bitcoin, Ether, and selected large-cap tokens has enabled more sophisticated hedging, arbitrage, and yield strategies, aligning digital assets with established risk management practices. Institutions that rely on research from platforms like J.P. Morgan and BlackRock have seen a steady increase in digital asset analysis, scenario planning, and macro correlations, signaling that crypto is being integrated into the standard toolkit of global asset allocation.

Tokenization of real-world assets has also become a major driver of institutional interest. In leading financial hubs, regulated platforms now enable the issuance and secondary trading of tokenized government bonds, corporate debt, funds, and, in some cases, real estate and infrastructure projects. This has created opportunities for fractional ownership, enhanced liquidity, and more efficient settlement, particularly in cross-border contexts. Institutions exploring these opportunities often look to resources such as BIS Innovation Hub and International Organization of Securities Commissions to understand best practices and supervisory expectations around tokenized markets and distributed ledger-based settlement.

Employment, Talent, and the Reconfiguration of Financial Careers

Crypto adoption in traditional finance hubs has had a profound impact on employment patterns, skill requirements, and career trajectories across the global financial industry. For readers engaged with employment and workforce trends, it has become clear that digital assets are no longer a niche specialization but a cross-cutting competency that affects front-office, middle-office, and back-office roles alike. Banks, asset managers, exchanges, and consultancies in major hubs are competing for professionals who can bridge the gap between legacy systems and blockchain-based infrastructure, combining technical literacy with regulatory, risk, and product expertise.

This shift has led to a surge in demand for engineers with experience in blockchain protocols, smart contracts, and cybersecurity, but it has also transformed the expectations placed on legal, compliance, and risk professionals. Lawyers and compliance officers in New York, London, Frankfurt, Singapore, and Hong Kong are now expected to interpret evolving crypto regulations, design governance frameworks for tokenized products, and engage with regulators on novel issues ranging from decentralized finance (DeFi) to on-chain identity. Risk managers must integrate digital asset exposures into existing models, stress-testing frameworks, and capital planning processes, ensuring consistency with prudential requirements and investor expectations. Those monitoring global talent trends through organizations like the World Economic Forum and International Labour Organization can see how digital asset skills are increasingly listed among core competencies for the future of financial work.

Education and professional development have adapted accordingly. Leading universities and business schools in the United States, United Kingdom, Germany, Singapore, and Australia have launched specialized programs on digital assets, blockchain strategy, and tokenized finance, often developed in partnership with major financial institutions. Executive education providers and professional associations have introduced certifications on digital asset compliance, crypto valuation, and blockchain project management, signaling that the industry views these capabilities as enduring rather than cyclical. For readers of DailyBusinesss considering their own career trajectories, this convergence suggests that fluency in both traditional finance and digital asset concepts will be a differentiator across roles and regions.

Founders, Startups, and the New Crypto-Fintech Hybrid

The entrepreneurial landscape in traditional finance hubs has also been reshaped by crypto adoption, creating a new generation of founders building at the intersection of digital assets, fintech, and regulated financial services. In cities such as New York, London, Berlin, Paris, Toronto, Singapore, and Sydney, startups are no longer positioning themselves purely as "crypto companies"; instead, they present themselves as infrastructure providers, compliance technology platforms, tokenization specialists, or digital asset risk managers serving banks, asset managers, and corporations. Readers who follow founders and startup ecosystems have seen how this new wave of ventures often includes alumni from major institutions who bring deep regulatory and product expertise to bear on digital asset challenges.

These startups are partnering with traditional institutions rather than trying to displace them outright. They are building on- and off-ramps that meet strict know-your-customer and anti-money laundering requirements, data analytics tools for on-chain risk monitoring, and platforms that allow corporates to issue and manage tokenized instruments in compliance with securities laws. Many of these ventures are backed by large venture capital funds and corporate venture arms that see digital assets as a core pillar of the future financial infrastructure. Platforms such as CB Insights and Crunchbase have documented the steady flow of capital into these hybrid crypto-fintech ventures, particularly in hubs where regulatory clarity and market demand coincide.

For DailyBusinesss, which covers both tech and business innovation, this founder activity is a critical lens through which to view the evolution of crypto adoption. It illustrates that the most significant opportunities in 2026 are not necessarily in speculative trading, but in building the infrastructure, governance, and user experiences that will allow digital assets to integrate seamlessly with existing financial systems, corporate treasuries, and trade flows.

The Role of Stablecoins, CBDCs, and Cross-Border Payments

One of the most transformative developments across traditional finance hubs has been the rise of regulated stablecoins and the acceleration of central bank digital currency experiments. Stablecoins, particularly those fully backed by high-quality liquid assets and subject to bank-like regulation, have become a critical component of global liquidity management and cross-border settlement. In the United States and Europe, banks and payment providers increasingly use regulated stablecoins as an intermediate settlement asset for wholesale transfers, while corporates in trade-intensive sectors employ them to reduce friction and delays in cross-border payments. Detailed analysis from institutions such as the Bank for International Settlements and SWIFT has highlighted how these instruments can complement, rather than replace, existing payment rails.

CBDC pilots and limited-scale deployments are also reshaping expectations. In China, the digital yuan has continued its gradual rollout, integrating with domestic payment ecosystems and cross-border trials with partner countries. In Europe, the digital euro project has moved from exploratory phases toward more concrete design and policy decisions, while in the United Kingdom, the prospect of a digital pound remains under active consideration. Smaller economies, including several in Asia, the Nordics, and the Caribbean, have advanced further with retail and wholesale CBDC implementations, providing valuable lessons on privacy, interoperability, and financial inclusion. Business leaders monitoring these developments through sources such as the European Central Bank and Bank of England increasingly view CBDCs and stablecoins as part of a broader modernization of payment systems rather than isolated experiments.

For globally active corporations and financial institutions, especially those engaged in trade, travel, and cross-border services, the combination of stablecoins and CBDCs offers the prospect of more efficient working capital management, reduced foreign exchange costs, and improved transparency in cross-border flows. Readers of DailyBusinesss who operate in export-oriented sectors or manage international supply chains are already encountering pilot programs and bank-led initiatives that leverage tokenized money for trade finance, invoice factoring, and just-in-time liquidity provisioning.

Sustainability, Governance, and Long-Term Trust

As crypto has moved into the core of traditional finance hubs, sustainability and governance have become central to its long-term legitimacy. The environmental impact of proof-of-work mining, once a dominant concern, has been partially mitigated by the transition of major networks to proof-of-stake and by the growing use of renewable energy in remaining mining operations. Nonetheless, institutional investors, particularly in Europe, Canada, and the Nordics, now subject digital asset exposures to the same environmental, social, and governance (ESG) scrutiny applied to other asset classes. Analysts and sustainability officers rely on resources such as the UN Principles for Responsible Investment and Climate Bonds Initiative to evaluate how digital asset projects align with broader decarbonization and governance objectives.

For DailyBusinesss, which tracks sustainable business practices and long-term value creation, this shift underscores that crypto's future in traditional finance hubs depends on more than technological innovation or speculative returns. It requires robust governance structures for blockchains and tokenized platforms, transparent risk disclosures, and credible commitments to cybersecurity and operational resilience. Incidents of exchange failures, protocol exploits, or governance breakdowns are now evaluated through the lens of systemic risk and fiduciary duty, prompting regulators and industry bodies to push for higher standards of auditability, incident reporting, and consumer redress.

This focus on trust extends into questions of data privacy, on-chain identity, and the balance between transparency and confidentiality. Financial institutions in major hubs must navigate how to leverage the programmability and traceability of blockchain systems while complying with data protection regimes such as the EU General Data Protection Regulation and comparable frameworks in other regions. As they do so, they increasingly collaborate with policymakers, technologists, and civil society organizations to design architectures that protect individual rights while enabling effective supervision and law enforcement. Business leaders seeking to understand these trade-offs often consult organizations like the OECD and World Bank, which provide guidance on digital governance and data policy.

Strategic Implications for Global Business Leaders

For the global, multi-sector audience of DailyBusinesss, the integration of crypto into traditional finance hubs carries strategic implications that extend well beyond the financial sector. Corporates in manufacturing, technology, travel, logistics, and consumer services must decide whether and how to accept digital assets as payment, hold them on balance sheet, or use tokenized instruments for financing and supply chain management. Multinational enterprises operating across North America, Europe, and Asia must reconcile differing regulatory regimes, tax treatments, and banking relationships, often relying on specialized advisers and in-house digital asset teams to coordinate policy and execution.

At the same time, investors and executives must consider the macroeconomic implications of widespread crypto adoption. The interaction between tokenized assets, stablecoins, and traditional monetary policy, the potential for capital flow volatility, and the impact on emerging markets that rely on remittances and cross-border capital are all areas of active debate. Institutions such as the International Monetary Fund and World Economic Forum have emphasized that digital assets can both enhance and complicate financial stability, depending on how they are integrated into the broader system. For decision makers, this means that crypto-related strategies cannot be siloed; they must be integrated into risk management, treasury, compliance, and long-term strategic planning.

For readers of DailyBusinesss who follow world developments and news, the key takeaway in 2026 is that crypto adoption in traditional finance hubs is no longer a question of if, but of how and at what pace. The leading centers in the United States, United Kingdom, Europe, and Asia are setting the tone through regulatory frameworks, institutional practices, and infrastructure investments that will shape the trajectory of digital assets for years to come. Businesses, investors, founders, and professionals who understand these dynamics and position themselves accordingly will be better equipped to navigate an increasingly tokenized global economy.

How to Consider Crypto as an Embedded Layer of Global Finance?

As crypto continues to embed itself into the fabric of traditional finance hubs, the conversation is shifting from digital assets as a standalone category to crypto as an enabling layer beneath a wide range of financial and commercial activities. Tokenization, programmable money, and blockchain-based settlement are becoming part of the underlying infrastructure that supports capital markets, trade, and everyday transactions, even when end users are scarcely aware of the technology involved. For DailyBusinesss and its finance watching readership, the challenge and opportunity lie in discerning which developments represent lasting structural change and which are transient cycles.

In the coming years, the interplay between regulation, institutional adoption, technological innovation, and macroeconomic conditions will determine how deeply and broadly crypto is integrated into global finance. Traditional hubs will remain at the center of this evolution, not only because of their concentration of capital and expertise, but also because they are where regulatory legitimacy, market infrastructure, and global connectivity intersect. By following developments across finance, crypto, economics, and technology, the audience of DailyBusinesss can track how crypto adoption in these hubs continues to redefine what it means to operate, invest, and compete in the global economy of 2026 and beyond.

Asia's Booming Middle Class Reshapes Consumption

Last updated by Editorial team at dailybusinesss.com on Saturday 11 July 2026
Article Image for Asia's Booming Middle Class Reshapes Consumption

Asia's Booming Middle Class Reshapes Global Consumption

A New Center of Gravity for Global Demand

The world's economic center of gravity has shifted decisively toward Asia, and nowhere is this more visible than in the rise of a vast, confident, and increasingly affluent middle class stretching from China and India to Indonesia, Vietnam, Thailand, Malaysia, South Korea, and beyond. For engaged readers of DailyBusinesss, whose interests normally go around things like AI, finance, business, crypto, economics, employment, founders, investment, markets, sustainability, and global trade, this transformation is not an abstract macroeconomic trend; it is a daily reality that is reshaping product strategies, capital flows, talent markets, and competitive dynamics across North America, Europe, and the rest of the world.

Analysts at organizations such as the World Bank and OECD have, over the past decade, documented the rapid expansion of Asia's middle-income population, with projections that by the mid-2020s more than half of the world's middle class would reside in Asia. Readers can explore how this has altered global demand patterns by reviewing recent global consumption data and projections from the World Bank and the OECD. For business leaders in the United States, United Kingdom, Germany, Canada, Australia, and across Europe and Asia, the practical implication is clear: the incremental consumer of the next decade is far more likely to live in Bangalore, Chengdu, Jakarta, or Manila than in Boston, Berlin, or Birmingham.

This article examines how Asia's booming middle class is reshaping consumption patterns in 2026, the implications for global companies and investors, and the strategic considerations that executives and founders, particularly those following the insights of DailyBusinesss' business coverage, must now place at the center of their planning.

Defining Asia's Middle Class in 2026

The term "middle class" has always been contested, but in Asia it has acquired a distinctive meaning that blends rising incomes with aspirational lifestyles, digital connectivity, and urbanization. Institutions such as the Asian Development Bank and McKinsey Global Institute have traced the evolution of this cohort, generally defining middle-class status in Asia using daily consumption thresholds adjusted for purchasing power parity and local costs of living. Interested readers can review detailed regional breakdowns from the Asian Development Bank and long-term projections from McKinsey Global Institute.

In 2026, Asia's middle class is no longer a fragile emergent segment; it is an entrenched economic force. In China's tier-two and tier-three cities, in India's rapidly growing urban centers such as Pune, Ahmedabad, and Hyderabad, and in Southeast Asia's rising metropolises like Ho Chi Minh City, Bangkok, and Kuala Lumpur, households are moving decisively beyond subsistence consumption toward discretionary spending on education, healthcare, housing upgrades, travel, digital services, and financial products. This evolution is tightly connected to the structural themes that DailyBusinesss regularly covers in its economics and markets sections, namely productivity growth, urbanization, and the diffusion of technology.

Crucially, Asia's middle class is also younger, more digitally native, and more open to experimentation than its counterparts in many Western economies. The median age in countries such as India, Indonesia, and the Philippines remains well below that of most European nations, and this demographic advantage is amplifying the impact of rising incomes on consumption patterns, especially in technology-enabled sectors.

Digital-First Consumption and the AI-Driven Platform Economy

One of the most striking characteristics of Asia's middle class in 2026 is its digital-first behavior. Smartphone penetration across major Asian markets has surged over the past decade, and mobile broadband networks have become both cheaper and more reliable. This has enabled an ecosystem of super-apps, e-commerce marketplaces, fintech platforms, and AI-enabled services that are now indispensable to middle-class daily life from Singapore to Seoul and from Shanghai to Surat.

Companies such as Alibaba, Tencent, JD.com, Meituan, Grab, Gojek, Shopee, Paytm, and Kakao have built integrated digital environments that combine payments, shopping, mobility, entertainment, and increasingly, AI-driven personal and financial services. The widespread integration of generative AI, recommendation engines, and predictive analytics into these platforms has changed how middle-class consumers discover products, evaluate brands, and make purchase decisions. Readers who follow DailyBusinesss' AI coverage will recognize that Asia's consumer platforms have become some of the most advanced applied AI laboratories in the world, rivaling or surpassing many Western peers.

Research from organizations like the International Telecommunication Union and UNCTAD shows that Asia now accounts for a dominant share of global e-commerce transactions, driven largely by middle-class consumers who are comfortable with digital wallets, QR-code payments, and embedded credit solutions. In markets such as China, South Korea, and Singapore, cash has become increasingly marginal in urban middle-class transactions, and digital identity systems and real-time payments infrastructure have allowed fintech innovators to scale at unprecedented speed.

For global brands from Europe, North America, and Australia seeking to serve Asia's middle class, this digital-first context means that traditional distribution models and brand-building strategies must be fundamentally rethought. Presence on major super-apps, partnerships with local influencers and content creators, and the deployment of AI-driven personalization are no longer optional; they are entry tickets to relevance in markets where consumer attention is both fragmented and intensely contested.

Financial Deepening: Savings, Investment, and Crypto Adoption

Rising incomes have not only fueled consumption; they have also expanded Asia's pool of household savings and investable assets. Middle-class households in China, India, South Korea, and Southeast Asia are increasingly sophisticated financial actors, seeking yield, diversification, and security in a volatile global environment marked by inflation concerns, geopolitical tensions, and fluctuating interest rates.

Traditional financial institutions such as DBS, OCBC, HSBC, ICBC, HDFC Bank, and MUFG are competing with digital-first challengers and neobanks that offer low-fee, mobile-optimized access to savings accounts, investment products, and insurance. Many of these offerings are integrated into broader super-app ecosystems, blurring the line between consumption and investment. For those tracking financial innovation, DailyBusinesss' finance and investment sections provide ongoing analysis of how these trends are reconfiguring capital markets and retail investor behavior.

Asia has also become a critical theater for the evolution of digital assets and cryptocurrencies. While regulatory approaches vary widely-from the relatively open stance of Singapore to more restrictive frameworks in China-middle-class investors across the region have demonstrated strong interest in crypto as both a speculative asset and, in some markets, as a hedge against currency volatility or capital controls. To understand the broader implications of this phenomenon, readers can explore DailyBusinesss' crypto coverage alongside regulatory perspectives from institutions such as the Monetary Authority of Singapore and the Bank for International Settlements.

At the same time, Asia's middle class is driving demand for more sophisticated investment products, including mutual funds, ETFs, pension schemes, and wealth-management services that are tailored to local tax regimes and cultural preferences. Global asset managers from the United States, United Kingdom, Switzerland, and France see the region as the central growth market for the coming decade, and many have formed joint ventures with local players to navigate regulatory, linguistic, and distribution complexities. The resulting financial deepening is reinforcing Asia's role as both a consumer market and a capital provider, with implications for global bond and equity flows that are closely followed by international investors.

Urbanization, Real Estate, and Infrastructure Demand

The expansion of Asia's middle class is tightly linked to rapid urbanization, which continues to reshape skylines and infrastructure networks from Beijing to Bangalore and from Jakarta to Tokyo. Middle-class households are migrating to cities not only in search of employment, but also in pursuit of better schools, healthcare, transportation, and quality of life. This has created sustained demand for residential real estate, commercial property, and urban infrastructure, even as policymakers grapple with affordability, congestion, and environmental stress.

In China, despite policy efforts to cool speculative bubbles, urban middle-class households continue to see property ownership as a core component of financial security, although the real estate sector's recent adjustments have prompted greater caution and diversification into financial assets. In India, affordable housing schemes and public infrastructure initiatives such as metro systems and regional connectivity corridors are catalyzing new urban clusters and commuter belts. Southeast Asian economies, including Vietnam, Indonesia, and the Philippines, are experiencing similar dynamics as rising incomes and demographic growth intersect with foreign investment and industrial relocation.

Organizations such as UN-Habitat and the World Economic Forum have highlighted the challenges and opportunities associated with this urban expansion, particularly in relation to sustainability, resilience, and social inclusion. For business leaders and investors who follow DailyBusinesss' world and trade coverage, the key takeaway is that infrastructure and real estate in Asia are not solely domestic stories; they are increasingly linked to global supply chains, cross-border financing, and international standards in areas such as green building and smart-city technologies.

Changing Lifestyles: Health, Education, and Leisure

As incomes rise, Asia's middle class is allocating a greater share of spending to health, education, and leisure, transforming these sectors into major growth industries. Middle-class parents in China, India, South Korea, Japan, and Southeast Asia are investing heavily in education, from early childhood programs to after-school tutoring, test preparation, international schooling, and online learning platforms. Organizations such as the OECD and UNESCO have documented the region's intense focus on educational attainment, which is seen as the primary route to upward mobility in increasingly competitive labor markets.

Health and wellness have also become central to middle-class aspirations. Demand for high-quality healthcare services, private insurance, preventive medicine, and fitness has surged, particularly in urban centers. International hospital groups, pharmaceutical companies, and health-tech startups are expanding their presence, while local players innovate with telemedicine, AI-assisted diagnostics, and digital health records. Those who wish to understand the broader public-health implications can consult resources from the World Health Organization and regional health ministries, which highlight both the progress and the persistent gaps in access and quality.

Leisure and travel represent another area where Asia's middle class is reshaping global consumption. Outbound tourism from China, India, Southeast Asia, and South Korea has become a critical driver of visitor numbers and spending in destinations across Europe, North America, Australia, and within Asia itself. For readers interested in how this influences airlines, hospitality, and retail, DailyBusinesss' travel section offers ongoing insight into evolving patterns of tourism, visa policies, and infrastructure investment. Destinations from France and Italy to Thailand and Japan are tailoring offerings, language services, and payment options to meet the expectations of Asian middle-class travelers, who are increasingly seeking personalized, experience-rich itineraries rather than standardized group tours.

Employment, Skills, and the Future of Work

The rise of Asia's middle class is not only a consumption story; it is fundamentally a story about employment, skills, and the future of work. Middle-class status in Asia is closely tied to participation in formal labor markets, particularly in services, manufacturing, and the digital economy. At the same time, automation, AI, and global competition are reshaping job profiles and wage dynamics, creating both opportunities and anxieties for workers in China, India, South Korea, Japan, and Southeast Asia.

International organizations such as the International Labour Organization and regional think tanks have emphasized that the next wave of middle-class growth will depend on the region's ability to upgrade skills, foster innovation, and manage transitions in sectors such as automotive, electronics, textiles, and business-process outsourcing. For readers of DailyBusinesss' employment coverage, a key theme is the increasing premium on digital literacy, data analytics, design thinking, and cross-cultural communication, particularly as multinational companies expand their Asian operations and as Asian firms internationalize.

Remote work and hybrid models, accelerated by the pandemic years earlier in the decade, have created new opportunities for Asia's middle-class professionals to participate in global labor markets without relocating, particularly in software development, design, marketing, and professional services. However, they have also intensified competition, as employers in the United States, United Kingdom, Canada, Germany, and Australia tap into talent pools across India, the Philippines, Vietnam, and beyond. The result is a more integrated but also more demanding global labor market, where continuous learning and adaptability are indispensable.

Sustainability, Climate, and Conscious Consumption

As Asia's middle class expands, so does its environmental footprint, raising critical questions about sustainability, climate resilience, and responsible consumption. The region's rising energy demand, growing vehicle ownership, and increased material consumption are placing pressure on global efforts to meet climate targets, even as many Asian governments and companies commit to net-zero timelines and invest heavily in renewable energy, electric mobility, and green infrastructure.

At the same time, there is a discernible shift among segments of the middle class toward more conscious consumption, particularly in markets such as Japan, South Korea, Singapore, and increasingly in China and India. Younger middle-class consumers are showing a preference for brands that demonstrate environmental and social responsibility, transparency in supply chains, and credible sustainability commitments. To understand the policy and scientific backdrop, readers can refer to the Intergovernmental Panel on Climate Change and the UN Environment Programme, which provide detailed assessments of regional climate risks and mitigation pathways.

For companies and investors following DailyBusinesss' sustainable business coverage, this presents both a challenge and an opportunity. On one hand, there is the risk that unchecked consumption growth could lock in high-carbon infrastructure and resource-intensive lifestyles; on the other, there is enormous potential for scaling clean technologies, circular-economy models, and sustainable finance instruments across a vast and dynamic market. Asian middle-class consumers are increasingly receptive to electric vehicles, energy-efficient appliances, plant-based foods, and eco-tourism, provided that these options are accessible, affordable, and aligned with local cultural preferences.

Implications for Global Business, Founders, and Investors

For the global business community, the rise of Asia's middle class in 2026 demands a strategic reorientation that goes far beyond simple market entry or export strategies. Executives in the United States, United Kingdom, Germany, France, Canada, Australia, and across Europe and North America must assume that the marginal consumer, the incremental growth opportunity, and often the next disruptive competitor will emerge from Asia's urban middle-class hubs.

Founders and entrepreneurs across the region are building globally competitive companies in e-commerce, fintech, enterprise software, health-tech, climate-tech, and consumer brands, many of which are now attracting capital from leading venture and growth-equity firms in Silicon Valley, London, Berlin, Singapore, and Hong Kong. Readers interested in the founder perspective can follow DailyBusinesss' dedicated founders section, which highlights how local entrepreneurs are tailoring products to the specific needs, languages, and cultural nuances of middle-class consumers in markets as diverse as India, Indonesia, Vietnam, and South Korea.

For institutional investors and asset managers, Asia's middle class represents both a structural growth story and a source of diversification. Equity and debt markets across the region are increasingly deep and liquid, with major indices and exchanges in Shanghai, Shenzhen, Hong Kong, Tokyo, Seoul, Singapore, Mumbai, and Jakarta attracting global capital. Organizations such as MSCI and FTSE Russell have progressively increased Asia's weight in global indices, reflecting the region's economic clout and the growing importance of its listed companies. Investors who track these developments through DailyBusinesss' markets coverage will recognize that understanding the consumption behavior, regulatory environments, and political dynamics of Asian economies is now a prerequisite for global portfolio construction.

Strategic Considerations for the Next Decade

Looking beyond 2026, the trajectory of Asia's middle class will be shaped by several interlocking factors: the pace of economic growth in China and India, the ability of Southeast Asian economies to move up the value chain, the region's success in managing demographic transitions in aging societies such as Japan and South Korea, and the geopolitical environment that frames trade, technology transfer, and capital flows between Asia, Europe, and North America.

Executives and policymakers who wish to position themselves effectively for this future must consider several strategic imperatives. These include building genuinely local capabilities in key Asian markets rather than relying solely on export models; investing in AI, data analytics, and digital infrastructure to understand and serve middle-class consumers at scale; integrating sustainability into core business strategies rather than treating it as an adjunct; and developing talent strategies that recognize Asia as both a source and a destination for high-skilled labor.

Resources from the IMF, World Bank, and World Trade Organization provide valuable macroeconomic and trade context, while DailyBusinesss' technology coverage and broader news reporting track the rapid evolution of AI, digital platforms, and regulatory frameworks that will shape the region's business environment. By integrating these perspectives, decision-makers can move beyond reactive approaches and develop proactive strategies that align products, capital allocation, and organizational capabilities with the realities of Asia's emerging middle-class century.

Conclusion: From Regional Trend to Global Finance Anchor

Asia's booming middle class is no longer an emerging story at the periphery of global business; it is the central anchor of future consumption, innovation, and growth. From AI-enabled digital platforms and sophisticated financial services to sustainable infrastructure, education, healthcare, and travel, the preferences and behaviors of hundreds of millions of Asian middle-class households are now shaping investment decisions and strategic priorities in boardrooms from New York and London to Frankfurt, Singapore, and Sydney.

For the super audience of DailyBusinesss, this transformation touches every area of interest: AI and technology, finance and investment, crypto and digital assets, employment and skills, founders and entrepreneurship, sustainability, trade, and global macroeconomics. The task for business leaders, investors, and policymakers is to recognize that Asia's middle class is not a monolithic bloc but a diverse, evolving mosaic of markets, cultures, and aspirations, each requiring nuanced understanding and tailored engagement.

Those who invest the time to understand these nuances, build local partnerships, leverage data and AI responsibly, and align their strategies with the values and expectations of Asia's new middle-class majority will be best positioned to thrive in the coming decade. Those who cling to outdated assumptions about where growth will come from and how consumers behave risk being left behind as the world's demand engine accelerates decisively eastward.

Canada Attracts Tech Talent with New Visa Pathways

Last updated by Editorial team at dailybusinesss.com on Friday 10 July 2026
Article Image for Canada Attracts Tech Talent with New Visa Pathways

Canada's New Tech Visa Pathways: How a Talent Strategy Became a Global Competitive Advantage

A New Phase in Canada's Technology Strategy

Canada has moved from talking about digital transformation to operationalizing it at scale, and nowhere is this more evident than in its evolving approach to high-skilled immigration. The country's new tech visa pathways, launched and refined between 2023 and 2026, have shifted from being a tactical response to labour shortages to becoming a core pillar of national competitiveness, innovation policy and economic resilience. For the fast growing global business community that follows news and developments through DailyBusinesss.com, these programs are no longer a niche immigration instrument; they are a strategic lens through which to understand how advanced economies are competing for talent, capital and intellectual property in artificial intelligence, fintech, quantum, clean technology and cybersecurity.

In an environment where the United States, United Kingdom, Germany, Singapore and Australia are all racing to attract the same limited pool of world-class engineers, data scientists and founders, Canada's tech visas represent an experiment in combining openness with rigorous standards of experience, expertise, authoritativeness and trustworthiness. As leading organizations reassess global location strategies, the Canadian model offers a case study in how immigration, innovation and industrial policy can be integrated rather than treated as separate files.

How Canada's Tech Visa Landscape Evolved

The modern phase of Canada's tech talent strategy can be traced to the Global Skills Strategy and the Global Talent Stream, which provided fast-track work permits for specialized roles and were promoted by Immigration, Refugees and Citizenship Canada. However, the period from 2023 onward saw a marked acceleration and rebranding of this agenda, with the federal government introducing targeted programs for highly skilled technology workers, especially those in artificial intelligence, software engineering and digital infrastructure, and positioning them explicitly as tools to win the global competition for talent.

These initiatives coincided with an unprecedented wave of investment into the Canadian innovation ecosystem, including new AI research hubs in Toronto, Montréal, Vancouver and Edmonton, as well as expanded activities by global firms such as Google, Microsoft, Amazon Web Services and Meta. Learn more about how Canada positioned itself as an AI leader through institutions like the Vector Institute and Mila. At the same time, Canadian policymakers responded to shifts in other jurisdictions, including tightening immigration in parts of Europe and uncertainty around long-term visa policies in the United States, by marketing Canada's relative stability and predictable pathways to permanent residence.

For readers of DailyBusinesss.com, which regularly analyzes developments across AI and emerging technologies and broader business and policy trends, Canada's evolving visa architecture illustrates how regulatory agility can be deployed to align workforce supply with the needs of fast-moving industries, while still preserving standards that maintain public trust.

Core Components of the New Tech Visa Pathways

The new tech visa pathways in Canada are not a single program but a portfolio of mechanisms designed to cover different stages of the talent lifecycle, from early-career specialists to seasoned founders. While specific naming conventions and streams have evolved, several common pillars can be identified.

The first pillar is speed. Building on the earlier Global Talent Stream, Canada has institutionalized processing timelines that, in many cases, aim for work permit approvals within weeks rather than months, a decisive factor for companies competing in tight product cycles and venture-funded growth windows. This is particularly relevant to scale-ups in fintech, AI and clean technology that operate across markets such as the United States, United Kingdom, Germany and Singapore, and need to deploy teams quickly to meet investor milestones. Businesses can explore how these timelines translate into practical advantages by reviewing guidance from Government of Canada's immigration portal.

The second pillar is skills targeting. Rather than broad, undifferentiated high-skilled migration, Canada's tech visas emphasize occupations and capabilities that are demonstrably scarce and economically strategic. This includes advanced AI research, machine learning engineering, data infrastructure, cybersecurity, quantum computing and specialized software development. Industry-validated wage thresholds and role definitions are used to ensure that incoming talent complements, rather than displaces, domestic workers, an approach that resonates with broader labour-market debates covered in DailyBusinesss.com's employment analysis.

The third pillar is a clear pathway to permanence. Unlike many temporary tech visa regimes in other jurisdictions, Canada's model often integrates mechanisms for permanent residence, enabling long-term planning for both individuals and employers. For global professionals deciding between Toronto, London, Berlin, Singapore or Silicon Valley, the prospect of a stable, family-friendly destination with access to high-quality public services, robust financial systems and a rules-based regulatory environment is increasingly central to decision-making. Investors tracking these trends can connect them to broader capital flows and valuation dynamics, which DailyBusinesss.com examines in its investment coverage.

Strategic Benefits for Canada's Innovation Economy

From a macroeconomic perspective, Canada's tech visa strategy serves several overlapping objectives that go well beyond filling short-term vacancies. It is a deliberate attempt to deepen the country's innovation capacity, diversify its growth model and enhance resilience against sector-specific shocks.

One of the most important effects has been the strengthening of Canada's AI and data economy. By attracting leading AI researchers and engineers at a time when global demand far outstrips supply, Canada has reinforced the critical mass of talent around its research institutes, universities and private-sector labs. This has supported a growing ecosystem of startups and scale-ups working on generative AI, applied machine learning in healthcare, financial services, climate modelling and industrial automation. Readers can learn more about how AI is reshaping industries through resources from the OECD AI Observatory and the World Economic Forum's Future of Jobs reports.

In finance and fintech, Canada's tech visas have underpinned the growth of digital banks, blockchain ventures and payment innovators that serve both domestic and cross-border markets, including the United States, United Kingdom and European Union. The ability to recruit globally for specialized roles in cryptography, distributed systems and regulatory technology has been critical, particularly as regulators such as the Bank of Canada, Office of the Superintendent of Financial Institutions and international bodies like the Bank for International Settlements tighten oversight of digital assets and systemic risk. Readers interested in the intersection of crypto, regulation and talent can explore DailyBusinesss.com's dedicated crypto and finance sections for ongoing analysis.

At the level of regional development, the new visa pathways have also supported the rise of second-tier tech hubs in cities such as Waterloo, Calgary, Ottawa and Halifax, complementing the established clusters in Toronto, Montréal and Vancouver. These ecosystems benefit from the arrival of experienced professionals who bring not only technical skills but also global networks, knowledge of international markets and familiarity with scaling companies across jurisdictions such as Europe, Asia and North America. This diffusion of expertise aligns with Canada's broader economic strategy to reduce overreliance on a small number of metropolitan areas and sectors.

Global Competition for Tech Talent

Canada's repositioning as a premier destination for technology professionals must be understood within a broader global context in which advanced economies are competing fiercely for the same human capital. The United States retains undeniable advantages in terms of market size, venture capital depth and the presence of global technology giants, but ongoing uncertainty around long-term visa categories and permanent residence pathways has created openings for competitors. The United Kingdom, especially after Brexit, has introduced its own high-potential individual and scale-up visas, while Germany, France, Netherlands and Spain have launched digital nomad and skilled worker programs to attract remote and on-site talent.

In Asia, Singapore, Japan, South Korea and Thailand have each introduced targeted visas for tech and startup professionals, often combined with tax incentives and streamlined corporate registration. The United Arab Emirates has aggressively marketed its own golden visas and free-zone ecosystems, while Australia and New Zealand have refined their skilled migration frameworks. Comparative assessments from organizations such as the OECD and World Bank highlight how these policies intersect with broader economic competitiveness indicators, including productivity, innovation output and human capital development.

Within this crowded field, Canada differentiates itself through a combination of predictable rule-of-law institutions, relatively depoliticized immigration debates, high quality of life and a reputation for multicultural inclusion, factors that resonate with professionals from regions as diverse as India, China, Brazil, South Africa, Nigeria, Malaysia and Eastern Europe. For corporate decision-makers evaluating where to base R&D hubs or shared services centres, these qualitative attributes are increasingly weighted alongside tax rates and cost structures, particularly when they directly influence the ability to attract and retain top performers.

Implications for Founders, Scale-ups and Investors

For founders and executives in North America, Europe and Asia who follow DailyBusinesss.com for strategic insights, Canada's tech visa regime is not merely an immigration story; it is a business model consideration. High-growth companies in fields such as AI, fintech, cybersecurity, cleantech and health technology are re-evaluating their global footprints, with many adopting hub-and-spoke structures in which engineering, research or regulatory teams are distributed across multiple jurisdictions.

Establishing or expanding a presence in Canadian cities allows these firms to tap into a growing pool of globally sourced talent while also leveraging trade agreements such as the Canada-European Union Comprehensive Economic and Trade Agreement and the Comprehensive and Progressive Agreement for Trans-Pacific Partnership, which facilitate access to markets across Europe, Asia-Pacific and the Americas. Learn more about how such agreements shape cross-border commerce through resources from the World Trade Organization and UNCTAD's investment and trade analysis.

Venture capital and private equity investors are also recalibrating assumptions about where the next generation of category-defining technology companies will emerge. The presence of robust tech visa pathways reduces execution risk for portfolio companies that need to scale teams quickly or relocate key personnel. In parallel, Canadian pension funds and institutional investors, long known for their global infrastructure and real-asset strategies, are increasing their exposure to technology and innovation, reinforcing domestic ecosystems and offering co-investment opportunities to international partners. Readers can connect these trends with broader market developments through DailyBusinesss.com's markets coverage and global news analysis.

For founders themselves, particularly those from emerging markets or regions facing political or economic instability, Canada's visa pathways offer a route to build globally competitive companies in a jurisdiction that values regulatory clarity, investor protection and adherence to international standards. Resources such as Startup Visa programs, provincial innovation agencies and accelerators linked to universities and corporate partners create an integrated support environment that complements the immigration framework. Entrepreneurs can explore how policy and ecosystem support interlock by reviewing insights from the Global Entrepreneurship Monitor and the Kauffman Foundation.

Labour Markets, Wages and Domestic Workforce Development

Any large-scale initiative to attract foreign talent inevitably raises questions about its impact on domestic labour markets, wage dynamics and social cohesion. In Canada's case, the design of the tech visa pathways has attempted to address these concerns by emphasizing complementarity rather than substitution, and by embedding talent attraction within a broader strategy of skills development and upskilling for residents and citizens.

Labour economists and policy analysts, including those at the Conference Board of Canada and Fraser Institute, have noted that in many technology sub-sectors, the demand for specialized skills continues to outpace domestic supply, even in major urban centres. The arrival of experienced international professionals can, in this context, increase overall productivity, create spillover learning effects and support the growth of firms that then hire larger numbers of local graduates in supporting roles. This dynamic has been observed in AI, cloud infrastructure, semiconductors and advanced manufacturing, where global benchmarks from McKinsey & Company and Boston Consulting Group highlight persistent skills gaps.

At the same time, Canadian policymakers have expanded investments in STEM education, digital literacy, reskilling programs and lifelong learning initiatives, ensuring that domestic workers can move into higher-value roles as technologies and business models evolve. Readers interested in how these labour-market strategies intersect with macroeconomic performance can find deeper analysis in DailyBusinesss.com's economics coverage, which regularly examines productivity, employment and growth trends across North America, Europe, Asia and Africa.

The long-term sustainability of Canada's tech visa approach will depend on maintaining public confidence that the benefits of high-skilled immigration are widely shared, that wage standards are upheld and that integration into communities proceeds smoothly. Transparent data, rigorous evaluation and ongoing stakeholder engagement will be critical in this regard, and business leaders have a direct interest in supporting evidence-based discourse.

Sustainability, Inclusion and the Future of Work

A notable feature of Canada's contemporary technology and immigration strategy is its alignment with broader commitments to sustainability, inclusion and responsible innovation. As global investors and corporates increasingly integrate environmental, social and governance criteria into decision-making, destinations that can credibly demonstrate climate leadership, social stability and respect for the rule of law gain a competitive edge in attracting both capital and talent.

Canada has positioned its tech sector as a partner in achieving net-zero targets, with growing clusters in clean energy, carbon capture, battery technology and sustainable finance. Learn more about sustainable business practices and climate-aligned investment through resources from the International Energy Agency and Task Force on Climate-Related Financial Disclosures. These sectors, too, depend heavily on specialized technical skills, and the new visa pathways are being used to attract engineers, data scientists and project managers with experience in large-scale renewable projects, grid modernization and climate analytics.

At the same time, Canadian institutions emphasize ethical AI, privacy protection and human-centric design, aligning with frameworks developed by organizations such as the European Commission and UNESCO. This orientation appeals to professionals who want to work at the frontier of innovation while contributing to systems that respect democratic norms and human rights, a consideration that is becoming more salient as debates over surveillance, algorithmic bias and digital authoritarianism intensify globally.

For the audience of DailyBusinesss.com, which follows developments in sustainable business, technology governance and the future of work, Canada's approach offers a reference point for how advanced economies can integrate talent attraction with broader societal goals, rather than treating them as separate or conflicting agendas.

The Role of Media and Analysis: DailyBusinesss.com's Perspective

As Canada's tech visa pathways mature and their impacts ripple across sectors and borders, independent analysis and informed commentary become essential. DailyBusinesss.com occupies a distinctive position in this landscape by providing integrated coverage that connects immigration policy to developments in AI, finance, crypto, employment, trade and global markets. By situating Canada's experience within a worldwide context that includes the United States, United Kingdom, Germany, France, Italy, Spain, Netherlands, Switzerland, China, Sweden, Norway, Singapore, Denmark, South Korea, Japan, Thailand, Finland, South Africa, Brazil, Malaysia, New Zealand and beyond, the platform helps business leaders and investors understand not only what is happening, but why it matters for their strategic decisions.

Through its coverage of technology and digital transformation, trade and global supply chains, and broader world developments, DailyBusinesss.com highlights how talent mobility interacts with capital flows, regulatory shifts and geopolitical dynamics. The site's emphasis on experience, expertise, authoritativeness and trustworthiness ensures that readers are not merely presented with headline announcements, but with contextualized analysis that links policy initiatives like Canada's tech visas to underlying structural trends in globalization, decarbonization and digitalization.

For executives and founders planning cross-border expansions, evaluating new investment destinations or assessing the resilience of their human-capital strategies, this integrated perspective is increasingly indispensable. It allows them to interpret Canada's visa reforms not as isolated national policies, but as part of a broader reconfiguration of how countries, companies and individuals negotiate opportunity and risk in a rapidly changing world.

Thinking What's to Come for Canada's Place in the Global Tech Talent Map

Canada's experiment with targeted tech visa pathways has positioned it as one of the most attractive jurisdictions for high-skilled technology professionals and innovation-driven enterprises. The combination of streamlined processes, strategic skills targeting, pathways to permanence, and alignment with broader values of sustainability and inclusion has resonated with both individuals and organizations across continents. Yet the global competition for talent is intensifying, and there is no guarantee that early-mover advantages will persist without continued adaptation.

Several factors will shape the next phase of this story. First, the pace of technological change in areas such as generative AI, quantum computing, bioengineering and advanced robotics will continue to create new skills gaps and redefine what counts as "tech talent." Second, demographic trends, including aging populations in many advanced economies, will sustain pressure to attract and retain working-age professionals, even as automation reshapes specific job categories. Third, geopolitical tensions and shifts in global supply chains will influence where companies choose to locate critical functions and how governments calibrate openness and security.

In this evolving landscape, Canada's ability to maintain and enhance its position will depend on preserving policy stability while remaining responsive to industry needs, investing in domestic education and training, and ensuring that the benefits of high-skilled immigration are broadly shared. For global business leaders, investors and founders, closely following these developments through incredibly well researched platforms like DailyBusinesss.com will be essential to making informed, forward-looking decisions.

As the world moves deeper into a digital, data-driven and low-carbon economy, talent will remain the ultimate scarce resource. Canada's tech visa pathways, as they stand, demonstrate how a country can use immigration policy as a strategic instrument to build an innovation-led future. For organizations deciding where to place their next engineering hub, AI lab, fintech venture or sustainable technology project, understanding the nuances of this Canadian model is no longer optional; it is a core component of competitive strategy in a global market where borders are increasingly defined not only by geography, but by ideas, skills and the ability to attract the people who drive them.

Germany's Blueprint for a Green Industrial Economy

Last updated by Editorial team at dailybusinesss.com on Thursday 9 July 2026
Article Image for Germany's Blueprint for a Green Industrial Economy

Germany's Blueprint for a Green Industrial Economy

A New Industrial Chapter for Germany and the World

As the world moves deeper into the second half of the 2020s, Germany's attempt to reconcile heavy industry with climate neutrality has become a reference point for policymakers, investors and corporate leaders from North America to Asia. Once primarily defined by its automotive giants, chemical conglomerates and precision engineering, the German economy is now attempting something far more complex: constructing a green industrial model that maintains global competitiveness while delivering on the European Union's legally binding climate targets and the Paris Agreement. For finance news readers of dailybusinesss.com, whose interests span AI, finance, markets, founders, trade and sustainability, Germany's evolving strategy offers not just a case study in policy design, but a living laboratory for how advanced economies might rewire themselves under the pressure of decarbonization, digitalization and geopolitical fragmentation.

Germany's blueprint is not a single law or program; it is a dense web of climate legislation, industrial policy, infrastructure investment, digital transformation and financial innovation, all operating within the broader framework of the European Union's Green Deal. Understanding how this system works in practice, and where it still struggles, is essential for decision-makers in the United States, the United Kingdom, Canada, Australia, Singapore and beyond who are facing similar challenges in aligning economic resilience with net-zero commitments. In this context, dailybusinesss.com positions itself as a bridge between high-level strategy and the operational realities faced by executives, founders and investors navigating this transition in real time.

The Strategic Foundations of Germany's Green Industrial Turn

Germany's green industrial strategy has been shaped by overlapping forces: the legally binding climate neutrality target for 2045, the EU Green Deal, Russia's invasion of Ukraine and the resulting energy shock, and intensifying competition from the United States and China in clean technologies. The German Climate Change Act set the initial trajectory by mandating steep emissions reductions across sectors, while the EU's Fit for 55 package tightened the regulatory framework, expanded carbon pricing and accelerated the phase-out of internal combustion engines. These measures created a powerful signal to industry that decarbonization was no longer optional but a structural requirement of doing business in Europe. Learn more about the policy architecture behind European climate action at European Commission climate policies.

At the same time, the U.S. Inflation Reduction Act introduced large-scale subsidies for clean energy and low-carbon manufacturing, triggering concerns in Berlin and Brussels about industrial relocation and subsidy competition. German policymakers responded by doubling down on a domestic green industrial agenda that combines support for renewable energy, hydrogen infrastructure, battery manufacturing, semiconductor production and low-carbon heavy industry. For a global view of how industrial policy is reshaping energy and manufacturing, readers can explore analysis from the International Energy Agency.

Within this broader context, dailybusinesss.com has increasingly focused on how German and European policy choices are influencing global capital flows, corporate strategy and employment patterns, especially in sectors such as automotive, chemicals, machinery and advanced materials that are central to international trade and supply chains.

Renewable Power and the Electrification of Industry

The foundation of Germany's green industrial economy is the rapid expansion of renewable electricity and the parallel electrification of industrial processes. Over the past decade, Germany has shifted from a coal- and nuclear-heavy mix toward wind and solar, yet the energy crisis of 2022-2023 exposed vulnerabilities in gas supply and grid capacity that forced a rethinking of both speed and scale. The government's current ambition is to reach an 80 percent share of renewables in electricity consumption by 2030, with an emphasis on offshore wind in the North Sea and Baltic Sea and large-scale solar installations on rooftops and industrial sites. Up-to-date data on Germany's energy transition can be examined via Agora Energiewende.

For energy-intensive industries such as steel, aluminum, cement and chemicals, electrification is both an opportunity and a risk. On one hand, access to abundant, low-cost renewable electricity can become a decisive competitive advantage, especially for companies that can switch to electric arc furnaces, heat pumps, or electric cracking technologies. On the other hand, intermittent supply, grid bottlenecks and high industrial power prices can undermine investment decisions and drive production to regions with cheaper energy. Investors and corporate strategists following these dynamics can deepen their understanding through sectoral insights from BloombergNEF.

The German government has responded by proposing "climate contracts for difference" and targeted electricity price relief for particularly exposed industries, while accelerating grid expansion and cross-border interconnectors to neighboring countries such as Denmark, the Netherlands and France. For readers of dailybusinesss.com, these developments intersect directly with themes covered in its dedicated sections on energy and climate economics and technology-driven industrial transformation, where the financial and strategic implications of electrification are analyzed through a global lens.

Hydrogen, Steel and the Reinvention of Heavy Industry

Hydrogen has become one of the central pillars of Germany's blueprint for decarbonizing heavy industry, particularly steel, chemicals and refining. The country's National Hydrogen Strategy, revised and expanded in the mid-2020s, envisions a large-scale ramp-up of green hydrogen production based on renewable electricity, complemented by imports from regions with abundant solar and wind resources such as North Africa, the Middle East and parts of Australia. Readers can explore the global hydrogen landscape through the Hydrogen Council.

German steelmakers, including thyssenkrupp Steel Europe and Salzgitter AG, are investing in direct reduced iron (DRI) plants that can operate initially on natural gas and later transition to hydrogen, with the goal of producing near-zero-emission steel for automotive and construction customers in Germany, the United Kingdom, Sweden and beyond. This transition is backed by substantial public funding under EU state aid rules and the Important Projects of Common European Interest (IPCEI) framework, which allows governments to support strategic cross-border projects in areas such as hydrogen, batteries and microelectronics. Further information on EU industrial initiatives can be found at European Commission industrial policy.

The chemicals sector, anchored by companies such as BASF, is pursuing a combination of electrified production processes, alternative feedstocks and carbon capture and utilization to reduce emissions while maintaining its position in global value chains. This transformation carries significant implications for employment in regions like North Rhine-Westphalia and Lower Saxony, where industrial clusters have long provided high-wage jobs and export revenues. Readers interested in how these shifts intersect with labor markets and skills development can follow coverage in dailybusinesss.com's employment and future of work section, which analyses workforce transitions in Germany, Scandinavia, North America and Asia.

Finance, Capital Markets and the Cost of Transition

No green industrial strategy can succeed without a robust financial architecture that channels capital into low-carbon infrastructure, innovation and corporate restructuring. Germany's financial sector, anchored by institutions such as Deutsche Bank, Commerzbank and a dense network of regional savings banks and cooperative lenders, has been under pressure to align portfolios with climate goals while maintaining profitability and risk discipline. The European Central Bank's work on climate-related financial risks and the EU Taxonomy for Sustainable Activities have pushed banks, insurers and asset managers to improve disclosure and adjust their lending and investment criteria. Learn more about evolving sustainable finance standards at the European Central Bank climate centre.

At the same time, the rise of green bonds, sustainability-linked loans and transition finance instruments has created new opportunities for German corporates to fund decarbonization projects, from offshore wind farms in the North Sea to low-carbon cement plants in Bavaria. Global investors, including pension funds from Canada, the Netherlands and Australia, as well as sovereign wealth funds from Asia and the Middle East, are increasingly active in these markets, seeking stable, long-term returns aligned with climate objectives. For in-depth coverage of how these instruments are reshaping capital allocation, readers can turn to dailybusinesss.com's dedicated finance and markets insights and its complementary investment coverage.

Yet the cost of transition remains a contentious issue in Germany's public debate. Small and medium-sized enterprises, which form the backbone of the Mittelstand, often lack the internal capacity to navigate complex funding programs or to quantify climate-related risks and opportunities. This has spurred the growth of advisory firms, fintech platforms and specialized funds that support SMEs in developing credible decarbonization plans and accessing green finance. International benchmarks and best practices on climate risk management and disclosure can be explored via the Task Force on Climate-related Financial Disclosures.

AI, Digitalization and Smart Manufacturing in a Green Context

A defining feature of Germany's blueprint is the integration of artificial intelligence and advanced digital technologies into the core of its green industrial strategy. Building on the concept of Industrie 4.0, German manufacturers are deploying AI-driven predictive maintenance, digital twins, advanced robotics and real-time energy optimization to reduce waste, improve efficiency and lower emissions across production lines. These tools not only cut costs but also provide the data transparency required to comply with tightening regulatory standards and customer demands for verified low-carbon products. For a broader overview of AI's industrial applications, readers can consult OECD AI policy resources.

AI also plays a growing role in grid management, renewable forecasting and demand response, enabling Germany to integrate higher shares of variable wind and solar while maintaining system stability. Startups and established firms are developing platforms that coordinate industrial loads, electric vehicle charging and distributed storage, turning factories, logistics centers and office buildings into active participants in the energy system. This convergence of energy and digital infrastructure is a recurring theme in dailybusinesss.com's AI and technology coverage and its broader technology and innovation reporting, which track how data-driven solutions are reshaping value creation across sectors.

The success of this digital layer depends heavily on secure, high-capacity connectivity and strong cyber resilience. As industrial systems become more interconnected, the risk of cyberattacks with physical consequences increases, prompting closer coordination between companies, regulators and security agencies. Global businesses monitoring these risks and opportunities can find further analysis at World Economic Forum cyber and energy insights.

Trade, Geopolitics and the Global Dimension of Germany's Strategy

Germany's green industrial economy cannot be understood in isolation from global trade and geopolitical dynamics. As one of the world's leading export nations, Germany relies on open markets in the United States, the United Kingdom, China and emerging economies across Asia, Africa and South America, while simultaneously facing rising trade tensions, industrial subsidies and strategic rivalry between major powers. The EU Carbon Border Adjustment Mechanism (CBAM), which gradually places a carbon price on certain imports such as steel, aluminum and fertilizers, is a central instrument in this context, designed to prevent carbon leakage and create a level playing field for European producers subject to stringent climate regulation. Detailed information on CBAM and its implementation is available from European Commission CBAM resources.

This mechanism, however, has implications for trading partners in regions like Southeast Asia, South America and Africa, where exporters may need to adapt production processes or face higher costs when accessing the EU market. For globally oriented readers of dailybusinesss.com, especially those following world and trade developments and international trade policy trends, Germany's approach illustrates how climate policy is increasingly intertwined with trade negotiations, supply chain strategies and foreign direct investment decisions.

Germany's blueprint also includes a strong emphasis on securing critical raw materials for batteries, wind turbines, solar panels and hydrogen technologies, often in partnership with countries such as Canada, Australia, Norway, Chile and Namibia. These efforts are linked to the EU Critical Raw Materials Act and broader initiatives to diversify supply chains away from excessive dependence on single suppliers. For context on the global raw materials landscape, readers can consult the International Renewable Energy Agency.

Urban Mobility, Automotive Transformation and the Role of Travel

The transformation of Germany's automotive sector, led by companies such as Volkswagen, Mercedes-Benz Group and BMW, is one of the most visible elements of its green industrial strategy. The shift toward electric vehicles, software-defined cars and new mobility services is reshaping not only manufacturing plants in Bavaria, Baden-Württemberg and Saxony, but also urban planning, charging infrastructure and travel behavior across Europe and North America. Policies at EU level, including the planned phase-out of new internal combustion engine car sales, have accelerated this shift, while global competition from Tesla and emerging Chinese EV manufacturers has raised the stakes for German incumbents. Readers can follow global mobility trends through analysis from the International Transport Forum.

For cities in Germany, the Netherlands, France, Spain and Italy, the rise of electric mobility intersects with broader efforts to redesign transport systems around public transit, cycling and shared mobility, reducing congestion and improving air quality. These changes directly affect business travel patterns, logistics networks and tourism flows, areas that dailybusinesss.com explores in its travel and mobility coverage. The integration of smart charging, vehicle-to-grid technology and AI-based traffic management further illustrates the convergence between transport, energy and digital infrastructure that defines Germany's approach.

Startups, Founders and the Innovation Ecosystem

While large industrial champions attract most of the headlines, Germany's green industrial blueprint also relies on a vibrant ecosystem of startups, research institutions and mid-sized technology firms. Climate-tech founders in Berlin, Munich, Hamburg and the Rhine-Ruhr region are working on solutions ranging from next-generation batteries and power electronics to carbon accounting platforms, circular materials and AI-driven energy optimization. These ventures often emerge from or collaborate closely with leading research organizations such as the Fraunhofer Society and Max Planck Society, as well as technical universities in Munich, Aachen, Berlin and Karlsruhe. Insights into Germany's research and innovation landscape can be found at the German Federal Ministry of Education and Research.

Access to capital remains a critical challenge and opportunity for these founders, especially in comparison with the more mature venture ecosystems of the United States and parts of Asia. European and German initiatives to deepen capital markets, promote green venture funds and attract international investors are therefore an integral part of the broader industrial strategy. For readers of dailybusinesss.com, this intersection of entrepreneurship, technology and sustainability is explored in depth in its founders and startup section, which highlights how climate-focused innovation is reshaping business models from Europe to North America and Asia-Pacific.

Social License, Employment and Regional Cohesion

No industrial transformation can succeed without social acceptance and a credible path for workers and communities affected by structural change. Germany's experience with coal phase-out in regions such as Lusatia and the Rhineland has underscored the need for long-term planning, targeted investment and social dialogue among unions, employers and governments. The country's green industrial blueprint therefore includes measures to support reskilling, vocational training and regional development, aiming to ensure that new green industries create quality jobs in areas that previously depended on fossil-based activities. Comparative perspectives on just transition policies can be explored via the International Labour Organization.

The challenge is particularly acute in industries such as automotive components, where the shift to electric drivetrains reduces the number of parts and alters the skills required, with implications for suppliers in Germany, the Czech Republic, Slovakia, Italy and Spain. Policymakers and business leaders must manage this transition carefully to avoid social backlash that could undermine climate policy and industrial competitiveness. dailybusinesss.com regularly examines these issues in its employment and labor market analysis, connecting developments in Germany with similar debates in the United States, the United Kingdom, South Korea, Japan and emerging economies.

Governance, Measurement and Trust in the Transition

A central question for investors, partners and citizens is whether Germany's green industrial blueprint is credible and on track. This requires transparent governance, robust data and independent evaluation of progress. Germany's climate targets are monitored by expert councils and embedded in EU-wide reporting systems, while corporate climate strategies are increasingly scrutinized by regulators, shareholders and civil society. The rise of standardized ESG reporting frameworks, climate scenario analysis and science-based targets has improved comparability and accountability, though concerns about greenwashing and inconsistent metrics persist. Guidance on corporate climate target setting can be explored through the Science Based Targets initiative.

Trust in the transition also depends on regulatory stability and policy coherence. Businesses investing in long-lived assets such as hydrogen-ready steel plants or offshore wind farms require confidence that carbon prices, subsidy regimes and permitting procedures will not shift unpredictably. Germany's efforts to streamline permitting, accelerate planning for energy and transport infrastructure, and coordinate federal and state-level policies are therefore critical components of its blueprint, even if they attract less attention than headline-grabbing technology announcements. For readers of dailybusinesss.com, these governance aspects are as important as the technological and financial dimensions, since they shape the risk landscape for global investors and corporate strategists.

What Germany's Blueprint Means for Global Business

Germany's emerging green industrial economy is not a finished product; it is a moving target shaped by technological breakthroughs, geopolitical shifts and evolving societal expectations. Nonetheless, it already offers valuable lessons for business leaders and policymakers in North America, Europe, Asia and beyond. It demonstrates that decarbonization in an advanced industrial economy is possible without abandoning manufacturing, but it also illustrates the complexity, cost and political sensitivity of such a transformation. Companies in the United States, the United Kingdom, Canada, Australia, Japan, South Korea and major emerging markets can draw on Germany's experience to design their own strategies, whether in terms of integrating AI into energy-intensive operations, leveraging green finance instruments, or navigating the intersection of climate policy and international trade.

For the loyal audience of dailybusinesss.com, which spans sectors from finance and crypto to travel and tech, Germany's blueprint serves as a real-time case study in how climate, digitalization and globalization are reshaping the fundamentals of business. Its evolution will continue to influence investment decisions, supply chain design, market access and regulatory compliance across continents. By following developments in Germany alongside parallel transitions in regions such as North America, Scandinavia and East Asia, readers can better anticipate the opportunities and risks that will define the next decade of global commerce and industrial strategy.

The Rise of Sovereign Wealth Funds in Global Deals

Last updated by Editorial team at dailybusinesss.com on Wednesday 8 July 2026
Article Image for The Rise of Sovereign Wealth Funds in Global Deals

The Rise of Sovereign Wealth Funds in Global Deals

A New Financial Power Center

Sovereign wealth funds have moved from the periphery of global finance to its very core, reshaping how capital is allocated, how strategic industries are financed, and how governments project economic influence far beyond their borders. For interested readers of dailybusinesss.com, who follow developments in AI, finance, crypto, economics, employment, and global markets, the rise of these state-backed investors is no longer an abstract macroeconomic trend; it is a daily reality that affects deal structures, valuations, regulatory scrutiny, and even the competitive strategies of private investors and corporate leaders across North America, Europe, Asia, Africa, and South America.

Sovereign wealth funds, or SWFs, now manage well over ten trillion dollars in assets globally, according to public estimates from organizations such as the International Monetary Fund and the World Bank, and their influence spans from Silicon Valley venture capital rounds to infrastructure projects in Africa, energy transitions in Europe, logistics hubs in the Middle East, and advanced manufacturing in Asia. As dailybusinesss.com continues to deepen its coverage of global business and markets, understanding how these funds operate, where they are deploying capital, and how they are reshaping the balance of power in global deals has become essential for executives, founders, policymakers, and investors.

What Sovereign Wealth Funds Are - And Why They Matter Now

Sovereign wealth funds are state-owned investment vehicles that manage national wealth for long-term objectives, typically funded by commodity revenues, foreign exchange reserves, fiscal surpluses, or, increasingly, the proceeds of privatizations and structural reforms. Classic examples include Norway's Government Pension Fund Global, the Abu Dhabi Investment Authority, the Qatar Investment Authority, Saudi Arabia's Public Investment Fund, Singapore's GIC and Temasek, and China Investment Corporation. Their mandates vary, but they generally aim to preserve and grow national wealth across generations, diversify away from volatile domestic revenue sources, and support broader economic or strategic goals.

Unlike traditional central bank reserves, which prioritize liquidity and safety, sovereign wealth funds are designed to take on more risk and to invest across a broader spectrum of asset classes, from public equities and bonds to private equity, venture capital, real estate, infrastructure, and alternative assets. As OECD analyses have repeatedly highlighted, their time horizons are typically longer than those of most private funds, which allows them to tolerate short-term volatility in pursuit of structural, multi-decade returns. Learn more about the structure and governance of sovereign wealth funds through the OECD's public materials at oecd.org.

This longer-term perspective has profound implications for global deals. In a world characterized by rising interest rates, geopolitical fragmentation, energy transition pressures, and rapid digitalization, sovereign wealth funds bring patient capital, often combined with government-level relationships and strategic intent. For companies seeking large-scale funding for infrastructure, decarbonization, or disruptive technologies such as artificial intelligence, quantum computing, and biotechnology, SWFs have become indispensable partners. Readers can follow how this capital intersects with technology and innovation in the dedicated AI and tech section of dailybusinesss.com.

From Passive Investors to Strategic Dealmakers

Historically, many sovereign wealth funds preferred relatively passive strategies, building diversified portfolios of listed equities and bonds, typically managed through external asset managers. Over the past decade, and especially in the years leading into 2026, this model has evolved dramatically. Large funds in the Middle East and Asia, in particular, have internalized investment capabilities, built substantial in-house teams, and shifted toward direct investments, co-investments, and strategic partnerships.

Saudi Arabia's Public Investment Fund (PIF) has been emblematic of this shift. Initially known for its domestic holdings, the fund has in recent years become a global dealmaker, backing sectors from electric vehicles and gaming to sports, tourism, and advanced manufacturing, aligning with the country's Vision 2030 strategy. Similarly, Temasek and GIC in Singapore have long operated as sophisticated global investors, with significant allocations to private markets, technology, and sustainable infrastructure. Readers interested in how such moves intersect with global trade and supply chains can explore related analysis at dailybusinesss.com/trade.html.

The shift from passive to active dealmaking has several consequences. First, sovereign wealth funds increasingly compete with private equity firms, pension funds, and large asset managers for attractive assets, often with the advantage of longer time horizons and lower pressure for short-term exits. Second, they frequently seek board seats, governance rights, and strategic influence, especially in sectors deemed critical to their home country's economic transformation, such as renewable energy, semiconductors, logistics, and digital infrastructure. Third, they have become important limited partners and co-investors in major private equity and venture capital funds, giving them insight into deal pipelines and emerging technologies.

Global financial institutions such as BlackRock, Goldman Sachs, and Morgan Stanley now routinely structure transactions with sovereign wealth fund participation in mind, while advisory firms and law firms have developed specialized practices dedicated to SWF clients. More details on evolving institutional investment trends can be found through resources at blackrock.com and goldmansachs.com.

Regional Dynamics: Middle East, Asia, and Beyond

While sovereign wealth funds exist across all continents, their growth and influence are particularly visible in the Middle East and Asia, regions that are central to the interests of the dailybusinesss.com audience. In the Gulf, high energy prices in the early 2020s, combined with ambitious diversification agendas, have turbocharged the asset growth of funds in Saudi Arabia, the United Arab Emirates, Qatar, and Kuwait. These funds are no longer content to simply recycle petrodollars into Western equities; they are proactively shaping global sectors such as aviation, tourism, sports, logistics, and green energy.

In Asia, GIC, Temasek, China Investment Corporation, and other state-backed investors have been instrumental in building regional champions in technology, finance, and infrastructure. Their investments span from North America and Europe to Africa and Latin America, often in partnership with multilateral institutions like the Asian Development Bank and the World Bank Group, as they support cross-border connectivity, digital inclusion, and sustainable development. Learn more about these multilateral initiatives at worldbank.org and adb.org.

European and North American sovereign vehicles, while generally smaller or more conservative, also play important roles. Norway's Government Pension Fund Global, widely regarded as a benchmark for transparency and governance, holds significant stakes in thousands of listed companies worldwide and has become a vocal proponent of environmental, social, and governance (ESG) standards. Its voting policies and exclusion lists are closely watched by corporate boards and investors, including those who follow sustainable business coverage on dailybusinesss.com.

In emerging markets such as Brazil, South Africa, and several Southeast Asian countries, sovereign funds are increasingly used as tools to stabilize economies, channel resource revenues into long-term investments, and attract foreign co-investment into infrastructure and strategic sectors. This regional diversification means that global dealmakers must now navigate a complex landscape of state-backed capital with varying mandates, governance standards, and geopolitical sensitivities.

Sovereign Wealth Funds and the Digital and AI Economy

For the technology and AI sectors that are closely followed by dailybusinesss.com readers, sovereign wealth funds have become critical sources of growth capital. As the cost and complexity of scaling AI infrastructure, cloud platforms, semiconductor fabrication, and advanced research have escalated, traditional venture capital and corporate R&D budgets alone are often insufficient. Sovereign wealth funds, with their ability to commit billions to long-horizon projects, have stepped into this funding gap.

Funds such as Mubadala Investment Company in Abu Dhabi, Qatar Investment Authority, Temasek, and GIC have built extensive portfolios in artificial intelligence, fintech, digital health, and cybersecurity, often backing both established global leaders and emerging startups. Their investments in data centers, subsea cables, and 5G and 6G infrastructure also underpin the physical backbone of the digital economy. Readers can explore how this capital flows into innovation ecosystems through the technology coverage at dailybusinesss.com and tech-focused news.

These investments are not purely financial. In many cases, sovereign wealth funds seek to leverage technology investments to accelerate domestic digital transformation, upskill local workforces, and foster innovation hubs in cities such as Abu Dhabi, Riyadh, Singapore, and Shenzhen. This creates a feedback loop in which global AI and tech companies gain access to capital and markets, while host countries gain technological capabilities and employment opportunities. For deeper context on global AI policy and standards, readers can refer to resources from organizations like the OECD AI Policy Observatory at oecd.ai and the World Economic Forum at weforum.org.

Impact on Global Finance, Markets, and Corporate Strategy

The growing prominence of sovereign wealth funds has reshaped global finance in ways that are highly relevant to corporate leaders, investors, and policymakers who rely on dailybusinesss.com/finance.html and dailybusinesss.com/markets.html for insight. In public markets, SWFs are now among the largest shareholders in many blue-chip companies across the United States, United Kingdom, Germany, France, Japan, and other major economies. Their trading activity, asset allocation decisions, and engagement on governance and ESG issues can influence valuations, sector rotations, and even index compositions.

In private markets, SWFs have become cornerstone investors in large buyout funds, infrastructure funds, and growth equity vehicles, often negotiating preferential terms and co-investment rights. This has contributed to the rise of mega-deals and multi-billion-dollar funding rounds, particularly in sectors such as renewable energy, logistics, healthcare, and digital platforms. Global financial media, including Financial Times and The Wall Street Journal, frequently highlight how SWF participation can validate a deal, lower financing costs, and attract additional investors; more background can be found at ft.com and wsj.com.

Corporate strategy has adapted accordingly. Executives in industries from aviation and hospitality to energy and manufacturing increasingly view sovereign wealth funds as potential strategic partners rather than just financial investors. These partnerships may involve joint ventures, technology transfer, localization commitments, and long-term supply or offtake agreements, especially when deals involve host countries that seek to build domestic capabilities. For example, major renewable energy developers partnering with Middle Eastern or Asian SWFs often agree to establish regional hubs, training programs, and research centers, thereby intertwining corporate strategy with national development agendas.

Governance, Transparency, and Geopolitical Sensitivities

As sovereign wealth funds have expanded their global footprint, questions about governance, transparency, and geopolitical influence have become more pressing. Organizations such as the International Forum of Sovereign Wealth Funds (IFSWF) have promoted voluntary principles-often referred to as the Santiago Principles-that encourage sound governance, accountability, and prudent investment practices. These guidelines, available at ifswf.org, aim to reassure host countries that SWF investments are commercially driven and not tools of covert state policy.

Nevertheless, regulators and policymakers in the United States, European Union, United Kingdom, Australia, and other jurisdictions have tightened foreign investment screening, particularly in sectors deemed sensitive such as defense, critical infrastructure, telecommunications, and advanced technologies. Bodies like the Committee on Foreign Investment in the United States (CFIUS) and the European Commission's foreign direct investment screening mechanism examine certain SWF-backed deals for national security implications. Readers interested in these regulatory dynamics can follow updates from official sources such as treasury.gov and ec.europa.eu.

The interplay between sovereign wealth funds and geopolitics is complex. On one hand, SWF investments can deepen economic interdependence and create shared interests between countries, potentially acting as a stabilizing force in international relations. On the other hand, concerns about strategic dependencies, data security, and political leverage mean that some deals attract intense scrutiny and, occasionally, public controversy. For a business audience, the key takeaway is that SWF-backed investments often require more careful structuring, stakeholder engagement, and regulatory navigation than comparable deals involving purely private capital.

Sovereign Wealth Funds, Sustainability, and the Net-Zero Transition

Sustainability and climate considerations are now central to the strategies of many leading sovereign wealth funds, aligning with the growing emphasis on ESG and net-zero commitments among global investors and corporations. Funds like Norway's Government Pension Fund Global, Temasek, and several Middle Eastern SWFs have adopted climate strategies that involve both reducing portfolio emissions and actively investing in the transition to a low-carbon economy. Learn more about sustainable finance and climate-aligned investing through resources at unepfi.org and unpri.org.

For readers of dailybusinesss.com, this sustainability push intersects with multiple areas of interest: energy markets, infrastructure, employment, and innovation. Sovereign wealth funds have become major financiers of renewable energy projects, including large-scale solar and wind farms, green hydrogen initiatives, and grid modernization efforts in Europe, North America, Asia, and emerging markets. They are also backing technologies such as carbon capture, sustainable aviation fuels, battery storage, and circular economy solutions, often in collaboration with development banks and private investors. Those tracking sustainable business trends can find additional coverage at dailybusinesss.com/sustainable.html.

Moreover, SWFs are increasingly integrating climate risk into their portfolio management, using tools and frameworks developed by organizations such as the Task Force on Climate-related Financial Disclosures (TCFD) and the International Sustainability Standards Board (ISSB). As these standards become more widely adopted, companies seeking SWF capital may face more stringent disclosure requirements and expectations around transition plans, emissions reduction pathways, and governance of climate-related risks. This further reinforces the alignment between sovereign wealth funds and the broader evolution of sustainable capitalism.

Employment, Founders, and the Entrepreneurial Ecosystem

The influence of sovereign wealth funds is also felt at the level of founders, employees, and entrepreneurial ecosystems, areas that dailybusinesss.com covers through its focus on founders and employment. When SWFs participate in late-stage venture rounds, growth equity deals, or strategic partnerships, they can provide not only capital but also market access, credibility, and long-term stability. For founders in the United States, Europe, and Asia, securing a sovereign wealth fund as an anchor investor can accelerate international expansion, facilitate government relationships in new markets, and support large-scale hiring and capability building.

At the same time, SWFs often expect robust governance, professionalization, and alignment with long-term value creation, which can influence how startups and scale-ups structure their boards, incentive plans, and reporting practices. For employees, particularly in technology and infrastructure sectors, SWF-backed projects can create new career opportunities in regions such as the Middle East, Southeast Asia, and Africa, where large-scale development initiatives are underway. Organizations like the International Labour Organization (ILO), accessible via ilo.org, have examined how such investments affect employment patterns and skills development.

From an entrepreneurial ecosystem perspective, several sovereign wealth funds have launched dedicated innovation platforms, venture arms, or co-investment programs with local accelerators and international venture capital firms. These initiatives often target sectors aligned with national priorities-such as fintech in Singapore, clean energy in Europe, or logistics and tourism in the Gulf-thereby shaping the trajectory of startup ecosystems and the types of innovation that receive support.

Crypto, Digital Assets, and Financial Innovation

The intersection between sovereign wealth funds and crypto or digital assets remains cautious but increasingly relevant. While most SWFs have not directly allocated substantial capital to cryptocurrencies, they are closely monitoring the evolution of blockchain technology, tokenization, central bank digital currencies (CBDCs), and regulated digital asset markets. Some have invested indirectly through fintech and infrastructure companies that provide institutional-grade custody, trading, and compliance solutions, reflecting a broader trend of institutionalization in the digital asset space. Readers can follow these developments in more detail at dailybusinesss.com/crypto.html.

Global standard-setting bodies such as the Bank for International Settlements (BIS) and the Financial Stability Board (FSB), accessible at bis.org and fsb.org, have published guidance on the prudential treatment of digital assets and the systemic implications of their growth. Sovereign wealth funds, given their mandate to preserve national wealth and financial stability, tend to align with these cautious, risk-aware perspectives. However, as tokenization of real-world assets and regulated digital exchanges mature, it is likely that SWFs will explore more direct participation, particularly in tokenized infrastructure, green bonds, and other instruments that combine innovation with robust regulatory oversight.

The Future Possible Positions of Sovereign Wealth Funds in Global Deals

Now sovereign wealth funds appear set to consolidate their role as pivotal actors in global finance and business. Demographic pressures, fiscal realities, and the energy transition will shape how they are funded and mandated, while technological disruption and geopolitical competition will influence where and how they invest. For the global business news focused audience of dailybusinesss.com, spanning the United States, United Kingdom, Germany, Canada, Australia, France, Italy, Spain, the Netherlands, Switzerland, China, Sweden, Norway, Singapore, Denmark, South Korea, Japan, Thailand, Finland, South Africa, Brazil, Malaysia, New Zealand, and beyond, several themes are likely to define the next phase.

First, competition for sovereign capital will intensify, especially for large-scale projects in infrastructure, clean energy, advanced manufacturing, and digital ecosystems. Corporates and governments that can offer credible long-term partnerships, stable regulatory environments, and alignment with SWF strategic objectives will have an advantage. Second, transparency, governance, and ESG performance will become even more important as sovereign funds face scrutiny from citizens at home and regulators abroad, reinforcing the need for robust reporting and stakeholder engagement.

Third, the integration of sovereign wealth funds into global innovation and entrepreneurship ecosystems will deepen, with implications for founders, talent flows, and the geography of innovation hubs. Finally, the interplay between SWFs and geopolitics will remain a defining feature, requiring sophisticated risk management and scenario planning from all parties involved in cross-border deals.

For dailybusinesss.com, whose mission is to provide timely, expert, and trustworthy analysis across business, investment, economics, world affairs, and news, the rise of sovereign wealth funds is not merely a niche financial topic; it is a lens through which to understand the evolving architecture of the global economy. As sovereign capital continues to shape the future of industries, regions, and technologies, staying informed about their strategies, priorities, and constraints will be essential for business leaders and investors seeking to navigate an increasingly interconnected and state-influenced financial landscape.

How Quantum Computing Will Disrupt Financial Markets

Last updated by Editorial team at dailybusinesss.com on Tuesday 7 July 2026
Article Image for How Quantum Computing Will Disrupt Financial Markets

How Quantum Computing Will Disrupt Financial Markets

Quantum Computing Moves From Theory to Trading Floor

Quantum computing has shifted decisively from an abstract research topic to a strategic priority for the global financial industry, and DailyBusinesss.com has seen its readers move from curiosity to urgency as boards, regulators, and investors now ask not whether quantum will matter, but how quickly it will reshape pricing, risk, and market structure. While today's quantum machines remain noisy and limited, the trajectory of advances at organizations such as IBM, Google, and IonQ, combined with rapidly expanding quantum software ecosystems, has convinced major banks, asset managers, and exchanges across the United States, Europe, and Asia that they are entering a decade in which quantum capability becomes a core differentiator in trading, risk management, and cybersecurity.

For readers who follow the intersection of technology and markets on DailyBusinesss.com, quantum computing is no longer a distant future topic reserved for research labs; it is becoming a practical question of competitive strategy, capital allocation, and regulatory adaptation. Leading institutions in New York, London, Frankfurt, Singapore, Hong Kong, and Tokyo are already building quantum teams, forming partnerships with hardware providers, and experimenting with hybrid quantum-classical workflows, aware that the firms that master this transition first may enjoy a structural advantage in pricing complex risks and managing capital across global markets. At the same time, regulators in the United States, the European Union, the United Kingdom, and Asia-Pacific are beginning to consider how quantum capabilities may affect market fairness, systemic stability, and cybersecurity standards, adding another layer of complexity that business leaders must understand.

Why Quantum Matters: From Exponential Complexity to Exponential Power

Financial markets are built on models that attempt to capture uncertainty, correlation, and human behavior, yet many of the most important problems in pricing, hedging, and portfolio construction are computationally intractable at large scale for even the fastest classical supercomputers. As derivative books grow in dimensionality, as cross-asset correlations shift rapidly, and as real-time data volumes explode, classical methods struggle to evaluate all relevant scenarios in a timely and cost-effective way. This is particularly evident in areas such as high-dimensional Monte Carlo simulation, portfolio optimization with complex constraints, and the calibration of sophisticated models used in interest rate, credit, and volatility trading.

Quantum computers, by leveraging the principles of superposition and entanglement, promise to process certain classes of problems in ways that scale far more efficiently than classical machines, especially where the underlying mathematics involves optimization, linear algebra, and probability distributions that grow exponentially with the number of variables. Readers can explore how quantum algorithms differ from classical ones through resources such as the MIT explanation of how quantum computing works. While quantum advantage for practical financial workloads has not yet been fully demonstrated, early experiments and proofs of concept suggest that quantum methods could one day cut the time needed for complex risk calculations from hours to minutes, or enable entirely new classes of models that are currently infeasible.

For executives following technology trends via the DailyBusinesss technology section at https://www.dailybusinesss.com/technology.html, the key takeaway is that quantum computing is not just "faster computing"; it is a different paradigm that may unlock value precisely where current systems hit a wall, especially in the most computationally intensive corners of global finance.

Quantum-Enhanced Pricing, Risk, and Portfolio Construction

One of the most immediate areas where quantum computing may disrupt financial markets is in pricing and risk analytics, which lie at the core of trading, structuring, and asset management. Complex derivatives, especially in interest rates, credit, commodities, and equity exotics, require sophisticated models and large-scale simulations to determine fair value and risk sensitivities. In stressed markets, when volatility spikes and correlations break down, the speed and accuracy of these calculations become even more critical, as risk managers must revalue large books under rapidly changing conditions.

Quantum algorithms such as quantum amplitude estimation and quantum Monte Carlo have been studied by researchers at Goldman Sachs, J.P. Morgan, and academic institutions as potential accelerators for option pricing and risk aggregation. Readers interested in the mathematical underpinnings can review introductions from organizations like the Bank for International Settlements, which has examined innovation in financial technologies. While today's noisy intermediate-scale quantum (NISQ) devices cannot yet handle production-scale portfolios, pilot projects in the United States, United Kingdom, Germany, and Singapore are already testing whether hybrid quantum-classical methods can reduce the number of samples needed for accurate Monte Carlo estimates, thereby improving both speed and energy efficiency.

In parallel, portfolio optimization, which involves maximizing expected return for a given level of risk under multiple constraints, has emerged as another promising domain. Quantum approximate optimization algorithms (QAOA) and related methods are being explored to handle large, combinatorial portfolio problems where traditional solvers become increasingly slow or require simplifying assumptions that degrade solution quality. Asset managers in North America, Europe, and Asia are particularly interested in whether quantum techniques can help integrate more complex environmental, social, and governance constraints into portfolios, aligning with sustainable investment strategies that many DailyBusinesss.com readers monitor closely.

Although real-world deployment remains experimental, the direction of travel is clear: as quantum hardware matures and error correction improves, financial institutions that have already built internal expertise will be positioned to translate theoretical speedups into practical advantages in pricing accuracy, risk awareness, and portfolio efficiency.

Quantum Risk for Cryptography, Crypto Assets, and Market Infrastructure

If quantum computing promises opportunity on the analytics side, it also introduces a profound new category of risk, particularly in cryptography and digital asset markets. Much of today's financial infrastructure, from interbank messaging to trading platforms and custody systems, relies on public-key cryptography schemes such as RSA and elliptic-curve cryptography, which are considered secure because classical computers would require astronomical time to break them. Quantum algorithms, most notably Shor's algorithm, theoretically enable the factoring of large integers and the breaking of these schemes in polynomial time once sufficiently powerful fault-tolerant quantum computers exist.

Authorities such as the National Institute of Standards and Technology (NIST) are already advancing post-quantum cryptography standards, and regulators in the United States, Europe, and Asia are beginning to push financial institutions toward migration planning. For readers tracking the broader technology and security landscape through https://www.dailybusinesss.com/tech.html, the implication is that quantum resilience is becoming a board-level cybersecurity issue rather than a niche technical concern. Large banks, exchanges, and market utilities are mapping cryptographic dependencies across payment systems, trading platforms, and settlement networks to assess how long it will take to upgrade and how to coordinate across jurisdictions.

The quantum threat also touches the world of cryptocurrencies and digital assets, which DailyBusinesss.com covers in depth at https://www.dailybusinesss.com/crypto.html. Many public blockchains rely on cryptographic assumptions that could be undermined in a post-quantum world, raising questions about the long-term security of wallets, signatures, and transaction histories. While some projects are experimenting with quantum-resistant signature schemes, and researchers at organizations like European Central Bank and Bank of England have examined digital currency resilience, the broader crypto ecosystem remains in transition. Market participants in the United States, Europe, and Asia must therefore consider quantum risk not only when evaluating traditional financial infrastructure, but also when assessing the durability and valuation of digital assets that may be held for decades.

Competitive Dynamics: Quantum Arms Race Among Global Financial Centers

Quantum computing is already reshaping the competitive landscape among financial institutions and among global financial centers, as firms and jurisdictions race to acquire expertise, form partnerships, and influence emerging standards. Large universal banks in the United States such as J.P. Morgan, Bank of America, and Citigroup, as well as European players like BNP Paribas, Deutsche Bank, and UBS, and Asian institutions including Mitsubishi UFJ, DBS, and ICBC, have established dedicated quantum research teams or partnerships with quantum hardware and software providers. These collaborations often aim to test use cases in derivatives pricing, risk management, portfolio optimization, and fraud detection, while also building internal human capital that will be essential once scalable quantum machines become available.

Financial centers such as New York, London, Frankfurt, Zurich, Singapore, Hong Kong, and Tokyo are seeking to position themselves as hubs for quantum finance, leveraging national and regional quantum initiatives. Governments in the United States, European Union, United Kingdom, China, and Japan have launched multi-billion-dollar quantum programs, details of which can be explored through resources like the European Commission's overview of quantum technologies in Europe. These initiatives often include funding for quantum research, incentives for industry collaboration, and support for startups building quantum software and middleware tailored to financial applications.

For the global readership of DailyBusinesss.com, which spans North America, Europe, Asia, and emerging markets, this emerging quantum arms race raises strategic questions: how should mid-sized banks, insurers, and asset managers in Canada, Australia, the Nordics, or Southeast Asia respond when they lack the scale of the largest Wall Street or City of London institutions? Many are opting for consortia approaches, joining regional quantum innovation hubs or industry groups that share knowledge and pool resources, while also leveraging cloud-based access to quantum hardware offered by providers like Amazon Web Services, Microsoft Azure, and Google Cloud, whose cloud quantum services are explained on their respective sites such as Microsoft's quantum overview.

As with earlier technology waves, the institutions that engage early, experiment pragmatically, and cultivate talent are likely to be better positioned than those that wait for quantum technology to fully mature, especially in markets where margins are thin and analytical edge matters.

Regulation, Systemic Risk, and Market Integrity in a Quantum Era

Regulators and central banks are beginning to recognize that quantum computing will not only transform the toolkit of individual firms but may also affect systemic risk, market integrity, and the fairness of competition. If certain institutions gain access to quantum-enhanced analytics that materially improve pricing, hedging, or arbitrage, questions arise about information asymmetry and the potential for destabilizing feedback loops in already complex markets. Supervisors in the United States, United Kingdom, euro area, and Asia are therefore studying quantum's implications for stress testing, capital requirements, and the supervision of algorithmic trading.

Organizations such as the Financial Stability Board (FSB) and the International Monetary Fund (IMF) have started to discuss emerging technology risks in finance, including quantum, within their broader work on digitalization and cyber resilience. Particular attention is being paid to the possibility that quantum capabilities could be used to compromise cryptographic keys at systemically important financial institutions or market infrastructures, triggering loss of confidence or operational disruption. Regulators are also considering how to ensure that post-quantum cryptography migration is coordinated across borders, given the globally interconnected nature of payments, clearing, and settlement networks.

For business leaders and risk officers who follow regulatory developments through the DailyBusinesss economics and markets coverage at https://www.dailybusinesss.com/economics.html and https://www.dailybusinesss.com/markets.html, the policy message is clear: quantum computing is moving onto the supervisory agenda, and firms that can demonstrate proactive planning around quantum risk and opportunity will likely be viewed more favorably by regulators and rating agencies. Over time, regulators may also require more transparency around the use of advanced quantum algorithms in trading and risk management, in order to understand model behavior and potential systemic interactions.

Talent, Culture, and the Quantum Skills Gap

Behind every quantum strategy lies a human capital challenge: the need to bridge the worlds of quantum physics, computer science, and financial engineering. There is already a global shortage of professionals who understand both the technical details of quantum algorithms and the practical realities of trading desks, risk committees, and regulatory frameworks. Universities in the United States, United Kingdom, Germany, Canada, Australia, and Singapore are expanding quantum information science programs, and some business schools are beginning to integrate quantum topics into finance and analytics curricula, as highlighted by institutions such as Harvard Business School and INSEAD, which discuss emerging technologies in business education.

For banks, asset managers, and fintechs, the skills challenge is not simply hiring PhD-level quantum scientists, but building cross-functional teams where quants, traders, risk managers, and technologists can collaborate effectively on quantum use cases. Many firms are pursuing a layered approach: upskilling existing quantitative staff through internal training, sponsoring specialized courses, and partnering with universities and startups, while also recruiting a smaller number of deep technical experts. This mirrors the evolution seen in earlier waves of financial technology, from high-frequency trading to machine learning, but with the added complexity that the underlying physics and hardware constraints are unfamiliar to most traditional IT teams.

Readers who track employment and skills trends via https://www.dailybusinesss.com/employment.html will recognize that quantum finance is likely to become an important niche in the global job market, especially in major financial centers and technology hubs. Countries such as the United States, Canada, Germany, the Netherlands, Sweden, Singapore, and Japan, which have both strong financial sectors and active quantum research communities, may become magnets for quantum-finance talent, intensifying competition for specialized skills and influencing where firms choose to locate key analytics and trading functions.

Strategic Roadmaps for Boards, Founders, and Investors

For boards, founders, and investors who rely on DailyBusinesss.com for strategic insight into AI, finance, and emerging technologies, the practical question is how to act now in a way that is proportionate to both the promise and the uncertainty of quantum computing. Overcommitting capital to speculative hardware bets is risky, yet ignoring quantum entirely could leave firms unprepared for a step-change in analytical capability and cybersecurity requirements. The most forward-looking organizations are therefore treating quantum as a strategic option: investing enough to build internal literacy, test early use cases, and form ecosystem partnerships, while remaining flexible as the technology and regulatory environment evolve.

From a corporate strategy perspective, this often means establishing a small, focused quantum working group that reports to the chief technology officer, chief risk officer, or chief investment officer, tasked with mapping potential use cases in pricing, risk, portfolio management, and operations, and with monitoring developments in hardware, software, and standards. Investors, including venture capital and private equity funds that follow trends at https://www.dailybusinesss.com/investment.html, are increasingly evaluating startups that offer quantum-inspired algorithms, quantum-safe cybersecurity solutions, or middleware that makes it easier for financial institutions to access quantum hardware through the cloud.

Founders in fintech hubs from New York and London to Berlin, Toronto, Singapore, and Sydney are exploring niches where quantum or quantum-inspired methods can deliver near-term value, even before full-scale quantum advantage is achieved. Some focus on hybrid algorithms that run efficiently on classical hardware but can later be ported to quantum machines, while others help institutions inventory cryptographic assets and plan migrations to post-quantum standards. Strategic investors, including corporate venture arms of major banks and exchanges, are selectively backing these ventures, aware that early exposure may yield both financial returns and strategic insight into quantum's trajectory.

Quantum, AI, and the Future Operating Model of Markets

Quantum computing is emerging alongside another transformative technology wave: artificial intelligence. For the global business audience of DailyBusinesss.com, which follows AI developments at https://www.dailybusinesss.com/ai.html, the interplay between quantum and AI will be particularly important in finance, where machine learning is already embedded in trading, credit scoring, fraud detection, and customer analytics. Researchers are exploring quantum machine learning algorithms that could, in theory, accelerate certain training tasks or enable new forms of pattern recognition in high-dimensional financial datasets.

In practice, the near-term impact is likely to come from hybrid architectures where classical AI models handle most workloads, while quantum routines are invoked for specific subproblems such as optimization or sampling. Over time, as both AI and quantum mature, the operating model of financial markets may shift toward a more automated, algorithmically driven environment in which human oversight focuses on governance, ethics, and strategic direction, while machines handle the bulk of micro-level decision-making. Institutions that understand how to orchestrate AI and quantum capabilities together, while maintaining robust controls and explainability, may enjoy a durable competitive edge.

Global policy discussions, including those at the World Economic Forum, which has published analyses on the future of financial services and emerging technologies, are beginning to consider how this convergence of AI and quantum may affect market structure, employment, and inclusion. Questions arise about whether advanced analytics will concentrate power in the hands of a few technologically sophisticated institutions, or whether cloud-based access and open-source tools will democratize quantum-enhanced finance across regions, including emerging markets in Africa, South America, and Southeast Asia.

Positioning for a Quantum-Disrupted Financial Future

Guess what, quantum computing remains an emerging technology, but the direction of disruption for financial markets is increasingly visible to those who track technology, finance, and policy through platforms like DailyBusinesss.com and its dedicated business coverage. Pricing, risk analytics, portfolio optimization, cryptography, and market infrastructure are all poised to be reshaped as quantum hardware scales, error correction improves, and software ecosystems mature. The timeline for full-scale quantum advantage in finance remains uncertain, and will likely vary by use case and region, but the strategic imperative for decision-makers is clear: treat quantum as a material, medium-term factor in technology planning, risk management, and competitive strategy.

For institutions across the United States, United Kingdom, Germany, Canada, Australia, France, Italy, Spain, the Netherlands, Switzerland, China, Sweden, Norway, Singapore, Denmark, South Korea, Japan, Thailand, Finland, South Africa, Brazil, Malaysia, and New Zealand, the challenge is to balance prudence with ambition. That involves building literacy at the board and executive level, fostering collaboration between quants, technologists, and risk professionals, engaging with regulators and industry bodies, and selectively investing in pilots and partnerships that illuminate where quantum can deliver real value. It also requires attention to quantum-safe cybersecurity, so that the benefits of quantum analytics do not come at the cost of heightened vulnerability.

Ultimately, the disruption that quantum computing will bring to financial markets is not predetermined; it will be shaped by the choices of firms, regulators, technologists, and investors over the coming decade. By following developments closely, engaging critically with both hype and skepticism, and grounding decisions in rigorous analysis, the global business community that turns to DailyBusinesss.com for incredible, cutting edge insight can help ensure that quantum's impact on finance enhances resilience, fairness, and long-term value creation across markets and regions. For those willing to invest in understanding and experimentation today, the coming quantum era may offer not only risks to be managed, but also significant opportunities to redefine how financial markets operate in a more complex, data-rich, and interconnected world.