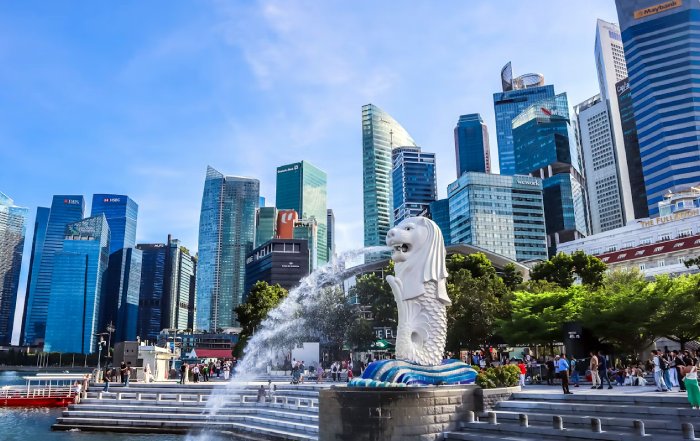
Singapore Cements Its Asian Financial Hub Status

Last updated by Editorial team at dailybusinesss.com on Monday 23 February 2026
Article Image for Singapore Cements Its Asian Financial Hub Status

Singapore Cements Its Asian Financial Hub Status

Singapore's Strategic Position in the Global Financial System

By 2026, Singapore has decisively consolidated its position as one of the world's most important financial hubs, not only in Asia but in the broader global system that connects capital, talent, technology and trade. For the international business audience of DailyBusinesss.com, this evolution is not an abstract macroeconomic story; it is a practical reality that shapes capital allocation decisions, market entry strategies, hiring plans and risk management frameworks across sectors from traditional banking and asset management to digital assets, sustainable finance and advanced technology services. Singapore's ascent reflects a deliberate blend of long-term policy planning, disciplined regulation, aggressive investment in infrastructure and a consistent emphasis on transparency and rule of law, which together have attracted multinational institutions, high-growth founders and sophisticated investors from the United States, Europe and across Asia.

While financial centers such as New York, London, Hong Kong, Tokyo and Shanghai continue to play central roles, Singapore has carved out a distinctive niche as a neutral, innovation-friendly and politically stable gateway between East and West. The Monetary Authority of Singapore (MAS), acting both as central bank and integrated financial regulator, has been central to this trajectory, fostering a regulatory environment that is simultaneously stringent and agile, enabling the city-state to adapt quickly to shifts in global financial markets, regulatory expectations and technological trends. For executives and investors tracking developments through resources such as DailyBusinesss business coverage, Singapore's model offers a reference point for understanding how policy, technology and capital can be aligned to support long-term competitiveness.

Regulatory Strength, Stability and the Rule of Law

Singapore's reputation as a trusted financial hub has been built on decades of legal certainty, political stability and consistent regulatory standards. The city-state's legal framework, grounded in English common law, provides a predictable environment for contract enforcement, dispute resolution and cross-border transactions, which is particularly valued by multinational corporations and global financial institutions managing complex international portfolios. Independent assessments from organizations such as the World Bank and the World Economic Forum have repeatedly highlighted Singapore's strong governance, low corruption and robust regulatory quality, attributes that underpin its attractiveness to institutional investors, sovereign wealth funds and high-net-worth individuals.

The Monetary Authority of Singapore has developed a reputation among global regulators as a sophisticated and credible counterpart, participating actively in international standard-setting bodies such as the Bank for International Settlements, the Financial Stability Board and the International Organization of Securities Commissions, and aligning domestic regulation with evolving global norms on capital adequacy, anti-money-laundering standards and market conduct. For decision-makers following broader macroeconomic dynamics via DailyBusinesss economics insights, Singapore's regulatory approach illustrates how careful calibration of prudential rules can support both financial stability and innovation.

In parallel, Singapore's emphasis on legal predictability and efficient dispute resolution, including through institutions like the Singapore International Commercial Court and the Singapore International Arbitration Centre, has positioned the city as a preferred venue for resolving cross-border commercial disputes, particularly those involving parties from Asia, Europe and North America. This legal infrastructure, combined with the country's strong contract enforcement record, reduces the perceived risk premium for investors and lenders, encouraging the use of Singapore as a base for regional treasury centers, project finance structures and complex trade finance arrangements that span Asia and beyond.

Capital Markets, Banking and Asset Management Depth

Singapore's role as a financial hub is underpinned by the breadth and depth of its banking sector, capital markets and asset management industry. The city hosts a dense concentration of global banks, including JPMorgan Chase, Citigroup, HSBC, Standard Chartered, UBS, Credit Suisse (now part of UBS Group), Deutsche Bank and major regional institutions such as DBS Bank, OCBC Bank and UOB, all of which operate significant regional headquarters or booking centers in the city-state. The presence of these institutions, alongside a growing ecosystem of boutique investment firms, family offices and specialist asset managers, has transformed Singapore into a central node for managing wealth and corporate capital from across Asia, Europe, the Middle East and the Americas.

The Singapore Exchange (SGX) has continued to evolve as a multi-asset platform, offering equities, fixed income, derivatives and commodity products that connect investors to growth opportunities across Asia and beyond. While Singapore's equity market is smaller in market capitalization than those of the United States, China or Japan, its derivative markets, particularly in equity index futures and foreign exchange, have become critical tools for global investors hedging or expressing views on Asian risk. For readers of DailyBusinesss markets analysis, SGX's role in price discovery and risk transfer illustrates how regional exchanges can integrate into global trading strategies, especially when combined with reliable clearing and settlement infrastructure.

Asset management has been a central pillar of Singapore's financial strategy, with the city attracting both traditional and alternative managers seeking proximity to Asian clients and investment opportunities. Major global players such as BlackRock, Vanguard, Fidelity, PIMCO, KKR, Carlyle, Apollo and Bridgewater Associates have expanded their Singapore footprint, while the city has also become a favored base for hedge funds, private equity funds and real estate investment managers targeting markets from India and Southeast Asia to China and Australia. Studies from bodies such as the OECD and the IMF highlight how cross-border capital flows increasingly route through hubs like Singapore, reflecting both tax efficiency and operational advantages, and underscoring the city's importance in global asset allocation decisions.

Digital Finance, AI and the Future of Financial Services

From the perspective of DailyBusinesss.com readers focused on AI, fintech and the future of financial services, Singapore's deliberate positioning as a digital finance leader is particularly noteworthy. The Monetary Authority of Singapore has invested heavily in supporting innovation through initiatives such as the FinTech Regulatory Sandbox, digital bank licensing frameworks and public-private partnerships around payments, regtech and digital identity. These efforts have attracted a wave of technology-driven firms, including regional leaders like Grab, Sea Group and Gojek, as well as global technology companies such as Google, Meta, Amazon Web Services and Microsoft, which have established significant cloud and AI operations in the city.

Singapore's emergence as a hub for AI-driven finance has been underpinned by investments in data infrastructure, talent development and cybersecurity, as well as by collaboration between regulators, universities and industry. Institutions such as the National University of Singapore and Nanyang Technological University have developed strong research capabilities in machine learning, data science and financial engineering, feeding a pipeline of skilled professionals into banks, asset managers and fintech startups. For executives monitoring AI trends through DailyBusinesss AI coverage, Singapore provides a practical case study of how a compact, highly connected economy can integrate AI into mainstream financial operations, from automated credit scoring and algorithmic trading to fraud detection and personalized wealth management.

The city's digital payments landscape has advanced rapidly, with initiatives like PayNow, FAST and cross-border payment linkages with Thailand, Malaysia and India demonstrating how real-time, low-cost payment infrastructure can support trade, tourism and remittances across borders. International organizations such as the Bank for International Settlements have highlighted Singapore's role in experimental projects around central bank digital currencies and interoperable payment systems, which could reshape cross-border settlement in the coming decade. For technology-oriented readers who follow DailyBusinesss technology insights, these developments illustrate how payment innovation, AI and cloud computing are converging to redefine what it means to be a financial hub in the 2020s and beyond.

Crypto, Digital Assets and Tokenization

Digital assets and blockchain-based finance have been another area where Singapore has sought to balance innovation with regulatory prudence. While speculative excesses in global cryptocurrency markets have led many jurisdictions to tighten rules or adopt restrictive stances, Singapore has pursued a more nuanced approach, allowing carefully supervised experimentation while emphasizing investor protection and financial integrity. The Payment Services Act and subsequent regulatory updates have created a licensing regime for digital payment token service providers, requiring compliance with anti-money-laundering and counter-terrorism financing standards, as well as clear disclosures to retail investors.

Global exchanges and crypto-native firms such as Binance, Coinbase, Crypto.com and OKX have engaged with Singapore's regulatory framework in varying ways, and while not all have secured full licenses, the city remains a critical hub for institutional digital asset activity in Asia. Projects focused on tokenization of real-world assets, including tokenized bonds, funds and real estate, have attracted attention from banks and asset managers, with MAS-led initiatives such as Project Guardian exploring how distributed ledger technology can be applied to wholesale funding markets and asset management. For readers interested in digital assets who follow DailyBusinesss crypto coverage, Singapore's stance demonstrates that a jurisdiction can support blockchain innovation without compromising on regulatory standards or investor safeguards.

International standard setters, including the Financial Action Task Force and the International Monetary Fund, have increasingly emphasized the need for coherent regulatory frameworks for digital assets, and Singapore's experience is often cited as an example of how to integrate these new technologies into existing financial systems. As tokenization gains traction among institutional investors in the United States, Europe and Asia, Singapore's legal clarity, sophisticated banking sector and advanced digital infrastructure position it to play a central role in the emerging global architecture of digital capital markets.

Sustainable Finance and the ESG Imperative

Sustainable finance has become a defining theme in global capital markets, and Singapore has moved rapidly to establish itself as a regional hub for green, social and sustainability-linked finance. The government's Green Plan 2030 and related initiatives have created a national framework for decarbonization, while MAS has introduced grant schemes, disclosure guidelines and taxonomies aimed at supporting the issuance of green bonds, sustainability-linked loans and transition finance instruments. The city has attracted sustainability-focused teams from global banks, asset managers and rating agencies, positioning itself as a center for structuring, verifying and distributing ESG-related financial products across Asia.

Global bodies such as the International Sustainability Standards Board and the Task Force on Climate-related Financial Disclosures have driven convergence in sustainability reporting standards, and Singapore has been proactive in aligning domestic disclosure requirements with these evolving norms. This alignment is particularly important for multinational corporations and investors who must comply with regulatory expectations in the European Union, the United States and other major jurisdictions while operating in Asia. For readers tracking the intersection of finance and climate through DailyBusinesss sustainable business coverage, Singapore's role in building ESG market infrastructure highlights the importance of trusted hubs in accelerating the flow of capital toward low-carbon and socially responsible projects.

Regional demand for sustainable finance is growing rapidly as economies such as China, India, Indonesia, Vietnam and Thailand pursue energy transitions, infrastructure modernization and climate resilience projects. Singapore's ability to mobilize international capital, structure complex blended finance vehicles and provide specialized expertise in areas such as green taxonomy alignment, sustainability reporting and impact measurement gives it a competitive advantage as a gateway for ESG investments into Asia. International organizations like the United Nations Environment Programme Finance Initiative and the World Resources Institute have worked with Singapore-based institutions on sustainable finance initiatives, further reinforcing the city's reputation as a credible and forward-looking ESG hub.

Talent, Employment and the Founders' Ecosystem

A financial hub is ultimately built on people, and Singapore's deliberate cultivation of a deep, international talent pool has been central to its success. The city's immigration policies, education system and quality of life have attracted professionals from the United States, the United Kingdom, Germany, France, India, China, Australia and across Southeast Asia, creating a cosmopolitan workforce that is comfortable operating across borders and cultures. Employment opportunities span traditional finance, fintech, technology, legal services, consulting and corporate functions, making Singapore an increasingly attractive destination for mid-career professionals and senior executives seeking regional or global roles.

For readers following labor market dynamics through DailyBusinesss employment coverage, Singapore's approach to talent management offers insights into how small, open economies can compete in the global war for skills. Initiatives such as the Tech.Pass and various employment pass refinements have aimed to attract high-caliber technologists, founders and investors, while local upskilling programs and partnerships between universities and industry aim to ensure that Singaporean workers can participate fully in new growth sectors. The city's emphasis on continuous education, professional certification and cross-functional skills has supported the development of a workforce that is adaptable to rapid technological and regulatory change.

At the same time, Singapore has cultivated a vibrant startup and founders' ecosystem that complements its role as a financial hub. The presence of regional headquarters for venture capital firms, corporate venture arms and private equity funds has created a robust funding environment for startups in fintech, AI, enterprise software, logistics, healthtech and climate tech. Government-linked investors such as Temasek and GIC, along with accelerators and incubators, have played catalytic roles in supporting early-stage ventures. For entrepreneurs and investors tracking opportunities through DailyBusinesss founders section, Singapore's ecosystem demonstrates how access to capital, mentorship and regional markets can be combined to create a launchpad for companies seeking to scale across Asia-Pacific.

Trade, Connectivity and the Real Economy

Singapore's status as a financial hub cannot be separated from its role as a global trade and logistics center. Strategically located at the crossroads of major shipping lanes, the city is home to one of the world's busiest ports and a major air cargo hub, connecting manufacturers, suppliers and consumers across Asia, Europe, the Middle East, Africa and the Americas. This physical connectivity underpins its financial services, as trade finance, commodity trading, shipping finance and supply chain financing are all deeply integrated into the city's economic fabric. Organizations such as the World Trade Organization and the International Chamber of Commerce have highlighted Singapore's role in promoting open trade regimes, efficient customs procedures and digital trade facilitation, all of which support the flow of goods and capital.

For global businesses following DailyBusinesss trade and world coverage, Singapore's network of free trade agreements, including participation in the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) and the Regional Comprehensive Economic Partnership (RCEP), provides a platform for accessing markets across Asia-Pacific and beyond. These agreements, combined with robust infrastructure and pro-business policies, have encouraged multinational corporations in sectors such as pharmaceuticals, electronics, consumer goods and logistics to base regional headquarters or treasury centers in Singapore, further reinforcing the city's financial ecosystem.

The interplay between trade, travel and finance is also evident in Singapore's tourism and aviation sectors, anchored by Changi Airport, consistently ranked among the world's leading airports. As global travel patterns recover and evolve, Singapore's role as a hub for business travel, conferences and high-level diplomatic engagements continues to support deal-making, investor roadshows and cross-border collaboration. For readers interested in how mobility shapes business strategy, DailyBusinesss travel insights provide context on how air connectivity and hospitality infrastructure underpin the city's broader economic and financial ambitions.

Geopolitics, Risk and the Search for Neutral Ground

In an era marked by geopolitical tension, regulatory fragmentation and shifting supply chains, Singapore's perceived neutrality and diplomatic agility have become increasingly valuable to global investors and corporations. The city-state maintains strong relationships with the United States, China, the European Union, India and key regional partners, positioning itself as a trusted interlocutor and stable base of operations in a turbulent environment. International think tanks such as the Carnegie Endowment for International Peace and the Brookings Institution have noted Singapore's careful balancing act, which seeks to preserve open trade and investment flows while navigating complex strategic rivalries.

For multinational corporations and financial institutions reassessing their Asia strategies in light of supply chain diversification, regulatory shifts and political risk, Singapore offers a relatively low-risk jurisdiction with robust legal protections, predictable policy-making and strong connectivity. This has led to a gradual reallocation of some regional headquarters, trading desks and risk management functions from other cities in the region to Singapore, a trend closely watched by readers of DailyBusinesss global business news. While Singapore does not seek to replace other major hubs, its ability to provide a stable base that is acceptable to stakeholders across different geopolitical blocs enhances its attractiveness as a financial center.

Looking Ahead: Singapore's Next Phase as a Financial Hub

As 2026 unfolds, Singapore's status as an Asian and global financial hub appears well entrenched, yet the city-state faces a series of strategic challenges and opportunities that will shape its next phase of development. Intensifying competition from other regional centers, evolving regulatory expectations, rapid technological change and the imperative to support sustainable and inclusive growth all require continuous adaptation. Policymakers, regulators and industry leaders in Singapore are acutely aware that past success does not guarantee future relevance, and that maintaining the city's competitive edge will depend on its ability to innovate, attract talent, manage risks and align with global standards.

For the international audience of DailyBusinesss.com, which spans investors, founders, executives and policymakers across North America, Europe, Asia, Africa and Latin America, Singapore's experience offers both a benchmark and a source of practical insight. By combining strong institutions, prudent regulation, open trade, advanced digital infrastructure and a relentless focus on talent and innovation, Singapore has demonstrated how a small state can punch far above its weight in the global financial system. As readers explore related themes across DailyBusinesss finance coverage, investment analysis and technology reporting, Singapore's trajectory will remain a critical reference point for understanding the evolving architecture of global finance, the future of work in financial services and the shifting balance of economic power in the twenty-first century.
ESG Reporting Standards Face Consolidation

Last updated by Editorial team at dailybusinesss.com on Monday 23 February 2026
Article Image for ESG Reporting Standards Face Consolidation

ESG Reporting Standards Face Consolidation: What 2026 Means for Global Business

The End of the Wild West Era in ESG Reporting

By 2026, environmental, social and governance (ESG) reporting has moved from a voluntary public relations exercise to a core component of financial and strategic disclosure for companies across North America, Europe, Asia-Pacific and key emerging markets. For the global readership of dailybusinesss.com, which spans executives, investors, founders and policymakers, the most important structural shift is clear: ESG reporting standards, once fragmented and often confusing, are undergoing rapid consolidation around a smaller set of globally recognized frameworks, driven by regulators, capital markets and large institutional investors who now treat sustainability data as financially material information rather than soft, aspirational content.

This consolidation is not merely a technical debate among accountants and sustainability officers; it is reshaping how boards make capital allocation decisions, how investors price risk and opportunity, how founders in the United States, Europe and Asia design their business models, and how employees evaluate employers in markets as diverse as Germany, Singapore, Brazil and South Africa. As dailybusinesss.com has explored across its coverage of business strategy, finance and capital markets and technology innovation, ESG has become deeply intertwined with core themes such as digital transformation, climate transition, regulatory risk and geopolitical fragmentation, creating both new burdens and new sources of competitive advantage for companies that navigate the emerging reporting landscape with sophistication and discipline.

From Alphabet Soup to a Global Baseline

For more than a decade, companies and investors wrestled with an alphabet soup of ESG standards and frameworks, from the Global Reporting Initiative (GRI) to the Sustainability Accounting Standards Board (SASB), the Task Force on Climate-related Financial Disclosures (TCFD), the CDP climate disclosure system and numerous regional and industry-specific guidelines. While these initiatives advanced transparency and awareness, they also created confusion, duplication of effort and inconsistent data, frustrating both corporate reporters and users of ESG information. The turning point came when global and regional standard-setters recognized that sustainability-related information must be integrated into mainstream financial reporting, rather than live in a parallel universe of standalone sustainability reports.

The creation of the International Sustainability Standards Board (ISSB) under the umbrella of the IFRS Foundation, which also oversees the International Accounting Standards Board (IASB), marked a decisive step toward a global baseline of investor-focused sustainability disclosure. By consolidating the work of SASB and the Climate Disclosure Standards Board (CDSB), and by building on the recommendations of the TCFD, the ISSB has begun to provide a coherent set of standards that focus on financially material sustainability information. Companies and investors seeking to understand this evolution can explore how the ISSB positions its standards as a global baseline that jurisdictions can build upon, for example by reviewing the IFRS Foundation's sustainability resources and guidance on sustainability-related financial disclosures.

At the same time, the European Union has advanced its own comprehensive framework through the Corporate Sustainability Reporting Directive (CSRD) and the associated European Sustainability Reporting Standards (ESRS), which are overseen by EFRAG and are designed to reflect the EU's "double materiality" concept, capturing both financial materiality and impacts on people and the environment. Businesses with significant operations in the EU, including many headquartered in the United States, United Kingdom, Switzerland and Asia, now face mandatory and highly granular reporting requirements that go far beyond traditional non-financial reporting, with guidance and technical updates available through the European Commission and EFRAG platforms, where companies can learn more about the ESRS framework and implementation timelines.

Regulatory Drivers Across Key Global Markets

The consolidation of ESG reporting standards is being accelerated not only by standard-setters but also by regulators and market authorities across the world's largest economies, each of which is embedding sustainability reporting into its regulatory architecture, often referencing or aligning with the ISSB, TCFD and EU standards. In the United States, the Securities and Exchange Commission (SEC) has moved forward with climate-related disclosure rules that require listed companies to provide more detailed and consistent information on climate risks, greenhouse gas emissions and governance structures, integrating these disclosures into existing reporting obligations under securities law. Companies can follow developments and interpretive guidance through the SEC's dedicated climate disclosure resources, where they can review the latest climate-related reporting rules and compliance expectations.

In the United Kingdom, the government and the Financial Conduct Authority (FCA) have been among the early adopters of TCFD-aligned reporting requirements, initially targeting premium-listed companies and asset managers and gradually expanding the scope to a broader set of entities, while also engaging with the ISSB's standards as a potential foundation for future mandatory reporting. Businesses operating in London and other UK financial hubs can consult the FCA's sustainability disclosure materials to understand the evolving UK sustainability disclosure regime.

Elsewhere, regulators in jurisdictions such as Canada, Australia, Singapore and Japan have either adopted or strongly encouraged climate-related reporting aligned with the TCFD, while closely monitoring the ISSB's progress. For example, the Monetary Authority of Singapore (MAS) has published extensive guidance on environmental risk management and climate disclosures for financial institutions, emphasizing the importance of consistent, decision-useful data for risk assessment and capital allocation, and market participants can explore MAS guidance on sustainable finance and disclosure expectations. In Asia and Europe, many central banks and supervisors are coordinating through the Network for Greening the Financial System (NGFS), which provides research and recommendations on climate risk and supervision, helping to create a more harmonized approach to climate-related financial disclosure; interested stakeholders can review NGFS publications on climate-related risk management.

For readers of dailybusinesss.com who track global regulatory developments and their impact on trade and markets, these regional moves underscore that ESG reporting is no longer a voluntary or localized exercise but a core element of cross-border regulatory compliance, particularly for multinational companies operating across Europe, North America and Asia-Pacific.

The Role of Capital Markets and Institutional Investors

While regulators provide the legal backbone for ESG reporting, the consolidation of standards is equally driven by the demands of global capital markets and the evolving strategies of large institutional investors, asset managers and lenders. Over the past decade, organizations such as the Principles for Responsible Investment (PRI) and the Glasgow Financial Alliance for Net Zero (GFANZ) have mobilized trillions of dollars of assets under management around the integration of ESG factors into investment decisions, pushing for more consistent, comparable and reliable sustainability data. Investors seeking guidance on how to integrate ESG into investment processes can learn more about responsible investment practices through the PRI's frameworks and case studies.

Major asset managers and pension funds in the United States, United Kingdom, Canada, the Netherlands and Scandinavia now routinely engage with portfolio companies on climate transition plans, board diversity, human capital management and supply chain due diligence, often using consolidated reporting frameworks as the basis for their expectations and stewardship activities. The Task Force on Climate-related Financial Disclosures, hosted by the Financial Stability Board (FSB), has played a pivotal role in shaping investor expectations by providing a widely adopted framework for climate-related governance, strategy, risk management and metrics, and companies can explore the TCFD recommendations and implementation guidance to better understand what investors expect in climate reporting.

Credit rating agencies and ESG ratings providers, although subject to growing scrutiny over methodologies and transparency, have also contributed to the push for standardized reporting by relying more heavily on structured, comparable data rather than self-selected narrative disclosures. As dailybusinesss.com has highlighted in its markets and investment coverage, this shift is influencing credit spreads, equity valuations and capital access for companies across sectors, particularly in carbon-intensive industries such as energy, transportation, heavy manufacturing and real estate, as well as in financial institutions with significant exposure to transition risk.

Data Quality, Assurance and the Trust Imperative

As ESG reporting becomes more standardized and embedded in financial reporting, questions of data quality, assurance and trustworthiness have moved to the forefront. Investors, regulators and other stakeholders increasingly expect ESG data to be subject to rigorous internal controls, independent assurance and board-level oversight, similar to traditional financial information. Leading audit and advisory firms, including PwC, Deloitte, KPMG and EY, have expanded their sustainability assurance offerings, while also contributing to the development of methodologies and best practices. Executives and audit committee members seeking practical guidance can review PwC's perspectives on ESG reporting and assurance to understand emerging expectations.

The International Auditing and Assurance Standards Board (IAASB) has responded by developing standards for sustainability assurance engagements, aiming to provide a consistent global framework for how auditors and assurance providers evaluate ESG information, including climate metrics, social impact indicators and governance disclosures. Companies wishing to understand the assurance landscape can learn more about IAASB's sustainability assurance initiatives and how they intersect with financial audit requirements.

For the readership of dailybusinesss.com, which closely follows investment trends, employment dynamics and the broader economy, this focus on assurance is critical because it underpins the credibility of ESG data that informs investment decisions, executive compensation plans, workforce strategies and public policy debates. Without reliable and comparable data, ESG risks being dismissed as marketing or political rhetoric; with robust assurance and governance, it can become a trusted component of enterprise performance management.

Technology, AI and the Future of ESG Data Management

The consolidation of ESG reporting standards coincides with a rapid acceleration in digital technologies, particularly artificial intelligence, data analytics and automation, which are transforming how companies collect, manage and report sustainability information. In 2026, leading organizations are deploying AI-driven platforms to ingest data from multiple internal systems, such as energy management, HR, procurement and logistics, as well as from external sources including suppliers, satellite imagery and climate models, in order to produce more timely, granular and accurate ESG metrics.

Technology providers and cloud platforms are increasingly embedding ESG capabilities into their enterprise solutions, allowing companies to link sustainability data with financial performance, scenario analysis and risk management. For readers of dailybusinesss.com interested in AI and technology trends, it is evident that ESG reporting is becoming a proving ground for advanced analytics, machine learning and natural language processing, with applications ranging from automated emissions calculation to real-time monitoring of supply chain labor practices.

At the same time, regulators and standard-setters are paying closer attention to the use of AI in ESG reporting, particularly around model transparency, data provenance and the risk of "greenwashing" through overly optimistic scenario modeling or selective disclosure. Organizations such as the World Economic Forum (WEF) are publishing frameworks on responsible AI and digital trust, which intersect with ESG reporting by emphasizing governance, ethics and accountability in data-driven decision-making; business leaders can explore WEF insights on responsible AI and sustainability. As digitalization advances, companies that invest in robust data architecture, cybersecurity and ethical AI practices will be better positioned to meet both ESG reporting requirements and broader stakeholder expectations around digital responsibility.

ESG, Strategy and the Global Competitive Landscape

Consolidation of ESG reporting standards is not only a compliance issue but also a strategic inflection point that is reshaping competitive dynamics across sectors and geographies. Companies that treat ESG reporting as an integrated part of corporate strategy, rather than a separate reporting obligation, are better able to align capital expenditure, innovation, M&A and workforce planning with long-term sustainability trends, including decarbonization, resource efficiency, demographic shifts and social inclusion. For example, in energy-intensive industries, credible transition plans backed by transparent, standardized reporting can influence access to green financing, eligibility for government incentives and partnership opportunities in emerging technologies such as hydrogen, carbon capture and advanced storage, as highlighted in sector analyses by the International Energy Agency (IEA), where stakeholders can review IEA scenarios and sectoral transition pathways.

In the financial sector, banks and asset managers that integrate consolidated ESG data into credit and investment processes can differentiate themselves through more sophisticated risk management and product innovation, from sustainability-linked loans to transition bonds and impact funds. The OECD has documented how sustainable finance is reshaping capital markets and corporate behavior, providing policymakers and market participants with analytical tools to understand trends in green and sustainable finance. For founders and growth-stage companies featured in dailybusinesss.com's founders and startup coverage, alignment with emerging ESG standards can facilitate access to venture capital and private equity funds that have integrated ESG criteria into their investment mandates, particularly in Europe and North America where limited partners increasingly demand robust sustainability practices.

Across global value chains, from manufacturing in Asia to logistics in Europe and retail in North America, standardized ESG reporting is pushing companies to map and monitor their Scope 3 emissions, human rights risks and biodiversity impacts, prompting reconfiguration of supplier relationships and sourcing strategies. Organizations such as the World Business Council for Sustainable Development (WBCSD) are providing platforms for companies to collaborate on sectoral roadmaps and data-sharing initiatives, and business leaders can learn more about collaborative approaches to sustainable value chains. For multinational companies with operations in countries such as China, India, Brazil and South Africa, this evolving landscape requires balancing local regulatory requirements with global investor expectations and emerging international standards.

Crypto, Digital Assets and ESG Transparency

For dailybusinesss.com readers engaged in crypto and digital assets, ESG reporting consolidation has particular resonance. As regulators and investors scrutinize the environmental footprint of blockchain networks, especially energy-intensive proof-of-work systems, standardized reporting on energy usage, emissions intensity and mitigation measures is becoming critical for exchanges, miners, custodians and institutional investors allocating to digital assets. Initiatives such as the Crypto Climate Accord and independent research by organizations like the Cambridge Centre for Alternative Finance have sought to quantify the environmental impact of crypto mining and propose pathways to decarbonization, and market participants can explore research on crypto's energy consumption and transition scenarios.

As traditional financial institutions integrate digital assets into their offerings, they are increasingly expected to apply the same ESG due diligence and reporting standards to crypto exposures as they do to other asset classes, particularly in Europe and North America where sustainable finance regulations are tightening. This means that crypto projects and Web3 companies aiming to attract institutional capital will need to provide more transparent, standardized ESG disclosures, not only on environmental metrics but also on governance structures, consumer protection and financial crime controls. The convergence of ESG reporting and digital asset regulation is likely to become a focal point for policymakers and market participants over the next several years, with implications for innovation, competitiveness and systemic risk.

Employment, Talent and the Social Dimension of ESG

While environmental and climate reporting have dominated the ESG conversation, the consolidation of standards is also bringing greater attention to social and human capital metrics, including workforce diversity, pay equity, labor conditions, health and safety, training and reskilling, and community impact. In 2026, companies across the United States, United Kingdom, Germany, France, Canada, Australia and other advanced economies face intensifying scrutiny from employees, unions, regulators and civil society organizations regarding how they manage people and social risks, particularly in the context of automation, AI adoption and remote work.

Standard-setters and regulators are beginning to codify expectations around social disclosures, drawing on frameworks developed by organizations such as the International Labour Organization (ILO), which provides conventions and guidelines on labor rights, occupational safety and social protection that increasingly inform corporate reporting and due diligence requirements, and businesses can learn more about international labor standards. For dailybusinesss.com readers who monitor employment trends and the future of work, this evolution underscores that ESG consolidation is not limited to carbon and climate metrics but extends to how organizations measure and communicate their impact on workers and communities.

Talent markets, especially in technology, finance and high-growth sectors, are increasingly influenced by perceptions of corporate purpose and ESG performance. Younger professionals in markets such as the Netherlands, Sweden, Norway, Singapore and Japan often weigh a company's sustainability and social credentials when choosing employers, and standardized reporting helps them compare organizations more objectively. Companies that integrate ESG into leadership development, incentive structures and corporate culture are better positioned to attract and retain high-caliber talent, particularly in competitive hubs such as New York, London, Berlin, Toronto, Sydney and Singapore.

Travel, Supply Chains and the Global Footprint

The post-pandemic recovery of international travel, tourism and global supply chains has intersected with ESG reporting consolidation in complex ways. As business travel resumes between regions such as North America, Europe and Asia, companies are under pressure to account for and manage the climate impact of travel, logistics and global operations, often as part of their Scope 3 emissions reporting. Airlines, hospitality companies and travel platforms are increasingly expected to provide transparent emissions data and decarbonization strategies, aligning with emerging reporting standards and climate targets. Organizations such as the International Air Transport Association (IATA) and the World Travel & Tourism Council (WTTC) publish guidance on sustainable aviation and tourism, helping companies and travelers understand pathways to lower-carbon travel.

For supply chains spanning Asia, Europe, Africa and South America, consolidation of ESG reporting standards is pushing companies to demand better data and practices from suppliers, including small and medium-sized enterprises that may lack the resources and expertise to comply with complex reporting expectations. This creates both risks and opportunities: suppliers that invest in sustainability capabilities can become preferred partners for global brands, while those that lag may face exclusion from high-value markets. dailybusinesss.com has observed in its trade and global business coverage that this dynamic is particularly pronounced in sectors such as apparel, electronics, automotive and food, where consumer and regulatory scrutiny of supply chain practices is intense.

The Road Ahead: Convergence with Local Nuance

Looking ahead from 2026, the trajectory of ESG reporting standards suggests continued consolidation around a global baseline, likely anchored by the ISSB standards and TCFD-aligned climate disclosure, with regional frameworks such as the EU's ESRS adding additional layers of detail and impact-focused requirements. The challenge for multinational companies will be to design reporting systems and governance structures that can satisfy multiple regulatory regimes while maintaining coherence and consistency in the story they tell to investors, employees, customers and communities.

For the global audience of dailybusinesss.com, spanning markets from the United States and United Kingdom to Germany, Singapore, Brazil, South Africa and beyond, the key message is that ESG reporting is evolving from a fragmented, voluntary practice into a structured, regulated and technology-enabled discipline that sits at the heart of corporate strategy, risk management and value creation. Executives, founders and investors who treat ESG reporting consolidation as an opportunity to strengthen decision-making, enhance transparency and build trust will be better positioned to navigate the uncertainties of climate transition, digital disruption and geopolitical change.

By integrating insights from finance and markets, technology and AI, sustainability and climate and global economic trends, dailybusinesss.com will continue to track how ESG standards evolve, how regulators and markets respond and how leading organizations translate reporting requirements into resilient, forward-looking strategies. In a world where stakeholders demand not only financial performance but also demonstrable responsibility and integrity, the consolidation of ESG reporting standards is not the end of the journey but the foundation for a new era of accountable, transparent and sustainable business.

Nordic Nations Pioneer the Green Transition

Last updated by Editorial team at dailybusinesss.com on Monday 23 February 2026
Article Image for Nordic Nations Pioneer the Green Transition

Nordic Nations Pioneer the Green Transition

A New Economic Narrative for the 2026 Business Landscape

By early 2026, the Nordic nations-Sweden, Norway, Denmark, Finland, and Iceland-have moved from being regional exemplars of social welfare to global reference points for how advanced economies can execute a green transition while maintaining competitiveness, social cohesion, and technological leadership. For readers of DailyBusinesss.com, whose interests span AI, finance, business, crypto, economics, employment, founders, and global markets, the Nordic experience offers an increasingly relevant blueprint for how sustainability can become a core driver of long-term value creation rather than a compliance burden or marketing exercise.

The Nordic story matters far beyond Scandinavia. As governments in the United States, United Kingdom, Germany, Canada, Australia, and across Europe, Asia, Africa, and the Americas struggle to reconcile climate commitments with growth and fiscal stability, the Nordic countries are demonstrating that ambitious climate policy, digital transformation, and social trust can be mutually reinforcing. Their progress is not flawless, and their models cannot be transplanted wholesale into vastly different political or demographic contexts, but their experience provides data-rich evidence that decarbonization can be integrated into the core architecture of modern capitalism. For executives, investors, founders, and policymakers following global developments through the world and economics coverage at DailyBusinesss.com, the Nordic trajectory is increasingly a strategic rather than merely academic concern.

From Environmentalism to Economic Strategy

The green transition in the Nordic region did not emerge overnight; it has evolved over decades from environmental protection into a broad economic strategy. Early investments in clean energy, public transport, and environmental regulation in the late twentieth century laid the groundwork for a more systemic shift in the 2000s and 2010s, when climate change moved from a niche concern to a central pillar of national competitiveness. Today, Nordic governments align industrial policy, taxation, innovation funding, and labor market frameworks around the objective of building climate-neutral, resilient, and inclusive economies.

According to the Nordic Council of Ministers, the region has committed to becoming the world's most sustainable and integrated region, with targets that go beyond the climate ambitions of many larger economies. Readers can explore how these ambitions translate into concrete policies by consulting global overviews of climate targets and progress such as those provided by UN Climate Change and the OECD. What distinguishes the Nordic approach, however, is less the headline ambition and more the integration of environmental goals into mainstream economic decision-making, from corporate governance and tax design to infrastructure planning and digital regulation.

For business leaders following business and markets developments at DailyBusinesss.com, this integration is crucial, because it influences everything from the cost of capital and regulatory risk to consumer expectations and talent attraction. The Nordic region has effectively turned sustainability into a strategic narrative that shapes investment flows, corporate strategies, and cross-border trade, rather than treating it as an afterthought or public relations exercise.

Energy Systems as the Backbone of the Green Transition

The most visible pillar of the Nordic green transition is the transformation of energy systems. Norway derives the vast majority of its electricity from hydropower, Iceland from geothermal and hydro, while Sweden, Denmark, and Finland combine hydro, wind, biomass, nuclear, and increasingly solar to achieve some of the cleanest power mixes in the industrialized world. This low-carbon electricity base is not just an environmental asset; it is an economic foundation for energy-intensive industries, digital infrastructure, and data-driven services.

The International Energy Agency provides detailed assessments of Nordic energy policies and performance, and its analysis underscores that the region has managed to combine high levels of electrification with relatively stable energy prices and high reliability. Learn more about the evolution of clean energy systems and their economic impact through resources such as the IEA and the International Renewable Energy Agency. For global investors and multinational corporations, the Nordic energy profile is increasingly a factor in location decisions for data centers, advanced manufacturing, and green hydrogen projects.

At the same time, the region faces new challenges as it deepens electrification across transport, industry, and buildings. Grid expansion, cross-border interconnectors, and digital management of flexible demand are becoming central issues, particularly as intermittent wind and solar expand. Nordic utilities and technology firms are investing heavily in smart grids, demand-response technologies, and AI-driven forecasting tools, creating opportunities for collaboration with global tech players and startups. Readers following the intersection of energy and digital innovation on the tech and technology sections of DailyBusinesss.com will recognize that the Nordic region is emerging as a testbed for how advanced electricity systems can be managed in real time through data and automation.

AI, Digitalization, and the Green Transition

Artificial intelligence and digitalization are now core enablers of the Nordic green transition rather than separate policy domains. Nordic governments and companies are deploying AI to optimize energy usage in buildings, forecast electricity production, manage logistics networks, and reduce industrial waste, thereby turning digital innovation into a direct lever for emissions reduction and cost savings. This convergence is particularly visible in Finland and Sweden, where AI-driven solutions are being integrated into manufacturing, forestry, and logistics, and in Denmark, where AI supports the integration of large-scale offshore wind into the grid.

Organizations such as AI Sweden and Finland's VTT Technical Research Centre have become hubs for applied AI research, often with a strong focus on climate and resource efficiency. Global readers can explore broader perspectives on responsible AI and its role in sustainable development through resources such as the World Economic Forum and the OECD AI Observatory. For DailyBusinesss.com's audience tracking AI and digital transformation, the Nordic region demonstrates how data governance, ethical frameworks, and public-private collaboration can accelerate green use cases while maintaining high levels of public trust.

Crucially, Nordic digital policy emphasizes both innovation and privacy. Strong data protection regimes, high levels of digital literacy, and robust public digital infrastructure-including e-ID systems and interoperable public databases-create a trusted environment in which AI can be deployed at scale in sensitive sectors such as energy, transport, and healthcare. This combination of digital maturity and social trust is difficult to replicate but provides a useful benchmark for policymakers in regions such as North America, Asia, and Europe who are seeking to harness AI for climate goals without triggering backlash or undermining civil liberties.

Finance, Green Investment, and Sustainable Markets

The Nordic green transition is also a financial story. Regional banks, pension funds, and asset managers have been early adopters of environmental, social, and governance (ESG) integration, and Nordic stock exchanges have become important venues for listing green bonds, renewable energy companies, and climate-focused technology firms. The Nordic Investment Bank has played a catalytic role in financing sustainable infrastructure and innovation across member countries, illustrating how public financial institutions can crowd in private capital.

For readers engaging with finance and investment themes on DailyBusinesss.com, the Nordic experience shows how regulatory alignment, investor expectations, and clear taxonomies can accelerate capital flows into low-carbon assets. Frameworks such as the EU Taxonomy for Sustainable Activities and disclosure standards shaped by bodies like the International Sustainability Standards Board are widely applied in the region, creating a relatively coherent environment for green finance compared with many other jurisdictions. Readers can deepen their understanding of these frameworks through organizations such as the European Commission and the IFRS Foundation.

At the same time, Nordic financial institutions are facing increased scrutiny regarding the credibility of their net-zero commitments and the extent of their exposure to high-emission sectors, both domestically and abroad. Regulators and civil society organizations are pressing banks and asset managers to move from portfolio-level targets to more granular, time-bound decarbonization plans, while investors are demanding higher quality climate risk disclosure. International guidance from bodies such as the Network for Greening the Financial System and the Task Force on Climate-related Financial Disclosures continues to shape Nordic financial regulation and corporate practice, reinforcing the broader trend toward climate-aligned capital markets.

Industrial Transformation and New Green Value Chains

The Nordic green transition is not limited to services and finance; it is reshaping heavy industry and manufacturing. In Sweden, projects such as HYBRIT and H2 Green Steel are pioneering fossil-free steel production using green hydrogen, aiming to decarbonize one of the world's most emission-intensive sectors while capturing a premium market for low-carbon materials in Germany, France, Italy, and beyond. In Finland, bio-based materials and circular economy solutions are emerging from the traditional forestry sector, with companies exploring advanced biochemicals, sustainable packaging, and fiber-based textiles.

The European Environment Agency has highlighted Nordic progress in circular economy policies, including extended producer responsibility schemes, advanced waste management, and high rates of recycling and reuse. Learn more about evolving circular economy frameworks and their implications for business through resources such as the EEA and the Ellen MacArthur Foundation. For global manufacturers and supply chain leaders, these developments signal that future competitiveness may depend on integrating circularity into core product design, procurement, and logistics strategies rather than treating it as a peripheral sustainability initiative.

Nordic companies are also deeply embedded in global clean tech supply chains, from wind turbine manufacturing and grid technologies to battery materials and electric vehicle components. Denmark's wind sector, anchored by companies such as Vestas and Ørsted, has long been a global leader, while Norway has leveraged its maritime expertise to develop low-emission shipping solutions and offshore energy technologies. As major economies such as China, Japan, South Korea, and the United States expand their own green industrial policies, Nordic firms are increasingly positioned as partners, suppliers, and technology providers in a competitive but rapidly growing global market.

Employment, Skills, and the Just Transition

One of the most persistent concerns about the green transition is its impact on employment, social equity, and regional cohesion. The Nordic countries address this challenge through active labor market policies, robust social safety nets, and strong tripartite cooperation between governments, employers, and trade unions. This model aims to ensure that workers in declining sectors receive support for retraining and that new green jobs are of high quality, with decent wages and working conditions.

International organizations such as the International Labour Organization and the World Bank have highlighted the importance of such "just transition" frameworks for maintaining social legitimacy during structural change. The Nordic experience, which readers can relate to broader employment trends via DailyBusinesss.com's employment coverage, suggests that well-designed labor institutions can mitigate the social costs of decarbonization and even transform it into an opportunity for upgrading skills and productivity.

However, challenges remain. Some regions dependent on fossil-fuel related industries, particularly in Norway's oil and gas sector, face complex transitions as global demand patterns shift. While many skills are transferable to offshore wind, carbon capture, and other low-carbon industries, not all jobs can be seamlessly replaced. Maintaining public support for ambitious climate policies will require continued investment in education, vocational training, and regional development, along with transparent communication about the pace and direction of change.

Founders, Startups, and Climate-Tech Innovation

The Nordic region has developed a vibrant startup ecosystem with a strong orientation toward climate-tech, fintech, and digital solutions that enable sustainability across sectors. Cities such as Stockholm, Copenhagen, Helsinki, and Oslo are home to founders building companies that address renewable energy integration, carbon accounting, sustainable mobility, and resource efficiency, often leveraging AI and data analytics. This ecosystem benefits from high levels of digital infrastructure, supportive public funding, and a culture that values both innovation and social responsibility.

For readers interested in entrepreneurial dynamics and founder stories, DailyBusinesss.com's founders section provides a lens through which to view how Nordic startups are scaling globally while retaining a clear climate mission. Many of these ventures are backed by a mix of local venture capital, government innovation agencies, and increasingly, international investors seeking exposure to climate-aligned technologies. Global accelerators and corporate innovation programs are also establishing partnerships in the region, recognizing its potential as a laboratory for scalable green solutions.

Internationally, reports from organizations such as PwC and BloombergNEF have documented the rapid growth of climate-tech investment worldwide, with the Nordics punching above their weight in terms of per-capita startup formation and funding. The region's challenge over the coming years will be to ensure that promising ventures can scale beyond national and regional markets, navigating complex regulatory environments in North America, Asia, and emerging markets in Africa and South America while maintaining their sustainability credentials.

Crypto, Digital Assets, and Sustainability Concerns

The rapid expansion of cryptocurrencies and digital assets has raised questions about energy consumption and environmental impact, particularly in the context of proof-of-work mining. Nordic countries, with their abundant low-carbon electricity and cool climates, became attractive locations for crypto mining operations in the late 2010s and early 2020s. However, as awareness of the environmental implications grew, policymakers and utilities in Sweden and Norway began to question whether allocating clean electricity to energy-intensive mining was compatible with broader climate and industrial objectives.

For readers tracking the intersection of crypto, digital finance, and sustainability at DailyBusinesss.com, the Nordic response is instructive. Authorities have signaled a preference for channeling clean power into activities that support long-term industrial decarbonization, digital infrastructure, and electrification of transport, rather than speculative mining. At the same time, Nordic financial regulators are engaging with the broader evolution of digital assets, including central bank digital currencies and tokenized green assets, in coordination with bodies such as the Bank for International Settlements and the European Central Bank.

This nuanced stance reflects a broader principle of strategic resource allocation: in a world where low-carbon electricity and grid capacity are valuable assets, governments and regulators must decide which sectors and technologies receive priority access. The Nordic debate about crypto mining is therefore a microcosm of a larger global conversation about how digital innovation, financial experimentation, and sustainability can be aligned rather than placed in tension.

Trade, Global Value Chains, and Regulatory Influence

Nordic economies are deeply integrated into global trade and value chains, exporting advanced manufacturing, maritime services, renewable energy technologies, and digital solutions to markets across Europe, Asia, North America, and beyond. As the green transition accelerates, trade policy and international regulatory frameworks are becoming critical levers for shaping the competitive landscape. Nordic governments, often working through the European Union, are active participants in debates on carbon border adjustment mechanisms, sustainable trade rules, and green industrial subsidies.

For business leaders and policymakers following trade and global news on DailyBusinesss.com, it is increasingly important to understand how Nordic positions within the EU and international forums may influence global standards. Resources such as the World Trade Organization and the International Chamber of Commerce provide insight into evolving trade rules related to environmental goods, services, and subsidies, while Nordic contributions often emphasize the need to balance climate ambition with open, rules-based trade.

Nordic companies, for their part, must navigate both opportunities and risks associated with this evolving landscape. On the one hand, strong domestic sustainability standards can create a competitive advantage in markets where customers value low-carbon and ethically produced goods. On the other hand, compliance with multiple overlapping regulatory regimes-from EU green taxonomies to national disclosure rules in Canada, Japan, or Singapore-can increase complexity and cost. Strategic engagement with regulators, industry associations, and international standard-setting bodies will therefore remain a priority for Nordic multinationals and their global partners.

Travel, Cities, and Sustainable Lifestyles

The green transition is also reshaping everyday life in Nordic cities and regions, with implications for travel, tourism, and urban development. Cities such as Copenhagen, Stockholm, and Oslo have invested heavily in cycling infrastructure, public transport, and low-emission zones, aiming to reduce car dependency and air pollution while enhancing quality of life. These urban strategies make the region a living laboratory for sustainable mobility and urban planning, attracting attention from city planners and investors worldwide.

For readers interested in how travel and tourism intersect with sustainability, the travel coverage at DailyBusinesss.com can be enriched by examining Nordic initiatives that promote low-carbon tourism, nature-based experiences, and off-season travel to reduce pressure on fragile ecosystems. Organizations such as the World Travel & Tourism Council and the UN World Tourism Organization offer global perspectives on how destinations can align tourism growth with environmental stewardship, and the Nordic region is often cited as a leading example.

Sustainable lifestyles in the Nordics also extend to building standards, food systems, and consumer behavior. High levels of public awareness, combined with relatively high incomes and strong public services, enable widespread adoption of energy-efficient homes, plant-forward diets, and circular consumption models such as repair, reuse, and sharing. While such patterns cannot be replicated identically in all contexts, they provide a reference point for how policy, infrastructure, and culture can reinforce each other to shift demand in a more sustainable direction.

Lessons and Strategic Implications for a Global Business Audience

As the green transition moves from aspiration to implementation in 2026, the Nordic experience offers several lessons for global business and policy leaders who follow the evolving landscape through DailyBusinesss.com's coverage of sustainable business, economics, and world developments. First, the region demonstrates that long-term policy consistency and cross-party consensus on climate goals can create a stable environment for investment and innovation, reducing regulatory risk and enabling companies to plan beyond electoral cycles. Second, it shows that integrating digitalization and AI into climate strategy can unlock efficiencies and new business models, provided that data governance and ethical frameworks maintain public trust.

Third, the Nordic model underscores the importance of aligning financial systems with sustainability objectives through clear taxonomies, disclosure standards, and public financial institutions that can de-risk early-stage investments. Fourth, it highlights that a just transition-supported by active labor market policies, social safety nets, and social dialogue-is not only a moral imperative but also a practical necessity for maintaining political support and social stability during structural change. Finally, it illustrates that small, open economies can exert outsized influence on global standards and markets when they combine ambitious domestic policies with active engagement in international forums.

For executives, investors, and founders in North America, Europe, Asia, Africa, and South America, the strategic question is not whether the Nordic model can be copied wholesale, but which elements can be adapted to their own institutional, cultural, and economic contexts. As climate risks intensify, regulatory expectations tighten, and technological change accelerates, the ability to integrate sustainability into core strategy will increasingly differentiate resilient, future-ready organizations from those that struggle to adapt. In that sense, the Nordic nations are not simply regional outliers; they are early indicators of a broader transformation in how advanced economies conceive of prosperity, competitiveness, and responsibility in the twenty-first century.

The Blurring Lines Between Tech and Finance

Last updated by Editorial team at dailybusinesss.com on Monday 23 February 2026
Article Image for The Blurring Lines Between Tech and Finance

The Blurring Lines Between Tech and Finance

A New Operating System for Global Capital

By 2026, the convergence of technology and finance has moved far beyond the well-worn label of "fintech" and has instead become a structural transformation of how capital, data and trust flow through the global economy. What once looked like a series of disruptive startups nibbling at the edges of banking has matured into a new operating system for financial services, in which software is not simply a tool layered on top of money but the primary infrastructure through which value is created, priced, transferred and governed. For readers of DailyBusinesss who track developments across AI, finance, markets, crypto and technology, this blurring of lines is no longer an abstract trend; it is a daily business reality reshaping strategy, regulation, employment and competition in every major region of the world.

The shift is visible from Wall Street to Silicon Valley, from London and Frankfurt to Singapore and Shanghai, and across emerging financial hubs in Africa, South America and Southeast Asia, where mobile-native consumers have leapfrogged traditional banking infrastructures. The fusion of code and capital is redefining what it means to be a financial institution, a technology company, a regulator and even a customer, as individuals and enterprises increasingly interact with money through digital interfaces, algorithmic decisions and real-time data streams rather than paper contracts or branch networks.

From Fintech Niche to Tech-Fin Mainstream

The first wave of fintech in the 2010s and early 2020s was often framed as a challenge to incumbent banks, but the narrative has shifted as the world approaches the middle of the decade. Rather than a binary contest, the more accurate description is a progressive merging of capabilities, cultures and business models between technology platforms and financial institutions. Large banks such as JPMorgan Chase, HSBC, BNP Paribas and Deutsche Bank have evolved into software-centric organizations, investing heavily in cloud, data analytics and AI, while major technology players such as Apple, Alphabet, Amazon, Tencent and Alibaba have embedded payments, lending and wealth tools into their ecosystems.

This evolution has produced a "tech-fin" landscape in which financial services are increasingly embedded into non-financial customer journeys. Consumers in the United States, United Kingdom, Germany, Canada, Australia, France, Italy, Spain, Netherlands and Switzerland now routinely experience credit, insurance and investment offerings at the point of purchase on e-commerce sites, ride-hailing apps and travel platforms. In rapidly digitizing markets such as China, Singapore, South Korea, Japan, Thailand, Malaysia, Brazil, South Africa and across Europe, Asia and Africa, super-app ecosystems have shown how payments, micro-investments and lending can be woven seamlessly into daily life. As central banks and policymakers monitor these developments through organizations such as the Bank for International Settlements and the International Monetary Fund, the strategic question is no longer whether technology will transform finance, but who will control the resulting data, standards and value chains.

AI as the New Financial Intelligence Layer

Artificial intelligence has become the critical intelligence layer that binds technology and finance into a single system. What began as algorithmic trading and rudimentary robo-advisory has expanded into pervasive AI-driven decision-making across lending, risk management, fraud detection, compliance, portfolio construction and customer engagement. Financial institutions now deploy advanced machine learning models to evaluate creditworthiness using hundreds of variables beyond traditional credit scores, to price complex derivatives in volatile markets and to detect anomalous transactions in real time, thereby reinforcing the integrity of the global payments and capital markets infrastructure.

Research from organizations such as the World Economic Forum and the OECD has highlighted how AI is reshaping financial inclusion, market efficiency and systemic risk, while regulators in the European Union, United States, United Kingdom, Singapore and Japan refine AI governance frameworks. At the same time, the democratization of AI tools has enabled smaller firms, family offices and even sophisticated retail investors to access analytics capabilities once reserved for global investment banks and hedge funds, with platforms offering algorithmic backtesting, sentiment analysis and portfolio optimization. Readers of DailyBusinesss following developments in AI and markets can see how this diffusion of capability is intensifying competition while also raising questions about model transparency, bias, explainability and accountability.

Embedded Finance and the Rise of Invisible Banking

One of the clearest manifestations of the tech-finance merger is the rise of embedded finance, in which financial products are integrated directly into non-financial platforms. Instead of a consumer visiting a bank to request a loan, the loan is offered at checkout; instead of a small business owner negotiating with a bank for working capital, financing is dynamically provided based on real-time sales data from an e-commerce or point-of-sale system. This "invisible banking" model has been popularized by technology providers such as Stripe, Adyen, Block (Square) and Shopify, which offer payment and financing rails to merchants and platforms across North America, Europe, Asia-Pacific and beyond.

The embedded model alters the economics of financial services by shifting distribution power toward platforms that own customer relationships and data. It also changes risk profiles, as non-financial companies take on quasi-financial roles while partnering with licensed banks in the background. As regulators from the European Central Bank to the U.S. Federal Reserve examine these developments, they are grappling with how to ensure consumer protection, financial stability and fair competition in a landscape where the line between bank, fintech and platform is increasingly blurred. For business leaders and founders navigating this environment, the strategic imperative is to understand how embedded finance can enhance customer experience and revenue while managing compliance and operational complexity, a theme regularly explored in DailyBusinesss coverage of business strategy and innovation.

Digital Assets, Tokenization and the Evolving Crypto Ecosystem

While early cycles of cryptocurrency enthusiasm were marked by volatility and speculation, by 2026 the digital asset ecosystem has matured into a more regulated and institutionally integrated component of global finance. Stablecoins, central bank digital currencies (CBDCs) and tokenized real-world assets now sit alongside more speculative tokens in a diverse landscape of blockchain-based instruments. Major financial institutions such as BlackRock, Fidelity, Goldman Sachs and UBS have launched or expanded digital asset divisions, offering custody, trading and tokenization services to institutional and high-net-worth clients, while exchanges and custodians are governed by more stringent licensing regimes in jurisdictions such as Singapore, Switzerland, United Arab Emirates, United States and United Kingdom.

The tokenization of assets, from real estate and infrastructure to carbon credits and private equity, promises to increase liquidity, transparency and access to previously illiquid markets, with organizations such as the World Bank and the International Finance Corporation exploring how these technologies could support development finance and sustainable investment. For readers tracking crypto and digital asset trends, the key story is not only price movements but the integration of blockchain infrastructure into mainstream settlement, collateral and identity systems, as well as the emergence of cross-border regulatory cooperation to manage risks related to money laundering, sanctions evasion and consumer harm.

Regulation, Trust and the New Architecture of Oversight

As technology and finance converge, the architecture of regulation is undergoing its own transformation. Supervisory authorities are adopting "suptech" tools that leverage data analytics, AI and real-time reporting to monitor financial institutions and markets more effectively. At the same time, regulatory sandboxes and innovation hubs in countries such as Singapore, United Kingdom, Australia, Canada, France, Germany, Japan and Brazil are enabling controlled experimentation with new products, from digital identity systems to programmable money.

The challenge for policymakers is to balance innovation with resilience, especially as systemic risks can now emerge from technology failures, cyberattacks or algorithmic feedback loops as much as from traditional credit or liquidity shocks. Institutions such as the Financial Stability Board and the Basel Committee on Banking Supervision are increasingly focused on operational resilience, third-party risk and cloud concentration, recognizing that a small number of hyperscale cloud providers and core technology vendors underpin a growing share of the financial system. For global business readers, trust in this evolving infrastructure is not a given; it must be earned through transparent governance, robust cybersecurity, clear accountability and credible enforcement, all of which are central to the editorial lens of DailyBusinesss on world and regulatory developments.

Data, Privacy and the Competition for Financial Identity

Data has become the most valuable asset in the tech-finance convergence, and the battle for control of financial identity is intensifying. Open banking and open finance regimes in Europe, United Kingdom, Australia, Brazil and other jurisdictions have mandated that banks share customer data with licensed third parties at the customer's request, enabling new services in payments, personal finance management and lending. As these frameworks expand into pensions, insurance and investments, they are creating a more interoperable financial data ecosystem that supports competition and innovation.

However, this greater data fluidity also heightens concerns about privacy, security and concentration of power. Global norms such as the EU's General Data Protection Regulation and evolving privacy laws in California, Canada, Japan, South Korea and Singapore are shaping how financial data can be collected, processed and shared. At the same time, large technology companies with extensive behavioral data are in a position to build highly granular financial profiles, raising antitrust and fairness questions. For executives and founders exploring opportunities in this space, a sophisticated understanding of data governance, consent management and ethical AI is becoming as critical as product design or capital allocation, a reality frequently examined in DailyBusinesss coverage of technology and regulation.

Employment, Skills and the Future of Financial Work

The fusion of technology and finance is reshaping employment patterns, career paths and skills requirements across global markets. Traditional roles in branch banking, back-office processing and manual compliance are declining, while demand is rising for data scientists, AI engineers, cybersecurity specialists, cloud architects, product managers and behavioral economists who can design digital-first financial experiences. In United States, United Kingdom, Germany, India, Singapore and Australia, leading banks and asset managers are competing directly with technology firms for top talent, offering hybrid work models, innovation labs and internal upskilling programs.

Studies from organizations such as the International Labour Organization and the McKinsey Global Institute have highlighted both the displacement risks and the new opportunities created by automation and digitization in finance. For professionals and graduates entering the field, career resilience now depends on a blend of technical literacy, domain expertise, regulatory awareness and human-centric skills such as judgment, communication and ethical reasoning. Readers of DailyBusinesss who follow employment and future-of-work trends are increasingly aware that financial careers no longer follow linear trajectories; instead, they require continuous learning and the ability to navigate between technology and business domains.

Founders, Capital and the Global Innovation Map

The blurring of tech and finance has also reconfigured the startup and venture capital landscape. Fintech founders are no longer limited to payments and neobanking; they now operate across infrastructure, compliance automation, climate finance, AI-driven underwriting, tokenization platforms and cross-border trade finance. Venture and growth investors in North America, Europe, Asia and Middle East are allocating capital to companies that sit at the intersection of software, data and regulated financial activity, often requiring deeper regulatory and risk expertise than in previous startup cycles.

At the same time, corporate venture arms of major banks, insurers and technology companies are partnering with or acquiring innovative startups to accelerate digital transformation and defend market share. Ecosystems in London, New York, San Francisco, Toronto, Berlin, Paris, Amsterdam, Zurich, Singapore, Hong Kong, Seoul, Tokyo, Sydney, São Paulo, Cape Town and Dubai have emerged as important nodes in this global innovation network, supported by accelerators, regulatory sandboxes and academic research centers. For founders and investors who look to DailyBusinesss for insights on founder journeys and investment strategy and capital allocation, the central question is how to build defensible, compliant and scalable businesses in an environment where regulatory expectations, technology standards and customer behaviors are evolving rapidly.

Sustainable Finance, Climate Risk and Tech-Enabled Stewardship

Sustainability has become another powerful axis along which technology and finance intersect. The integration of environmental, social and governance (ESG) considerations into investment and lending decisions has accelerated, driven by investor demand, regulatory requirements and the growing financial materiality of climate risk. Technology is playing a critical role in measuring, reporting and managing these risks, with platforms that aggregate emissions data, model climate scenarios, track supply chain performance and verify sustainability claims.

Organizations such as the Task Force on Climate-related Financial Disclosures and the International Sustainability Standards Board have advanced global standards for climate and sustainability reporting, while supervisory authorities in Europe, United States, United Kingdom, Japan and other regions integrate climate risk into stress testing and prudential oversight. For businesses and investors, the ability to harness data and analytics to align capital with sustainable outcomes is becoming a core competence rather than a niche specialty. Readers of DailyBusinesss who follow sustainable business and finance themes recognize that climate and nature-related risks are now central to valuation, creditworthiness and strategic planning, and that technology-enabled transparency is redefining what constitutes credible stewardship.

Global Trade, Travel and the Financial Infrastructure of Movement

The post-pandemic recovery in global trade and travel has highlighted how deeply financial and technological infrastructures are intertwined with the movement of goods, services and people. Digital trade finance platforms, real-time cross-border payment systems and blockchain-based supply chain solutions are reducing friction in international commerce, enabling small and medium-sized enterprises in Asia, Africa, South America and Eastern Europe to participate more fully in global markets. At the same time, travel and hospitality companies are leveraging embedded payments, dynamic pricing and personalized financial offers to enhance customer experience and revenue.

Initiatives such as the G20's work on cross-border payments and regional projects in Europe, ASEAN and Africa aim to improve interoperability, reduce costs and increase transparency in international transactions, recognizing that efficient financial rails are essential for inclusive trade and growth. For executives and policymakers who monitor trade and travel dynamics and global business trends through DailyBusinesss, the key insight is that competitive advantage increasingly depends on the ability to integrate financial technology into logistics, procurement, customer engagement and risk management.

Strategic Imperatives for Leaders in a Converged World

As the boundaries between technology and finance continue to dissolve, leaders across industries face a set of strategic imperatives that cut across geography and sector. First, they must recognize that financial capability is no longer confined to banks or specialized institutions; any organization with a strong digital interface and data capability can, in principle, become a financial services distributor or even a quasi-financial institution. Second, they must invest in robust governance, risk and compliance frameworks that are adapted to a world in which technology decisions are also financial stability decisions, and in which regulators are increasingly sophisticated in their use of data and analytics.

Third, they must cultivate talent and culture that can bridge the languages of code, capital and regulation, fostering collaboration between technologists, financiers, lawyers and risk professionals. Fourth, they must engage proactively with policymakers, industry bodies and standard-setters to help shape the evolving rules of the game, rather than treating regulation as an after-the-fact constraint. Finally, they must build trust through transparency, security and a clear articulation of how data is used, how AI systems make decisions and how customers are protected in an increasingly digital and interconnected financial ecosystem.

For the global audience of DailyBusinesss, spanning North America, Europe, Asia-Pacific, Africa and South America, the blurring of lines between tech and finance is not a temporary disruption but a structural realignment that will define the next decade of competition, innovation and policy. By following in-depth analysis across finance and markets, technology and AI, economics and policy and breaking business news, decision-makers can better anticipate the opportunities and risks of this new era, positioning their organizations not merely to adapt to the changing landscape, but to help design the financial and technological architecture of the future.

Employee Ownership Models Gain Traction

Last updated by Editorial team at dailybusinesss.com on Monday 23 February 2026
Article Image for Employee Ownership Models Gain Traction

Employee Ownership Models Gain Traction in the Post-2025 Global Economy

A Quiet Revolution in Corporate Ownership

By early 2026, employee ownership has moved from the fringes of corporate experimentation to the center of strategic conversations in boardrooms from New York to Singapore. Across sectors as diverse as technology, manufacturing, professional services and retail, leaders are reassessing traditional shareholder primacy and exploring models that give employees a direct stake in the enterprises they help to build. For the audience of DailyBusinesss.com, whose interests span AI, finance, entrepreneurship, global markets and the future of work, this shift is not a passing trend but a structural evolution that is reshaping incentives, governance and long-term value creation.

The renewed attention to employee ownership is not occurring in a vacuum; it is a response to converging pressures that have defined the 2020s: widening wealth inequality, persistent talent shortages in high-skill sectors, geopolitical and supply chain volatility, and the accelerating impact of automation and artificial intelligence on traditional employment structures. As investors, founders and policymakers search for models that can reconcile productivity, resilience and social legitimacy, employee ownership has emerged as a credible, data-backed and increasingly global answer. Learn more about how this intersects with broader business model innovation themes explored regularly on DailyBusinesss.com.

Defining the New Landscape of Employee Ownership

Employee ownership is not a single structure but a spectrum of models that transfer economic and sometimes governance rights to workers. In the United States, the most established form is the Employee Stock Ownership Plan, or ESOP, a tax-advantaged vehicle that allows employees to accumulate shares over time. The National Center for Employee Ownership explains how ESOPs have grown into a significant part of the U.S. corporate landscape, with thousands of companies and millions of employees participating; readers can explore the mechanics and performance data through resources on employee ownership research.

Beyond ESOPs, equity compensation in the form of stock options, restricted stock units and performance shares has become standard in technology and high-growth sectors, particularly in hubs such as the United States, United Kingdom, Germany, Canada, Australia and Singapore. In Europe, worker co-operatives and employee ownership trusts have gained prominence, with the UK Employee Ownership Association highlighting the success of companies that transition to employee ownership trusts as part of long-term succession planning. For a broader macroeconomic context on how these models intersect with productivity and income distribution, readers can connect this discussion with the economic analysis available on the DailyBusinesss.com economics section.

In parallel, platform-based and gig-economy businesses are experimenting with tokenized or digital forms of ownership, particularly in crypto-native communities and decentralized autonomous organizations. While regulatory frameworks remain fluid, especially in Europe and Asia, these experiments have intensified discussions on how ownership can be embedded from the outset in new forms of digital enterprises. The Organisation for Economic Co-operation and Development (OECD) has followed these developments closely, and its reports on inclusive growth and corporate governance provide a useful reference point for understanding how employee ownership fits within global policy debates; readers can explore OECD corporate governance resources.

The Economic Case: Productivity, Resilience and Long-Term Value

The resurgence of interest in employee ownership since 2020 has been driven as much by hard data as by ideology. Multiple studies in the United States, United Kingdom and continental Europe have found that companies with broad-based employee ownership often demonstrate higher productivity, lower turnover and greater resilience during economic shocks. The Rutgers Institute for the Study of Employee Ownership and Profit Sharing has documented performance advantages of employee-owned firms, particularly in their ability to maintain employment and investment during downturns; interested readers can review recent findings on performance and resilience.

From a financial perspective, employee ownership can align incentives across stakeholders by linking compensation to long-term enterprise value rather than short-term metrics. For investors, this alignment is increasingly important in a world where intangible assets, human capital and intellectual property drive a growing share of market capitalization. The Harvard Business Review has published several analyses demonstrating how ownership culture contributes to innovation and customer satisfaction, reinforcing the view that employee equity is not merely a benefit but a strategic asset; more detail can be found in their coverage of high-performance organizational cultures.

In markets such as the United States, United Kingdom, Canada and Australia, tax incentives have played a critical role in making employee ownership financially attractive to both founders and employees. The U.S. Internal Revenue Service (IRS) provides guidance on favorable tax treatment for ESOPs, while the UK HM Revenue & Customs (HMRC) outlines similar incentives for employee ownership trusts and share schemes. Readers who follow developments in corporate taxation and capital markets on DailyBusinesss.com's finance and markets sections will recognize how these regulatory frameworks influence capital allocation decisions and exit planning.

Talent, AI and the Future of Work

Nowhere is the strategic logic of employee ownership more evident than in the war for talent, particularly in AI, advanced analytics, cybersecurity and deep tech. As companies in the United States, Europe and Asia race to build AI-enabled products and services, they face intense competition for scarce skills. Salary alone is no longer sufficient to attract and retain top engineers, data scientists and product leaders. Equity participation, especially in early-stage and growth-stage companies, has become a core component of total compensation and a signal of serious intent to share upside.

In this context, employee ownership intersects directly with the themes explored in the DailyBusinesss.com AI coverage, where readers will recognize how rapidly advancing AI capabilities are changing both job design and organizational structures. As automation takes over routine tasks in sectors from manufacturing to financial services, ownership becomes one of the mechanisms through which the economic gains of productivity improvements can be distributed more broadly. The World Economic Forum has repeatedly emphasized in its Future of Jobs reports that inclusive models of value sharing will be essential to maintaining social stability in the face of automation; readers can explore the Future of Jobs insights.

For global employers, particularly in technology hubs such as Silicon Valley, London, Berlin, Toronto, Singapore and Seoul, the ability to offer meaningful equity stakes can differentiate them in competitive labor markets. This is especially true as remote and hybrid work arrangements expand the geographic reach of recruitment, enabling skilled professionals in countries such as India, Brazil, South Africa and Malaysia to participate in equity programs of companies headquartered elsewhere. The International Labour Organization (ILO) has noted that such cross-border arrangements raise new questions around labor rights and social protection, but also create opportunities for more inclusive wealth creation; its analysis of changing employment relationships is highly relevant to these developments.

Founders, Succession and the Mid-Market Opportunity

For founders and privately held mid-market companies, employee ownership is increasingly viewed as a pragmatic succession and liquidity strategy rather than a purely ideological choice. Owners who have built businesses over decades in sectors such as manufacturing, professional services, logistics and retail are often reluctant to sell to private equity buyers or strategic acquirers that may dismantle their culture or relocate operations. Transitioning to an employee ownership trust, ESOP or co-operative structure allows them to crystallize value while preserving the company's identity and local employment footprint.

This trend has been particularly visible in the United Kingdom, where the Employee Ownership Association reports a steady increase in businesses converting to employee ownership trusts, and in the United States, where ESOP conversions are becoming a mainstream alternative to trade sales. For readers of the founders section of DailyBusinesss.com, these transitions illustrate how ownership design is now central to entrepreneurial strategy, not just a legal or tax afterthought. The Kauffman Foundation, a leading voice on entrepreneurship, has highlighted how employee ownership can support business continuity and community stability when founders retire; further discussion is available in its research on entrepreneurship and economic development.

In continental Europe, especially in Germany, France, Italy, Spain and the Netherlands, medium-sized "Mittelstand" and family-owned companies are also exploring hybrid models that combine family control with broader employee shareholding. These structures can reinforce long-termism, which is already a hallmark of many European industrial champions, by embedding employee voice into governance while preserving strategic coherence. As demographic shifts accelerate and a wave of baby-boomer entrepreneurs approach retirement, the opportunity for employee ownership to play a central role in succession planning across Europe, North America and parts of Asia is substantial.

Crypto, Tokenization and New Frontiers of Ownership

The crypto and Web3 boom of the early 2020s introduced a radically different narrative about ownership, one that resonated strongly with younger, globally distributed workforces. While the subsequent market volatility and regulatory crackdowns in jurisdictions such as the United States, China and parts of Europe tempered some of the initial exuberance, the underlying idea of programmable, tokenized ownership has not disappeared. Instead, it has begun to converge with more traditional corporate structures in nuanced ways.

Decentralized autonomous organizations, or DAOs, attempted to reimagine corporate governance by distributing decision-making and economic rights via tokens. While many early DAOs struggled with governance, coordination and compliance, they provided a laboratory for new forms of participation. The Bank for International Settlements (BIS) and various central banks have closely studied these developments, particularly as they intersect with systemic financial stability and investor protection; readers can examine their analytical work on crypto and decentralized finance.

For companies covered in the crypto and investment sections of DailyBusinesss.com, the practical implication is that future employee ownership schemes may blend conventional equity with tokenized incentives that reflect usage, contribution or network effects. In technology ecosystems across the United States, Singapore, South Korea and Switzerland, legal and tax advisers are already working with founders to design compliant structures that allow employees to benefit from both equity appreciation and digital asset-based rewards. The U.S. Securities and Exchange Commission (SEC) and European regulators have signaled that such arrangements must fall within securities and employment law frameworks, underscoring that the frontier of ownership will remain heavily regulated even as it innovates.

Regional Dynamics: United States, Europe and Asia-Pacific

Employee ownership is evolving differently across regions, shaped by legal systems, labor markets, cultural norms and political priorities. In the United States, employee ownership has long benefited from a supportive tax environment and a strong ecosystem of specialized advisers, trustees and lenders. The U.S. Department of Labor oversees key aspects of ESOP regulation, and its guidance has helped formalize best practices around fiduciary duty and valuation; further information is available through its materials on employee benefit plans.

In the United Kingdom, government policy over the past decade has explicitly encouraged employee ownership as part of a broader industrial strategy focused on productivity and regional development. The UK Government's Department for Business and Trade provides guidance on employee ownership trusts and share schemes, and there is active collaboration between policymakers, business associations and advisory firms to support transitions. In continental Europe, the picture is more heterogeneous: France has a long history of employee shareholding, including state-supported schemes, while Germany and the Nordic countries are gradually expanding legal frameworks for employee equity, often in the context of start-up ecosystems in Berlin, Stockholm, Copenhagen and Helsinki.

In Asia-Pacific, jurisdictions such as Singapore, Japan, South Korea and Australia have been particularly proactive in refining their rules for employee stock ownership, especially to support technology and high-growth sectors. The Monetary Authority of Singapore (MAS) and Australian Securities and Investments Commission (ASIC) have both clarified regulatory expectations around equity compensation and tokenized incentives, recognizing their importance in attracting global talent. Meanwhile, in emerging markets such as Thailand, Malaysia, Brazil and South Africa, employee ownership is often linked to broader agendas around financial inclusion, black economic empowerment or industrial upgrading, with policymakers exploring how equity participation can support both competitiveness and social goals.

For readers tracking global policy and trade dynamics on the world and trade sections of DailyBusinesss.com, these regional differences illustrate how employee ownership is becoming a point of competitive differentiation in the global race to attract investment and talent.

Governance, Risk and the Trust Imperative

As employee ownership models proliferate, questions of governance, risk management and trust move to the foreground. Ownership without transparency, education and robust governance can create as many problems as it solves. Employees who receive equity or tokens without understanding valuation, liquidity, vesting or tax implications may become disillusioned, particularly if exit events are delayed or market conditions deteriorate. Similarly, poorly designed schemes that concentrate control in a small group while presenting a veneer of broad-based ownership can erode trust rather than build it.

Leading organizations and advisers emphasize that effective employee ownership requires a comprehensive approach that integrates equity design, financial education, communication and participatory governance. The Chartered Governance Institute and similar professional bodies have developed guidance on best practices in board oversight, disclosure and stakeholder engagement for companies with significant employee ownership. At the same time, standard setters such as the International Financial Reporting Standards (IFRS) Foundation provide accounting frameworks for share-based payments and equity instruments, ensuring that markets and regulators can assess the true economic impact of these schemes; readers can review IFRS guidance on share-based payments.

For the DailyBusinesss.com audience, which includes investors, executives and policy professionals, the trust dimension is particularly critical. Employee ownership is most powerful when it is part of a broader culture of transparency and shared purpose, supported by clear metrics and aligned incentives. In this sense, it intersects directly with environmental, social and governance (ESG) frameworks that institutional investors in North America, Europe and Asia increasingly use to evaluate corporate performance. The Principles for Responsible Investment (PRI) and UN Global Compact both highlight employee engagement and fair value sharing as components of responsible business conduct; those interested in sustainable corporate strategies can connect these themes with the analysis available on the sustainable business section of DailyBusinesss.com.

Capital Markets, Liquidity and Valuation Challenges

From a capital markets perspective, the expansion of employee ownership raises complex questions about liquidity, valuation and control. In private companies, particularly in mid-market and founder-led businesses, creating mechanisms for employees to realize value without forcing a sale or public offering can be challenging. Secondary markets, internal share buyback programs and employee-focused liquidity events are emerging as tools to address these issues, but they require careful structuring to avoid conflicts of interest and regulatory pitfalls.

For listed companies, broad-based equity compensation can lead to significant dilution if not managed carefully, prompting boards and investors to scrutinize the balance between incentive alignment and shareholder returns. The Nasdaq and New York Stock Exchange (NYSE), along with major European and Asian exchanges, have developed listing rules and disclosure requirements that govern stock-based compensation and related-party transactions, seeking to ensure that markets can accurately price these instruments. Readers who follow capital market developments on DailyBusinesss.com's investment and news sections will recognize how these dynamics influence valuation, earnings per share and investor sentiment.

Valuation itself becomes more nuanced when a substantial portion of equity is held by employees, particularly in companies with complex capital structures or multiple share classes. Independent valuation, robust internal controls and external audit oversight become essential to maintain confidence among all stakeholders. The International Valuation Standards Council (IVSC) and leading audit firms have published guidance on valuing share-based payments and closely held equity, underscoring the technical sophistication required to manage employee ownership at scale.

Travel, Mobility and the Cross-Border Workforce

The globalization of talent and the normalization of distributed work have added another layer of complexity to employee ownership. Professionals in AI, software engineering, design, finance and consulting now routinely work across borders, whether through relocation, digital nomad arrangements or hybrid assignments. This raises intricate questions about tax residency, securities law, foreign exchange controls and employment regulation when granting equity or tokens to employees in multiple jurisdictions.

Countries such as Spain, Portugal, Estonia and Thailand have introduced digital nomad visas and related frameworks that implicitly encourage global professionals to spend time within their borders while maintaining employment with foreign companies. At the same time, tax authorities and regulators in the United States, United Kingdom, Germany, Canada, Singapore and other major economies are refining their positions on cross-border equity compensation and reporting obligations. The OECD's work on tax policy and digitalization, particularly the Base Erosion and Profit Shifting (BEPS) project, provides important context on how governments are seeking to adapt tax systems to these new realities; readers can explore OECD tax digitalization resources.

For executives and HR leaders responsible for global mobility programs, these developments require close coordination between legal, tax, finance and people teams to design employee ownership schemes that are both competitive and compliant. On DailyBusinesss.com, discussions in the employment section increasingly highlight how cross-border work and equity participation are reshaping the employee value proposition, particularly for globally mobile professionals in technology, finance and consulting.

The Road Ahead: From Experiment to New Normal

By 2026, employee ownership has firmly entered the mainstream of corporate strategy, yet its trajectory is still unfolding. The convergence of AI-driven productivity, demographic shifts, geopolitical realignment and evolving expectations of fairness is creating fertile ground for models that share value more broadly without sacrificing competitiveness. For business leaders, investors and policymakers in the United States, United Kingdom, Germany, Canada, Australia, France, Italy, Spain, the Netherlands, Switzerland, China, Sweden, Norway, Singapore, Denmark, South Korea, Japan, Thailand, Finland, South Africa, Brazil, Malaysia, New Zealand and beyond, the strategic question is no longer whether employee ownership matters, but how to design and implement it in ways that are sustainable, transparent and aligned with long-term goals.

For the readership of DailyBusinesss.com, which spans AI, finance, business, crypto, economics, employment, founders, world affairs, investment, markets, sustainability, technology, travel and trade, employee ownership sits at the intersection of many of the themes that define the future of the global economy. It is simultaneously a financial instrument, a governance mechanism, a talent strategy and a social contract. As coverage across the platform's technology and tech sections has shown, the most successful organizations of the coming decade are likely to be those that harness the power of their people not only as employees, but as genuine owners and partners in value creation.

The momentum behind employee ownership suggests that the corporate landscape of the 2030s will look materially different from that of the 2010s. Companies that embrace thoughtful, well-governed ownership structures stand to benefit from stronger cultures, deeper engagement, greater resilience and enhanced legitimacy in the eyes of customers, regulators and society. Those that ignore these shifts may find it harder to compete for talent, capital and trust in an increasingly transparent and interconnected world.

Sustainable Packaging Solutions Disrupt Retail

Last updated by Editorial team at dailybusinesss.com on Monday 23 February 2026
Article Image for Sustainable Packaging Solutions Disrupt Retail

Sustainable Packaging Solutions Disrupt Retail: How the Next Decade of Commerce Is Being Re-Engineered

The Strategic Shift: Packaging Moves from Cost Center to Competitive Weapon

By 2026, sustainable packaging has moved from the margins of corporate social responsibility reports into the center of retail strategy, redefining how products are designed, shipped, marketed, and experienced across global markets. For the audience of DailyBusinesss.com, which spans decision-makers in AI, finance, retail, logistics, crypto, economics, employment, founders, investment, markets, and technology, the transformation of packaging is no longer a niche environmental concern; it is a material driver of cost structures, brand equity, regulatory risk, and innovation opportunity in North America, Europe, Asia, and beyond.

Retailers and brands in the United States, United Kingdom, Germany, Canada, Australia, France, Italy, Spain, Netherlands, Switzerland, China, Sweden, Norway, Singapore, Denmark, South Korea, Japan, Thailand, Finland, South Africa, Brazil, Malaysia, and New Zealand are now operating in a landscape where packaging decisions directly influence investor confidence, consumer trust, and access to markets. Regulatory frameworks such as the European Union's evolving packaging and packaging waste regulations, which can be explored through the European Commission's environment portal, and extended producer responsibility schemes in regions such as Canada and Asia, have forced retailers to rethink packaging as an integrated part of product lifecycle management rather than a post-production afterthought.

On DailyBusinesss.com, where coverage of global business trends and economic shifts is central, sustainable packaging now sits at the intersection of environmental policy, supply chain optimization, and digital transformation. The most advanced retailers are treating packaging as an innovation platform, leveraging data, automation, and design thinking to deliver new forms of value while addressing mounting pressures from regulators, institutional investors, and increasingly climate-conscious consumers.

Regulatory Pressure and Investor Scrutiny Redraw the Risk Landscape

The rapid escalation of regulation has been one of the primary catalysts for disruption in retail packaging. In Europe, the EU Green Deal and its associated legislation have accelerated requirements around recyclability, recycled content, and waste reduction, raising the compliance bar for any retailer operating in the single market. Businesses monitoring these developments through resources such as the European Environment Agency understand that packaging is becoming a measurable component of corporate climate and resource efficiency performance, with direct implications for access to public procurement opportunities and sustainable finance.

In the United States, the regulatory picture remains more fragmented, but state-level initiatives, such as extended producer responsibility laws in states including California, are converging toward a similar outcome: retailers must assume partial responsibility for the end-of-life management of packaging materials. Companies tracking these developments through organizations like the U.S. Environmental Protection Agency recognize that the cost of inaction increasingly manifests in the form of fees, penalties, and reputational risk. In Canada, Australia, and several Asian markets, comparable frameworks are emerging, creating a patchwork of obligations that multinational retailers must navigate with careful strategic alignment.

At the same time, institutional investors and asset managers, informed by frameworks such as those from the Task Force on Climate-related Financial Disclosures, are integrating packaging and materials use into their broader assessments of climate and transition risk. For retail leaders who follow investment and markets analysis on DailyBusinesss.com, it is increasingly clear that sustainable packaging performance can influence credit ratings, cost of capital, and inclusion in ESG indices. BlackRock, Vanguard, and other global asset managers have signaled that resource efficiency and circularity are now mainstream considerations, and packaging is a highly visible, quantifiable proxy for these capabilities.

This convergence of policy and capital market expectations has elevated packaging from an operational detail to a board-level conversation. Retailers now must demonstrate not only compliance but credible forward-looking strategies aligned with international sustainability goals, such as those outlined by the United Nations Environment Programme, if they wish to maintain their social license to operate and preserve long-term shareholder value.

Changing Consumer Expectations Across Regions and Demographics

The consumer dimension of this disruption is equally significant. In the aftermath of the pandemic-driven surge in e-commerce, households across North America, Europe, Asia, Africa, and South America have become acutely aware of the volume of packaging entering their homes, particularly from online orders. Surveys conducted by organizations such as the World Economic Forum and research institutions in Germany, Sweden, and Japan indicate that a growing share of consumers now associate excessive or non-recyclable packaging with corporate irresponsibility, especially in urban centers where waste management infrastructure is visible and under strain.

In markets such as the United Kingdom, Netherlands, and Denmark, where recycling systems are relatively mature, consumers are beginning to differentiate between brands based on the ease with which packaging can be sorted and recycled, while in emerging markets across Africa and South America, concerns often focus on visible litter and inadequate waste systems, reinforcing the reputational risk for global brands that fail to adapt their packaging strategies to local realities. Retailers that monitor global news and market sentiment understand that social media has amplified consumer scrutiny, with viral posts about excessive packaging or hard-to-recycle materials quickly translating into public relations challenges.

At the same time, there is nuanced variation across age groups and income segments. Younger consumers in Canada, Australia, Singapore, and South Korea, many of whom are already engaged with climate issues and digital activism, often expect brands to demonstrate leadership on sustainable packaging as part of a broader climate and social responsibility stance. More affluent consumers in Switzerland, Norway, and Finland may be willing to pay a premium for products with minimal or innovative packaging, particularly in sectors such as cosmetics, electronics, and specialty foods, where packaging is closely linked to brand identity. Retailers that fail to incorporate these shifting expectations into their product and packaging design risk erosion of loyalty and market share, particularly in competitive categories where switching costs are low.

Materials Innovation: From Bioplastics to Circular Fiber Systems

The most visible dimension of sustainable packaging disruption lies in materials innovation, where advances in chemistry, material science, and process engineering are reshaping what is possible at industrial scale. Traditional fossil-fuel-based plastics, while still dominant in many supply chains, are now challenged by a range of alternatives, including bio-based plastics, advanced paper and fiber materials, and reusable container systems designed for multiple cycles within circular logistics networks.

Research institutions and companies collaborating with organizations such as the Ellen MacArthur Foundation are pushing the boundaries of what circular packaging can achieve, emphasizing design for recyclability, reuse, and compostability. In Germany and France, where regulatory and consumer pressure is high, major retailers and consumer goods companies are piloting packaging made from agricultural residues, seaweed, and other renewable feedstocks, while in China and Japan, innovation often focuses on ultralight, high-strength materials that reduce overall material intensity and logistics emissions.

However, the transition is complex and requires careful life-cycle assessment. Not all bioplastics are inherently sustainable; some compete with food production or require specific industrial composting conditions that are not widely available. Organizations such as the OECD and national standards bodies in United States, Canada, and Europe have highlighted the importance of robust methodologies to evaluate trade-offs between greenhouse gas emissions, land use, water consumption, and end-of-life outcomes. Retailers that wish to avoid accusations of "greenwashing" must therefore integrate rigorous environmental assessment into their material selection processes, rather than relying on simplistic labels such as "biodegradable" or "eco-friendly".

For the DailyBusinesss.com audience focused on technology and innovation, the emerging frontier lies in smart materials that embed digital identifiers-such as QR codes, RFID tags, or novel tracer technologies-into packaging substrates. These features enable more accurate sorting in recycling facilities, support product authentication, and create new data streams for supply chain optimization. As AI-driven recognition systems improve, and as robotics in material recovery facilities become more sophisticated, packaging that is "machine-readable" as well as consumer-friendly is likely to become a competitive differentiator in global retail markets.

AI, Data, and Automation: The Intelligence Layer Behind Sustainable Packaging

Artificial intelligence has become a critical enabler of sustainable packaging strategies, turning what was once a static, one-time design decision into a dynamic, data-driven optimization process. For readers following AI developments on DailyBusinesss.com, the integration of machine learning into packaging design, demand forecasting, and reverse logistics marks one of the most impactful applications of AI within retail operations.

Leading retailers and logistics providers are using AI to simulate packaging performance across a variety of conditions, from warehouse handling to last-mile delivery in diverse climates across North America, Europe, and Asia. By integrating historical damage rates, transportation modes, and product characteristics, AI systems can recommend packaging configurations that minimize material use while maintaining product integrity, thereby reducing both waste and costly returns. Platforms that draw on research from institutions such as the Massachusetts Institute of Technology and other global universities are enabling more sophisticated modeling of packaging's impact on carbon emissions and operational efficiency.

In parallel, AI is playing a growing role in waste management and recycling, particularly in advanced economies such as Germany, Sweden, Japan, and South Korea, where automated sorting facilities rely on computer vision and robotics to identify and separate different packaging materials. Companies collaborating with research organizations and technology leaders referenced by the International Solid Waste Association are demonstrating that AI-enabled sorting can significantly increase the recovery rates of high-value materials, making recycling more economically viable and supporting the business case for recyclable packaging design.

Data analytics is also reshaping the business model for reusable and refillable packaging systems. Retailers and startups in United Kingdom, France, Singapore, and United States are experimenting with digital deposit-return schemes and app-based tracking of reusable containers, leveraging smartphones and cloud platforms to manage asset pools, optimize collection routes, and encourage consumer participation. The intersection of fintech, crypto-enabled incentives, and sustainable packaging is an emerging area of interest for readers who follow crypto and finance trends on DailyBusinesss.com, as tokenized rewards and micro-payments could theoretically support more granular, performance-based incentives for circular behavior.

Financial Implications: Cost, Capital, and Competitive Positioning

From a financial perspective, sustainable packaging is frequently mischaracterized as a pure cost increase, when in reality it represents a complex mix of upfront investment, operational savings, risk mitigation, and revenue opportunity. For executives and investors tracking finance and markets, the key question is not whether sustainable packaging is more expensive in the short term, but how it reshapes the overall economics of retail operations and brand positioning over a multi-year horizon.

In the short run, transitioning to new materials, redesigning packaging formats, and updating machinery can indeed require capital expenditure and higher unit costs, particularly where supply chains for advanced materials are still maturing. However, as documented by organizations such as the World Bank, efficiency gains in logistics, reduced damage and return rates, lower waste disposal costs, and improved compliance with regulatory frameworks often offset a significant portion of these expenses. Moreover, the risk of stranded assets and regulatory non-compliance is becoming more tangible as jurisdictions phase out certain single-use plastics and impose minimum recycled content requirements.

Access to sustainable finance is another important dimension. Banks and investors guided by principles from the UN Principles for Responsible Investment and similar frameworks are increasingly willing to offer favorable financing terms to companies that demonstrate credible pathways toward circularity and resource efficiency. Retailers that can quantify the impact of their packaging strategies on emissions, waste, and resource use may be better positioned to tap into green bonds, sustainability-linked loans, and other instruments that tie cost of capital to environmental performance metrics.

On the revenue side, sustainable packaging can support premium pricing, category differentiation, and market entry into environmentally conscious segments, particularly in countries such as Germany, Switzerland, Nordic markets, and New Zealand, where environmental awareness is high. For digitally native brands that rely on e-commerce and social media, packaging has become a storytelling medium that communicates values, transparency, and innovation. The ability to articulate a credible, data-backed narrative about packaging sustainability can therefore contribute to brand equity and customer lifetime value, themes that resonate strongly with founders and growth-stage companies featured on DailyBusinesss.com's founders coverage.

Employment, Skills, and Organizational Change in the Packaging Transition

The shift toward sustainable packaging is not only a technological and financial story; it is also reshaping employment patterns, skills requirements, and organizational structures across the global retail value chain. For readers of DailyBusinesss.com who focus on employment and labor markets, the packaging transition illustrates how environmental objectives intersect with workforce development and corporate culture.

As retailers and consumer goods companies redesign packaging systems, demand is growing for specialists in materials science, life-cycle assessment, regulatory affairs, and circular business models. Packaging engineers who once focused primarily on cost and mechanical performance must now integrate environmental metrics, recyclability standards, and digital traceability into their work. Sustainability teams, which in many organizations were historically peripheral, are increasingly embedded within core product development and supply chain functions, reflecting the strategic importance of packaging decisions.

At the same time, new roles are emerging in reverse logistics, reuse system management, and digital platform operations. Companies experimenting with reusable packaging in Europe, Asia, and North America require staff to manage collection networks, refurbishment processes, and customer engagement programs, while waste management firms are hiring data analysts and AI specialists to operate advanced sorting facilities. Reports from the International Labour Organization suggest that the transition to more sustainable production and consumption models, including packaging, can create net employment gains if supported by appropriate training and policy frameworks.

Organizationally, sustainable packaging demands cross-functional collaboration that cuts across traditional silos. Marketing, operations, procurement, finance, and sustainability leaders must align around shared objectives and metrics, supported by transparent governance structures and clear accountability. For global retailers with complex supply chains spanning Asia, Africa, South America, and Europe, this often requires new forms of supplier engagement, joint innovation programs, and shared data platforms that enable consistent implementation of packaging standards across regions and product categories.

Global Supply Chains, Trade, and Geopolitical Considerations

Sustainable packaging is deeply intertwined with global trade and supply chain dynamics, making it a critical topic for readers interested in world affairs and trade and global trade flows. As governments introduce border adjustment mechanisms and environmental standards that apply to imported goods, packaging is becoming a factor in trade compliance and market access.

For example, as the European Union and other jurisdictions consider or implement carbon border adjustment mechanisms and stricter packaging waste directives, exporters from China, Brazil, South Africa, Thailand, and other manufacturing hubs must adapt their packaging practices to meet destination market requirements. Failure to do so can lead to delays at customs, additional costs for repackaging, or even denial of market entry. Trade policy analysis from organizations such as the World Trade Organization highlights the growing role of environmental standards, including packaging, in shaping the terms of international commerce.

Supply chain resilience is another dimension. Disruptions in the availability of certain plastic resins or paper grades, whether due to geopolitical tensions, energy price volatility, or climate-related events, have underscored the vulnerability of packaging-dependent operations. Retailers that diversify material sources, invest in recycled content, and build more localized packaging supply chains can reduce exposure to such shocks, aligning with broader strategies for resilience and risk management that are central to executive discussions on DailyBusinesss.com.

In the travel and hospitality sectors, where readers may follow insights via travel and global business coverage, sustainable packaging intersects with tourism trends and destination management. Airlines, hotels, and food service operators in regions such as Europe, Asia, and Oceania are under pressure to reduce single-use plastics and visible waste, both to meet regulatory requirements and to align with the expectations of environmentally conscious travelers. Packaging decisions in these sectors can influence destination branding, local waste management systems, and community relations, reinforcing the idea that packaging is a strategic lever rather than a mere operational detail.

The Road Ahead: Strategic Priorities for Retail Leaders

As 2026 progresses, sustainable packaging stands as one of the most tangible, measurable, and strategically rich arenas in which retail leaders can demonstrate commitment to environmental responsibility while unlocking operational and financial benefits. For the business community that turns to DailyBusinesss.com for analysis of markets, technology, and the future of commerce, several priorities are emerging as markers of serious intent and long-term competitiveness.

First, retailers must embed packaging considerations into core business strategy, aligning them with climate targets, circular economy objectives, and digital transformation roadmaps. This requires executive-level ownership, clear key performance indicators, and integration with broader sustainability programs of the type discussed in sustainable business coverage. Second, investment in data, AI, and automation is essential to move from incremental improvements to systemic optimization, enabling dynamic adaptation of packaging solutions to changing product portfolios, regulatory environments, and consumer behaviors.

Third, collaboration across value chains and sectors will be critical. No single retailer, brand, or logistics provider can solve the systemic challenges of packaging waste and circularity in isolation. Partnerships with material innovators, recyclers, technology firms, and policymakers-supported by insights from organizations such as the World Resources Institute-will determine the pace and scale of progress. Finally, transparent communication with consumers, investors, and employees, grounded in robust data and realistic timelines, will be necessary to build trust and avoid the reputational pitfalls associated with overstated or poorly substantiated sustainability claims.

For a global readership engaged with the evolving intersection of AI, finance, business, crypto, economics, employment, founders, world affairs, investment, markets, news, sustainability, technology, travel, future trends, and trade, sustainable packaging is an emblematic case of how environmental imperatives and commercial logic are converging. The retailers and brands that understand this convergence and act decisively will not only reduce their environmental footprint but also shape the next decade of retail innovation, setting new benchmarks for efficiency, resilience, and trust in an increasingly scrutinized global marketplace.

Retail Investors Influence Market Dynamics

Last updated by Editorial team at dailybusinesss.com on Monday 23 February 2026
Article Image for Retail Investors Influence Market Dynamics

How Retail Investors Are Reshaping Global Market Dynamics in 2026

A New Center of Gravity in Capital Markets

By 2026, retail investors have moved from the margins of global finance to a position of undeniable influence, altering how capital is allocated, how companies communicate with the market, and how regulators think about stability and fairness. What was once perceived as a sporadic, sentiment-driven force has matured into a structurally significant component of market liquidity and price discovery, particularly in the United States, United Kingdom, Europe and Asia, but increasingly across every major financial hub from New York and London to Singapore, Sydney, Frankfurt and Toronto. For readers of DailyBusinesss who track developments in finance, markets, investment and technology, understanding this shift is now essential to interpreting volatility, valuations and long-term strategic opportunities.

This transformation has been driven by a combination of zero-commission trading, fractional shares, social media-enabled communities, rapid advances in artificial intelligence, and a broader cultural shift in which individuals in the United States, Europe, Asia and beyond view investing not only as a means of wealth creation but also as a form of participation in technological, environmental and societal change. As institutions, regulators and corporate leaders adapt, the influence of the retail segment is no longer measured merely in trading volume, but in its ability to catalyze narratives, accelerate adoption of new asset classes such as digital assets, and pressure boards and executives to address governance, sustainability and stakeholder concerns more directly.

From Fringe Participants to Structural Market Players

The evolution of retail investors from occasional traders to structural market participants can be traced through several inflection points, notably the commission-free trading revolution led by platforms such as Robinhood Markets, the pandemic-era surge in account openings across Charles Schwab, Fidelity Investments, Interactive Brokers and European platforms like Trade Republic and eToro, and the global meme-stock episodes that began in 2021. These developments coincided with historically low interest rates, fiscal stimulus in the United States, United Kingdom, Canada and parts of Europe, and a renewed focus on personal finance education through digital channels.

Data from organizations such as the Bank for International Settlements and national regulators including the U.S. Securities and Exchange Commission show that retail participation in equity and options markets has remained elevated even as pandemic-era conditions faded, suggesting a structural rather than cyclical shift. In major markets like the United States and South Korea, individual investors now account for a significant share of daily turnover in equities and derivatives, often exceeding 20-25 percent in specific segments. In Europe, retail participation has grown in Germany, France, Italy, Spain and the Netherlands, while in Asia, markets such as Japan, Singapore, Thailand and India have seen pronounced growth in direct equity and exchange-traded fund ownership.

For readers of DailyBusinesss following the broader business landscape, this change in market structure means that corporate funding costs, valuation multiples and even strategic decisions around listing venues or spin-offs can be influenced by the preferences and behaviors of millions of individual investors rather than a relatively small cohort of institutional asset managers alone.

Technology, AI and the Democratization of Market Access

The most visible driver of this shift has been the rapid democratization of market access, powered by digital trading platforms, mobile-first interfaces and, increasingly, embedded AI tools. Commission-free trading, real-time quotes and fractional share capabilities have lowered the barrier to entry across North America, Europe and parts of Asia-Pacific, enabling investors in countries from the United States and United Kingdom to Australia, New Zealand and Singapore to participate in global equity, ETF and crypto markets with minimal friction.

At the same time, retail investors have gained access to sophisticated research and analytics that were once the preserve of institutional desks. Natural-language interfaces and AI-driven screening tools, often built on top of open-source frameworks or commercial APIs, allow individuals to interrogate company fundamentals, compare sector metrics and simulate portfolio scenarios in a matter of seconds. Platforms such as Bloomberg, Refinitiv, Morningstar and S&P Global increasingly tailor digital offerings to the self-directed segment, while educational initiatives from organizations like the OECD and World Bank provide guidance on financial literacy and responsible investing. Readers interested in how AI is transforming the investor toolkit can explore the dedicated coverage on AI and automation in markets to understand the emerging capabilities and associated risks.

In parallel, the integration of open banking and digital identity frameworks across the European Union, the United Kingdom, Canada, Australia and parts of Asia has simplified funding, verification and reporting processes, making cross-border investing more accessible. This has contributed to a more globally connected retail investor base, in which individuals in Germany or Sweden can trade U.S. tech stocks as easily as domestic equities, and investors in Brazil, South Africa or Malaysia can increasingly access international ETFs and thematic funds listed in New York, London or Hong Kong.

The Social Layer: Communities, Narratives and Collective Action

Beyond technology, the social layer of modern markets has become a defining feature of retail investor influence. Forums, messaging platforms and social networks have evolved into continuous, real-time conversations where investment theses are debated, challenged and amplified. While the early meme-stock episodes highlighted the speculative and sometimes chaotic side of this phenomenon, the landscape in 2026 is more nuanced, with communities ranging from day-trading groups to long-term fundamental investors, environmental and social impact advocates, and specialized sector forums focused on areas such as semiconductors, renewable energy, healthtech and cryptoassets.

Academic research from institutions such as MIT, Stanford University and the London School of Economics has explored how online narratives can propagate through markets, sometimes leading to short-term mispricings but also fostering deeper engagement with corporate disclosures and macroeconomic trends. For business leaders and policymakers, understanding these narrative dynamics has become increasingly important, as they can shape perception around earnings announcements, regulatory developments or product launches, particularly in high-growth sectors like AI, clean energy and digital payments. Readers can learn more about how narratives influence economic outcomes by reviewing broader analysis of global economics and policy that situates retail behavior within macro-financial frameworks.

This socialization of investing has also blurred the lines between education, entertainment and activism. Influential creators on platforms such as YouTube and X (formerly Twitter) share long-form analyses and real-time commentary, sometimes rivaling traditional media in reach. Regulators in the United States, United Kingdom, European Union and Asia have responded with guidelines and enforcement actions around paid promotions, disclosure of conflicts of interest and the use of social media in securities marketing, reflecting a growing recognition that digital influence can have material market consequences.

Retail Flows, Liquidity and Volatility

From a market microstructure perspective, the most direct impact of retail investors is visible in liquidity patterns, intraday volatility and order-book dynamics. Retail order flow, often executed through marketable orders routed to wholesale market makers, can provide substantial liquidity, particularly in large-cap U.S. equities, options and popular exchange-traded funds. Market-making firms such as Citadel Securities and Virtu Financial have built sophisticated systems to internalize and hedge this flow, contributing to tighter spreads in many instruments while also concentrating execution in a relatively small number of intermediaries.

However, the episodic nature of retail participation, especially in response to news, social media narratives or macro events, can amplify volatility. Episodes in which retail investors collectively target heavily shorted stocks, small-cap names or niche cryptoassets have demonstrated the capacity for rapid price dislocations, sometimes forcing institutional short sellers to cover positions at significant losses and triggering feedback loops in derivatives markets. The Federal Reserve, European Central Bank and other central banks have studied these dynamics in the context of financial stability, particularly where leverage, margin lending or complex derivatives intersect with concentrated retail positions.

For readers of DailyBusinesss who monitor market structure and trading trends, this interplay between retail flow and institutional positioning is now a core variable in assessing risk, particularly around earnings seasons, macro data releases and geopolitical events. It has also influenced how institutional investors execute large orders, manage short exposure and communicate with clients about potential squeezes or liquidity gaps in specific segments.

The Crypto Dimension: Retail as Early Adopters and Price Setters

The rise of digital assets has provided a vivid example of how retail investors can shape an entire asset class. From the early days of Bitcoin and Ethereum through the waves of altcoins, stablecoins and decentralized finance protocols, individual investors have consistently been at the forefront of adoption, experimentation and, at times, speculative excess. In many jurisdictions, including the United States, United Kingdom, Canada, Germany, Switzerland, Singapore and South Korea, retail demand played a central role in driving the development of regulated exchanges, custody solutions and, more recently, spot crypto exchange-traded products.

Regulatory bodies such as the U.S. Commodity Futures Trading Commission, the Financial Conduct Authority in the UK and the Monetary Authority of Singapore have sought to balance innovation with consumer protection, issuing guidance on advertising, leverage, stablecoin reserves and the custody of digital assets. The interplay between retail enthusiasm and regulatory caution has shaped the pace of institutional adoption, with major asset managers and banks entering the space more decisively only once clearer frameworks emerged. Readers aiming to stay ahead of developments in this domain can follow dedicated coverage of crypto and digital assets, where the intersection of retail behavior, regulatory change and institutional strategy is closely tracked.

By 2026, the integration of tokenized assets, blockchain-based settlement and programmable securities into mainstream financial infrastructure is underway, with pilot projects in Europe, Asia and North America exploring tokenized bonds, funds and real-world assets. Retail investors, often more comfortable with digital wallets and on-chain transactions than traditional paperwork-heavy processes, are likely to remain influential in determining which platforms, protocols and asset types gain traction.

Retail Investors, ESG and the Sustainability Agenda

Another dimension of retail influence is visible in the growth of environmental, social and governance investing. While large institutional investors such as BlackRock, Vanguard and State Street have drawn attention for their stewardship policies and voting power, retail investors across the United States, Europe, Australia, Canada and parts of Asia have increasingly expressed preferences for sustainable business models, low-carbon strategies and stronger governance practices. This has translated into flows toward ESG-themed funds and green bonds, as well as direct engagement with companies on issues ranging from climate risk and supply chain transparency to diversity and executive compensation.

Organizations such as the United Nations Principles for Responsible Investment, the World Economic Forum and the Task Force on Climate-related Financial Disclosures have promoted frameworks that enable investors to assess and compare corporate sustainability efforts. Yet it is often retail sentiment, amplified through social media, that accelerates reputational pressure on companies perceived to be lagging on environmental or social commitments. For executives and boards, this means that sustainability narratives must be grounded in credible data and measurable progress, as retail shareholders can quickly mobilize around perceived inconsistencies between stated goals and actual performance. Those interested in how sustainability intersects with market behavior can explore more in-depth coverage of sustainable business and finance, where these trends are analyzed from both a strategic and regulatory perspective.

Global and Regional Variations in Retail Power

While the overarching trend toward greater retail influence is global, its expression varies significantly by region, reflecting differences in regulatory frameworks, cultural attitudes toward investing, tax regimes and the maturity of local capital markets. In the United States, the combination of deep equity markets, long-standing 401(k) and IRA systems, and a vibrant fintech ecosystem has created a particularly powerful retail base that participates both directly in stocks and indirectly through mutual funds and ETFs. In the United Kingdom and Europe, the growth of individual savings accounts, robo-advisors and low-cost brokers has broadened access, though bank deposits and real estate still dominate household balance sheets in many countries such as Italy, Spain and France.

In Asia, markets such as South Korea and Japan have strong traditions of retail stock ownership, while Singapore, Hong Kong and increasingly Thailand and Malaysia serve as hubs for cross-border investment into regional and global assets. China presents a unique case, with a large and active domestic retail investor base operating under a distinct regulatory environment and capital controls, while also accessing offshore markets through Hong Kong and overseas platforms where permitted. In emerging markets across Africa and South America, including South Africa and Brazil, the combination of inflation concerns, currency volatility and the rise of mobile-based brokerage platforms has spurred interest in both local equities and U.S. dollar-denominated assets, though regulatory and infrastructure constraints still limit full integration with global markets.

For the global readership of DailyBusinesss, which spans North America, Europe, Asia-Pacific and emerging markets, these regional nuances are crucial when evaluating cross-border investment themes, capital flows and the potential for retail-driven episodes of volatility or opportunity. Coverage across world markets and geopolitics increasingly highlights how domestic retail behavior interacts with currency moves, trade policy and macroeconomic cycles.

Implications for Founders, Executives and Policy Makers

The rise of the retail investor has important implications not only for asset managers and traders but also for founders, executives and policymakers. For high-growth companies in technology, AI, fintech, healthtech and climate solutions, retail investors can serve as early supporters, brand advocates and, in some cases, sources of patient capital when institutional sentiment turns cautious. Public companies with strong consumer brands, particularly in sectors such as e-commerce, electric vehicles, semiconductors and entertainment, often find that a significant portion of their shareholder base consists of customers who view equity ownership as an extension of brand loyalty.

This dynamic requires a more sophisticated approach to investor relations, with clear, accessible communication that resonates with both professional analysts and individual investors. Transparency around business models, unit economics, competitive positioning and risk factors becomes essential, as retail shareholders are increasingly adept at dissecting earnings calls, regulatory filings and independent research. Founders and executives featured in founder-focused coverage on DailyBusinesss often emphasize the importance of building trust with this broader investor community, recognizing that misalignment between narrative and execution can quickly translate into share-price pressure.

For policymakers and regulators, the challenge lies in balancing the benefits of democratized access with the need to protect less experienced investors from fraud, excessive leverage and complex products that may not be well understood. Initiatives from bodies such as the International Organization of Securities Commissions, the European Securities and Markets Authority and national regulators in the United States, United Kingdom, Australia and Singapore increasingly focus on product governance, suitability assessments, disclosure standards and digital marketing practices. At the same time, there is growing recognition that paternalistic restrictions can inadvertently entrench wealth disparities by limiting access to growth opportunities. The policy debate therefore centers on how to equip individuals with the tools, information and safeguards needed to participate responsibly in markets that are more complex and interconnected than ever.

Employment, Skills and the Professionalization of Retail Participation

The increased prominence of retail investors has also intersected with employment trends and the future of work. As remote and flexible work arrangements have become more common in the United States, Europe, Canada, Australia and parts of Asia, some individuals have allocated more time to active investing or trading, treating it as a side business or, in some cases, a full-time occupation. This has created demand for educational content, data services and risk-management tools, while also blurring boundaries between amateur and professional activity.

Universities, business schools and online education platforms have responded with courses in quantitative finance, behavioral investing and data-driven trading strategies, often incorporating AI-powered analytics and simulation tools. Organizations such as CFA Institute and professional bodies in Europe and Asia have expanded resources for individual investors, recognizing that a more financially literate population can contribute to deeper, more stable capital markets. For those tracking labor and skill trends, the intersection of investing, data science and digital entrepreneurship is increasingly visible in employment and future-of-work coverage, where the professionalization of retail participation is viewed as both an opportunity and a risk, depending on how individuals manage leverage, diversification and psychological pressures.

Strategic Considerations for 2026 and Beyond

As 2026 unfolds, several strategic themes emerge for businesses, investors and policymakers seeking to navigate the continued rise of retail influence in global markets. First, the integration of AI and data analytics into retail platforms will likely deepen, enabling more personalized portfolio construction, automated risk warnings and scenario analysis, but also raising questions about algorithmic bias, transparency and the potential for herding behavior if many investors rely on similar models. Second, the continued expansion of tokenized and digital assets, supported by initiatives from institutions such as the Bank of England, European Investment Bank and Monetary Authority of Singapore, will further blur boundaries between traditional securities and blockchain-based instruments, with retail investors at the forefront of adoption.

Third, demographic shifts, including the ongoing wealth transfer from baby boomers to younger generations in North America, Europe and parts of Asia, will influence asset preferences, risk tolerance and the importance attached to sustainability, social impact and technological innovation. Younger investors, often more comfortable with digital tools and more vocal on environmental and social issues, are likely to reinforce trends toward ESG integration, thematic investing and direct engagement with corporate governance. Finally, geopolitical and macroeconomic uncertainties-from inflation dynamics and interest-rate paths to trade tensions and technological competition between major powers-will continue to test the resilience of retail investors and the robustness of regulatory frameworks designed to protect them.

For the readership of DailyBusinesss, which spans founders, executives, policymakers, asset managers and self-directed investors across continents, the central takeaway is that retail investors are no longer a peripheral consideration in market analysis or corporate strategy. Their collective decisions, shaped by technology, social networks, macroeconomic conditions and cultural shifts, now form a critical part of the global financial ecosystem. Staying informed through rigorous, data-driven coverage of news and market developments, while maintaining a disciplined approach to risk and long-term value creation, will be essential for anyone seeking to navigate this new era in which individual investors play a central role in shaping market dynamics and, by extension, the trajectory of the global economy.

Thailand's Rise as an Electric Vehicle Hub

Last updated by Editorial team at dailybusinesss.com on Monday 23 February 2026
Article Image for Thailand's Rise as an Electric Vehicle Hub

Thailand's Rise as a Global Electric Vehicle Hub in 2026

A New Chapter in Thailand's Industrial Story

By 2026, Thailand has moved decisively beyond its traditional branding as the "Detroit of Asia" and is increasingly recognized as one of the world's most dynamic electric vehicle hubs, a shift that is reshaping regional supply chains, capital flows, employment patterns and technology ecosystems. For the global business audience of DailyBusinesss.com, this transformation is not merely a regional industrial upgrade; it is a case study in how a middle-income economy can reposition itself at the intersection of advanced manufacturing, clean technology and strategic trade, while competing head-to-head with larger players in China, Europe and North America.

Over the past decade, the Thai government and private sector have worked in tandem to attract leading global automakers, battery producers and component suppliers, while also nurturing a new generation of domestic technology firms that support software, charging infrastructure, energy management and mobility services. This has been supported by an evolving policy framework that links industrial strategy, foreign investment promotion, green finance and employment development, creating a foundation that many investors and analysts now see as structurally durable rather than cyclical. For readers tracking developments in global business and markets, Thailand's EV ascent provides a lens through which to understand the next phase of competition in the automotive and clean energy industries.

Strategic Positioning in the Global EV Value Chain

Thailand's rise in the EV space is rooted in its longstanding strength as a regional automotive manufacturing base, with decades of experience hosting major Japanese, European and American brands that have used the country as an export platform to Southeast Asia, Oceania and beyond. Building on this legacy, the government has deliberately repositioned the sector around electrification, offering targeted incentives for battery electric vehicles, plug-in hybrids and supporting components, while maintaining open trade and investment channels that appeal to multinational corporations seeking to diversify their manufacturing footprints.

For companies planning cross-border investment strategies, Thailand's geographic and logistical advantages are increasingly important. Its proximity to major consumer markets in China, India, Indonesia and the broader ASEAN region, combined with deep-water ports and integrated supply chains for electronics, steel, chemicals and plastics, enables efficient export of EVs and components to both regional and global destinations. Organizations studying regional trade flows can find complementary context in broader trade and global market analysis, which reveals how Thailand is embedding itself into the evolving architecture of Indo-Pacific supply chains.

International institutions such as the World Bank and Asian Development Bank have highlighted Thailand's manufacturing capabilities and infrastructure in their assessments of regional competitiveness, and business leaders increasingly reference these comparative advantages when choosing locations for new EV and battery plants. Those seeking a high-level macroeconomic overview can explore how this industrial shift aligns with broader global economic trends and the transition toward low-carbon growth models.

Policy, Incentives and the Evolving Regulatory Landscape

The policy framework underpinning Thailand's EV rise has become more sophisticated and targeted over time, moving from broad automotive incentives to carefully designed packages that specifically favor electrification, battery manufacturing and charging infrastructure. Agencies such as the Board of Investment of Thailand have rolled out multi-year tax holidays, import duty reductions for key components and support for research and development, while the government has implemented consumer-side subsidies and excise tax reductions to stimulate domestic demand for electric vehicles.

In parallel, regulators have begun to align national standards with global norms on vehicle safety, battery recycling and charging interoperability, seeking to ensure that EVs produced in Thailand meet the requirements of export markets in the European Union, the United States and other advanced economies. Businesses monitoring these developments can learn more about evolving regulatory frameworks and sustainable industrial strategies through resources provided by organizations such as the International Energy Agency, which regularly publishes analysis on electric vehicle policies and deployment.

For investors and corporate strategists, the credibility and consistency of policy are critical components of trust. Thailand has worked to signal long-term commitment by embedding EV targets within its broader climate and energy strategies, including its nationally determined contributions under the Paris Agreement and its long-term low-emissions development plans. Readers interested in how these commitments link to global climate and sustainability frameworks can explore the work of the United Nations Framework Convention on Climate Change, which provides detailed information on national climate strategies and goals.

Foreign Direct Investment and the New Competitive Landscape

Thailand's EV transition has been accelerated by a wave of foreign direct investment from established automakers and rising EV specialists, particularly from China, Japan, South Korea and Europe. Companies such as BYD, Great Wall Motor, SAIC Motor, Toyota, Honda, Hyundai, Mercedes-Benz and BMW have either announced or expanded EV-related projects in the country, ranging from complete vehicle assembly to battery pack production and advanced components such as inverters and electric drive units.

These investments are not only about manufacturing scale; they also bring advanced process technologies, quality systems and digitalization capabilities that raise the overall sophistication of Thailand's industrial base. The presence of global tier-one suppliers in power electronics, thermal management and lightweight materials further deepens the ecosystem, creating opportunities for local firms to integrate into international supply chains. For readers of DailyBusinesss.com focused on investment opportunities and market dynamics, Thailand's EV cluster now represents a complex network of cross-border partnerships, joint ventures and technology licensing arrangements that merit close monitoring.

International trade and investment organizations, including the OECD and UNCTAD, have documented rising greenfield investment in clean technology manufacturing across Southeast Asia, with Thailand frequently cited as a leading destination. Those seeking structured data and comparative analysis may find value in exploring global investment trend reports that place Thailand's EV surge within a broader wave of sustainable industrial investment across emerging markets.

Building a Battery and Materials Ecosystem

No EV hub can be truly competitive without a robust battery and materials ecosystem, and Thailand has made measurable progress in attracting both cell manufacturers and upstream materials processors. Joint ventures between global battery companies and local partners are establishing facilities for cell assembly, module and pack integration and, increasingly, localized production of cathode and anode materials, as well as electrolyte and separator components. This is complemented by investments in copper processing, aluminum casting and other materials essential for electric drivetrains and charging infrastructure.

While Thailand does not possess the same scale of domestic critical mineral resources as some competitors, it is positioning itself as a regional processing and manufacturing center that can import raw or semi-processed materials from partners in Australia, Indonesia, Africa and South America, and then add value through advanced manufacturing and quality control. Businesses tracking commodity markets and energy transition supply chains may want to examine insights from agencies like the International Energy Agency, which publishes detailed work on critical minerals and battery supply chains.

At the same time, the Thai government and industry associations are beginning to design frameworks for battery recycling and second-life applications, recognizing that end-of-life management will be central to long-term sustainability and cost competitiveness. For companies and investors interested in circular economy models and green manufacturing, resources on sustainable industrial practices provide useful benchmarks against which to measure Thailand's emerging policies and standards.

Technology, AI and the Digital Layer of Thailand's EV Hub

The transformation of Thailand into an EV hub is not limited to hardware; it is equally a story of software, data and artificial intelligence. Automakers and suppliers operating in the country are increasingly integrating AI-driven quality control, predictive maintenance and supply-chain optimization into their operations, while also experimenting with connected vehicle platforms, over-the-air software updates and advanced driver assistance systems that rely on high-quality data and robust cybersecurity.

Local technology firms and startups are emerging as important partners in this digital layer, providing solutions for fleet management, smart charging, payment integration and mobility-as-a-service platforms that connect EVs with public transport, logistics networks and consumer applications. This convergence of manufacturing and digital innovation aligns closely with themes covered in DailyBusinesss.com's coverage of artificial intelligence and emerging technologies, where Thailand's EV sector now serves as a live testbed for Industry 4.0 and smart factory concepts.

Global technology leaders such as NVIDIA, Google, Microsoft and Amazon Web Services are also active in supporting cloud infrastructure, AI tools and data platforms that underpin connected mobility solutions, and many of their regional initiatives have direct or indirect links to automotive and EV applications. Business leaders examining the broader technological context can explore more about industrial AI and digital transformation to understand how Thailand's EV hub fits into the global shift toward data-driven manufacturing.

Finance, Capital Markets and the Economics of Thailand's EV Transition

Behind the physical factories and infrastructure lies a complex financial architecture that channels capital into Thailand's EV ecosystem. Domestic banks, regional lenders and international financial institutions are increasingly providing project finance, green loans and sustainability-linked instruments for EV and battery projects, often tied to performance metrics such as emissions reduction, energy efficiency or social impact. This has been accompanied by growing interest from private equity, infrastructure funds and sovereign wealth funds seeking exposure to long-term clean mobility assets.

Thailand's capital markets have also begun to reflect this shift, with listed companies in automotive, energy and technology sectors disclosing more detailed information on their EV strategies and sustainability performance, in line with evolving environmental, social and governance expectations. Investors who follow finance and markets coverage on DailyBusinesss.com will recognize that EV-related assets are increasingly seen as a proxy for broader themes such as decarbonization, digitalization and regional integration, which shape portfolio allocation decisions across North America, Europe and Asia.

International bodies such as the Financial Stability Board and Bank for International Settlements have highlighted the importance of managing climate-related financial risks, including the transition risks associated with shifting from internal combustion engines to EVs. Those seeking deeper insight into how financial regulators and central banks are responding to this structural change can review global guidance on climate and financial stability and consider how Thailand's policy and regulatory environment aligns with emerging best practices.

Employment, Skills and the Future of Work in Thailand's EV Sector

The evolution of Thailand into an EV hub carries profound implications for employment, skills development and the future of work. While electrification can reduce the complexity of powertrain manufacturing compared with internal combustion engines, it also introduces new requirements in electronics, software, battery engineering and high-precision manufacturing that demand a different mix of competencies. Thai universities, vocational institutions and corporate training programs are responding by updating curricula, expanding engineering and technical programs and forming partnerships with automakers, battery producers and technology firms.

For workers and policymakers, the central challenge is managing the transition in a way that preserves employment opportunities while upgrading skills and productivity. This includes retraining workers from traditional automotive roles, such as engine assembly or exhaust systems, into areas like battery pack integration, power electronics and advanced quality assurance. Readers interested in the human capital dimension of this industrial shift can explore employment and skills coverage on DailyBusinesss.com, which frequently examines how technological change reshapes labor markets in both advanced and emerging economies.

Global organizations such as the International Labour Organization and World Economic Forum have underscored the importance of reskilling and lifelong learning in the context of the green and digital transitions, and Thailand's EV strategy is increasingly viewed as a practical test of these concepts. Business leaders evaluating investment in Thai operations often consider not only wage levels and labor regulations but also the depth of the talent pool and the robustness of training ecosystems, recognizing that long-term competitiveness depends on sustained investment in people as much as in machinery.

Sustainability, Climate Goals and Thailand's Green Ambitions

At a time when governments and corporations worldwide are under pressure to align with net-zero targets, Thailand's emergence as an EV hub is closely tied to its broader sustainability and climate agenda. The transport sector is a major source of greenhouse gas emissions, and accelerating EV adoption is a central pillar of Thailand's strategy to reduce emissions, improve urban air quality and enhance energy security by lowering dependence on imported fossil fuels. This aligns with global efforts to decarbonize mobility, as documented by organizations such as the International Renewable Energy Agency, which provides extensive analysis on electrification and renewable integration.

However, the environmental benefits of EVs depend on the carbon intensity of the electricity grid, the sustainability of battery materials and the effectiveness of recycling systems. Thailand is therefore pursuing parallel initiatives to expand renewable energy capacity, modernize its power grid and promote energy efficiency in industry and buildings. Business readers can explore sustainable business and climate coverage on DailyBusinesss.com to understand how these initiatives intersect with corporate strategies in sectors ranging from energy and utilities to real estate and logistics.

International frameworks such as the Task Force on Climate-related Financial Disclosures and emerging global standards on sustainability reporting are pushing companies operating in Thailand's EV ecosystem to provide more transparency on their environmental impacts and mitigation strategies. This growing emphasis on disclosure and accountability reinforces Thailand's efforts to position itself not just as a cost-competitive manufacturing base, but as a credible partner for global firms seeking to decarbonize their value chains in line with investor and stakeholder expectations.

Crypto, Digital Finance and Mobility Innovation

While the core of Thailand's EV hub is industrial, it also intersects with emerging trends in digital finance and crypto-enabled services. As EVs become more connected and integrated into smart city infrastructure, new business models are emerging around usage-based insurance, dynamic pricing for charging, peer-to-peer energy trading and tokenized incentives for low-carbon mobility. In Thailand, regulators and innovators are cautiously exploring how blockchain and digital assets might support these models, for example by enabling transparent tracking of renewable energy certificates or facilitating micro-payments for charging and parking.

This experimentation is occurring within a regulatory environment that has evolved rapidly in recent years, as Thai authorities have sought to balance innovation with consumer protection and financial stability in the digital asset space. Readers following crypto and digital finance developments on DailyBusinesss.com will recognize that Thailand is one of several markets in Asia where regulators are actively engaging with industry to shape the future of digital assets, including their potential applications in mobility and energy systems.

On a global level, institutions such as the World Economic Forum and Bank for International Settlements continue to analyze the implications of crypto, stablecoins and central bank digital currencies for payments, capital markets and cross-border trade. For businesses considering how these technologies might intersect with EV infrastructure, fleet management and consumer services, it is valuable to review global insights on digital currencies and payment innovation and assess how Thailand's regulatory approach may enable or constrain new mobility-linked financial products.

Thailand's EV Hub in the Context of Global Trade and Geopolitics

Thailand's ascent as an EV hub cannot be fully understood without considering the broader geopolitical and trade environment that is reshaping global supply chains. As companies in the United States, European Union, Japan and other advanced economies seek to diversify away from over-reliance on any single country, Southeast Asia has emerged as a key destination for "China-plus-one" strategies, with Thailand often at the center of boardroom discussions on regional manufacturing footprints. This diversification imperative has been reinforced by trade tensions, export controls on advanced technologies and growing scrutiny of supply chain resilience following the pandemic.

In this context, Thailand's relatively open trade regime, network of free trade agreements and stable business environment make it an attractive partner for multinational firms seeking to balance cost, market access and geopolitical risk. For global executives and investors, the country's EV hub represents both an operational opportunity and a strategic hedge, enabling them to serve markets in Asia, Europe, North America and beyond with a more distributed and resilient production base. Those interested in the geopolitical and macroeconomic dimensions of this shift can explore world and economics coverage as well as in-depth economic analysis on DailyBusinesss.com.

International think tanks and policy institutes, such as the Carnegie Endowment for International Peace and Chatham House, have increasingly examined how the energy transition and EV supply chains intersect with strategic competition among major powers. Business leaders evaluating long-term investments in Thailand's EV ecosystem would benefit from reviewing global research on energy, security and industrial policy to understand how shifting regulatory, trade and security dynamics could impact market access, technology flows and partnership structures.

Outlook to 2030: Opportunities and Risks for Global Business

Looking ahead to 2030, Thailand's role as an EV hub appears set to deepen, but the trajectory is not guaranteed and will depend on how effectively the country navigates a series of opportunities and risks. On the opportunity side, Thailand can leverage its manufacturing capabilities, geographic position and policy framework to expand EV exports, attract higher-value R&D activities and strengthen integration with regional partners in ASEAN, East Asia and beyond. There is also scope to position Thailand as a testing ground for advanced mobility solutions, including autonomous driving pilots in controlled environments, smart logistics corridors and integrated public transport systems powered by electric fleets.

At the same time, Thailand faces intense competition from neighboring countries and established manufacturing giants, as well as technological uncertainties related to battery chemistries, charging standards and potential breakthroughs in hydrogen or other alternative propulsion systems. To maintain its competitive edge, the country will need to continue investing in infrastructure, talent, digital connectivity and regulatory quality, while ensuring that its EV strategy is aligned with broader national priorities in energy, environment and social inclusion. For global businesses, this implies a need for continuous monitoring of policy signals, market data and technological developments, which can be supported by following ongoing news and market coverage and technology insights on DailyBusinesss.com.

International organizations such as the International Monetary Fund and OECD have emphasized that economies which successfully navigate the twin transitions of digitalization and decarbonization will be best placed to achieve sustainable, inclusive growth in the coming decade. Thailand's EV hub is a concrete example of how an emerging economy can translate these macro-level imperatives into sector-specific strategies that attract investment, create jobs and foster innovation. For business leaders, investors and policymakers across North America, Europe, Asia, Africa and South America, Thailand's experience offers valuable lessons on the importance of coherent policy, partnership with the private sector and a clear long-term vision in building competitive advantage in a rapidly changing global economy.

In this evolving landscape, DailyBusinesss.com will continue to track Thailand's progress as an electric vehicle hub, connecting developments in manufacturing, finance, technology, employment and trade, and providing the global business community with the analysis needed to make informed, forward-looking decisions.

South Korea's Dominance in Battery Technology

Last updated by Editorial team at dailybusinesss.com on Monday 23 February 2026
Article Image for South Korea's Dominance in Battery Technology

South Korea's Dominance in Battery Technology: Powering the Next Global Industrial Cycle

South Korea's Strategic Ascent in the Global Battery Race

By 2026, South Korea has consolidated a position at the center of the global battery ecosystem, standing alongside and in many respects ahead of competitors in the United States, China, Japan, and Europe. What began as an extension of its consumer electronics and automotive strengths has evolved into a comprehensive industrial strategy that now underpins energy security, electric mobility, and digital infrastructure worldwide. For readers of DailyBusinesss who follow developments in AI, finance, sustainability, markets, and global trade, understanding how South Korea has achieved this dominance in battery technology is essential to grasping the next phase of industrial transformation.

The country's leading battery manufacturers, including LG Energy Solution, Samsung SDI, and SK On, have become linchpins in global supply chains for electric vehicles, grid-scale storage, and advanced consumer devices. Their technologies power cars produced by Tesla, Volkswagen, Hyundai Motor Group, Ford, and General Motors, as well as stationary storage systems that support renewable integration across North America, Europe, and Asia. This transformation is not accidental; it is the result of decades of cumulative investment in materials science, manufacturing excellence, and export-oriented industrial policy, all of which align closely with the strategic themes that DailyBusinesss covers in business and industry analysis.

At the same time, South Korea's battery sector is deeply intertwined with global macroeconomic trends, from the push for decarbonization and energy independence to the reconfiguration of supply chains under geopolitical pressure. As governments from Washington and Brussels to Seoul and Tokyo seek to secure critical technologies, batteries have shifted from a niche component to a strategic asset, comparable in importance to semiconductors. For investors, founders, policymakers, and corporate leaders, the Korean battery story now serves as a case study in how technological focus, scale, and international collaboration can reshape global markets.

Foundations of Dominance: Industrial Policy, Chaebols, and R&D Depth

South Korea's leadership in battery technology is grounded in the same structural strengths that propelled its rise in semiconductors, shipbuilding, and electronics. The country's development model, characterized by close coordination between government and large conglomerates, or chaebols, created an environment where long-term capital-intensive bets in advanced manufacturing could be sustained over decades. The battery sector, led by LG Group, Samsung Group, and SK Group, has benefited from this tradition of deep, patient investment.

In the 1990s and early 2000s, when lithium-ion batteries were still largely associated with consumer electronics, Korean firms invested heavily in materials science, cell chemistry, and precision manufacturing. This early focus allowed them to move quickly when global demand shifted toward electric vehicles and grid storage. Their R&D centers, often working in collaboration with universities and institutes such as the Korea Advanced Institute of Science and Technology (KAIST) and the Korea Institute of Energy Research, built a foundation of expertise that could be rapidly adapted as new use cases emerged. Those seeking a deeper understanding of how industrial R&D supports competitiveness can explore broader trends in technology and innovation.

Government policy has been equally significant. The Ministry of Trade, Industry and Energy (MOTIE) and the Korea Energy Agency have supported battery research, pilot projects, and export promotion, while also aligning national energy and industrial strategies with the global shift toward electrification and decarbonization. South Korea's commitment to achieving net-zero emissions by 2050 has given further impetus to domestic deployment of energy storage systems and electric vehicles, creating a virtuous cycle of local demand and export growth. International organizations such as the International Energy Agency have repeatedly highlighted South Korea's role in scaling clean energy technologies, particularly in the storage domain.

This combination of industrial policy, corporate scale, and R&D depth has allowed South Korea to move beyond being a contract manufacturer and become an innovation leader in areas such as high-nickel cathodes, silicon-based anodes, and advanced battery management systems. For global markets, this means Korean firms are not only supplying capacity but also shaping the technology roadmap that will define performance, safety, and cost trajectories for years to come.

Technological Edge: From High-Nickel Chemistries to Solid-State Ambitions

The core of South Korea's competitive advantage lies in its mastery of advanced lithium-ion chemistries and its ability to industrialize them at scale. Companies like LG Energy Solution and SK On have been at the forefront of developing high-nickel NCM (nickel-cobalt-manganese) and NCA (nickel-cobalt-aluminum) cathode formulations that increase energy density and extend driving range, while Samsung SDI has pioneered high-performance cells for premium electric vehicles and energy storage applications.

These innovations are not purely incremental; they represent a sophisticated balancing act between performance, safety, cost, and supply chain risk. High-nickel chemistries reduce cobalt content, addressing both cost volatility and ethical concerns related to cobalt mining in regions such as the Democratic Republic of the Congo. At the same time, these formulations require careful control of thermal stability and cycling behavior, areas where Korean firms have built strong intellectual property portfolios and manufacturing know-how. For readers interested in the broader implications of such material innovations on global markets, the World Bank's energy storage resources offer useful background.

Beyond conventional lithium-ion, South Korean companies and research institutes are heavily invested in next-generation technologies, particularly solid-state batteries. Samsung SDI and LG Energy Solution have publicized development milestones in solid-state prototypes that promise higher energy densities, faster charging, and improved safety by replacing flammable liquid electrolytes with solid materials. While commercial deployment at scale remains a challenge, the race to bring solid-state batteries to market is now one of the defining contests in global electrification, with South Korean firms competing intensely with Japanese, American, and European rivals. Organizations such as Fraunhofer Institute for Systems and Innovation Research in Germany provide valuable analysis on how these technologies are reshaping industrial strategies in Europe and beyond.

Korean manufacturers are also pushing advances in battery management systems, thermal management, and pack-level integration, all of which are critical to the performance and safety of electric vehicles and grid-scale storage. Their expertise in electronics and software, inherited from decades of consumer device manufacturing, gives them a distinctive edge in integrating cells into complete systems that can be optimized for different applications and markets. This systems-level competence is increasingly important as AI-driven analytics and digital twins are used to monitor battery health, optimize charging cycles, and extend asset lifetimes, a topic that intersects closely with the AI coverage on DailyBusinesss' dedicated AI section.

Global Supply Chains, Geopolitics, and the Inflation Reduction Act Era

South Korea's dominance in battery technology cannot be understood without considering the shifting landscape of global supply chains and industrial policy, especially in the United States and Europe. The U.S. Inflation Reduction Act (IRA), enacted in 2022, has fundamentally reconfigured incentives for battery and EV manufacturing in North America, tying tax credits to domestic content and "friendly" sourcing. Korean firms have responded with a wave of investments in gigafactories across the United States, forming joint ventures with major automakers and committing tens of billions of dollars to local production.

Projects such as Ultium Cells LLC, the joint venture between LG Energy Solution and General Motors in the United States, and BlueOval SK, the partnership between SK On and Ford, exemplify this strategic alignment. By localizing production, Korean companies not only secure access to U.S. subsidies but also deepen their integration with key automotive customers, anchoring their role in North American supply chains. The U.S. Department of Energy provides extensive documentation on how such investments support national decarbonization and industrial resilience goals.

In Europe, similar dynamics are at play. The European Commission and national governments in Germany, France, and other member states have launched initiatives to build a competitive battery ecosystem, often under the umbrella of Important Projects of Common European Interest (IPCEI). Korean firms have established manufacturing footprints in countries such as Poland and Hungary, supplying European automakers while navigating an evolving regulatory environment focused on sustainability, recycling, and strategic autonomy. For a broader view of how Europe is structuring its battery strategy, readers can consult resources from the European Commission's energy and mobility directorates.

Geopolitically, South Korea must balance deep economic ties with China, which dominates upstream materials refining and component manufacturing, against growing security and trade alignment with the United States and other democratic partners. Korean battery makers rely heavily on Chinese suppliers for materials such as cathode precursors, graphite, and critical minerals, even as governments in Seoul, Washington, Brussels, and Tokyo push for diversification. The International Monetary Fund has highlighted how such supply chain concentration creates systemic vulnerabilities, particularly in the context of geopolitical tensions and resource nationalism.

For business leaders and investors tracking these crosscurrents, the Korean battery sector offers a real-time illustration of how industrial competitiveness, trade policy, and national security concerns are becoming deeply intertwined, a theme that resonates across the global economics coverage on DailyBusinesss.

Raw Materials, Sustainability, and the ESG Imperative

Dominance in battery technology brings with it a responsibility to address environmental, social, and governance (ESG) challenges across the value chain. South Korean firms are acutely aware that their long-term competitiveness depends not only on performance and cost but also on their ability to demonstrate responsible sourcing, low-carbon manufacturing, and effective end-of-life management.

The upstream segment of the battery supply chain, particularly mining and refining of lithium, nickel, cobalt, and manganese, is under increasing scrutiny from regulators, investors, and civil society organizations. Korean companies are responding through a combination of direct investments in mining projects, long-term offtake agreements, and participation in industry initiatives focused on responsible sourcing. Organizations such as the Responsible Minerals Initiative and the OECD's responsible business conduct guidelines are shaping standards and expectations in this area.

On the manufacturing side, Korean battery plants are under pressure to reduce carbon intensity, water use, and waste, particularly as automakers in the European Union and the United Kingdom must comply with increasingly stringent lifecycle emissions regulations. The European Battery Regulation, for example, requires detailed carbon footprint disclosures and sets recycling and material recovery targets that will influence how Korean firms design and operate their European facilities. For a deeper understanding of how regulatory frameworks are evolving, the European Environment Agency offers comprehensive analyses of industrial environmental impacts.

End-of-life management is emerging as a critical frontier for South Korea's battery ecosystem. Recycling and second-life applications not only mitigate environmental impacts but also offer a partial solution to resource constraints by recovering valuable materials and extending asset lifetimes. Korean companies and research institutes are exploring hydrometallurgical and pyrometallurgical recycling technologies, as well as repurposing EV batteries for stationary storage. These efforts align closely with the broader sustainability themes that DailyBusinesss explores in its sustainable business coverage, where circular economy models and low-carbon strategies are becoming central to corporate strategy.

For investors and corporate leaders, the Korean battery sector's approach to ESG is increasingly a determinant of capital access and market positioning, particularly as global asset managers and sovereign funds adopt more rigorous sustainability criteria. Institutions like the World Resources Institute and the UN Principles for Responsible Investment provide frameworks that shape how these issues influence capital allocation decisions.

Employment, Skills, and the Human Capital Dimension

The rapid expansion of battery manufacturing and R&D has significant implications for employment and skills development in South Korea and abroad. Domestically, the sector has created tens of thousands of high-quality jobs in engineering, materials science, manufacturing, and logistics, particularly in regions where large-scale plants are located. The Korean government and industry associations are working with universities and vocational schools to develop specialized curricula that prepare workers for roles in cell production, quality control, automation, and data-driven process optimization.

Internationally, Korean battery investments in the United States, Europe, and Southeast Asia are reshaping local labor markets, bringing advanced manufacturing jobs and technology transfer to countries such as the United States, Poland, Hungary, and Indonesia. These developments are closely watched by policymakers concerned with industrial revitalization and workforce development, particularly in regions that have experienced deindustrialization. Organizations such as the OECD analyze how such investments influence employment patterns, productivity, and regional development.

At the same time, the sector faces challenges in attracting and retaining specialized talent in areas such as electrochemistry, AI-driven process control, and power electronics, where global competition is intense. This talent dimension is particularly relevant for readers of DailyBusinesss who follow employment and labor market trends, as it illustrates how the green and digital transitions are reshaping skill requirements across industries.

For South Korea, the battery industry is not only an export engine but also a platform for upgrading its human capital base, fostering new generations of scientists, engineers, and technicians whose expertise will be critical to sustaining competitiveness in related fields such as hydrogen, power electronics, and advanced materials.

Investment, Markets, and the Financialization of the Battery Value Chain

From a financial perspective, South Korea's battery sector has become a focal point for global capital flows, equity valuations, and strategic partnerships. Listed entities such as LG Energy Solution and Samsung SDI command significant market capitalizations on the Korea Exchange, attracting institutional investors from North America, Europe, and Asia who view batteries as a core pillar of the energy transition and the future of mobility. The sector's growth prospects, combined with its exposure to regulatory shifts and commodity price volatility, make it a complex but compelling theme for portfolio construction and risk management, topics that align closely with the investment analysis on DailyBusinesss' finance and markets pages.

Beyond equity markets, the financialization of the battery value chain extends to project finance, green bonds, and sustainability-linked loans that support the construction of gigafactories and recycling plants. Multilateral institutions such as the Asian Development Bank and the European Investment Bank are increasingly involved in financing energy storage projects and manufacturing facilities, recognizing their importance for achieving climate and energy security goals.

The intersection of batteries and digital technologies is also attracting venture capital and corporate venture arms, particularly in areas such as AI-enabled battery analytics, advanced materials, and software platforms for fleet and grid optimization. For founders and early-stage investors, the Korean ecosystem offers opportunities to collaborate with established manufacturers while targeting niche innovations that can be scaled globally, a dynamic that resonates with the entrepreneurial stories covered in DailyBusinesss' founders section.

Commodity markets are another critical dimension. Prices for lithium, nickel, and other key inputs have experienced sharp fluctuations over the past several years, influenced by demand surges, supply disruptions, and speculative activity. Financial institutions and commodity traders increasingly treat battery metals as a distinct asset class, integrating them into strategies that span physical supply, derivatives, and structured products. Readers interested in how these dynamics affect global trade and capital flows can explore broader market coverage on DailyBusinesss' markets page.

AI, Data, and the Future of Battery-Enabled Business Models

As of 2026, the convergence of battery technology and artificial intelligence is opening new frontiers in both industrial operations and business models. South Korean firms are deeply engaged in deploying AI across the battery lifecycle, from R&D and manufacturing to deployment and lifecycle management. Machine learning techniques are used to accelerate materials discovery, optimize electrode formulations, and simulate degradation pathways, significantly reducing the time and cost required to bring new chemistries to market. Institutions such as the Allen Institute for AI and research groups at leading universities highlight how AI-driven science is transforming materials research, including battery technologies.

In manufacturing, AI and advanced analytics are applied to process control, defect detection, and yield optimization, leveraging vast amounts of data generated by highly automated production lines. This data-centric approach is particularly well-suited to Korean firms, which have decades of experience in high-volume electronics manufacturing and are now extending those capabilities to gigafactories. For readers who follow AI and automation trends, the connections between intelligent manufacturing and energy storage are increasingly central to understanding the future of industrial competitiveness, a theme that features prominently in DailyBusinesss' AI and technology coverage.

On the deployment side, AI-enabled battery management systems and cloud-based platforms are transforming how energy storage assets are operated and monetized. Grid-scale storage facilities, EV fleets, and distributed residential systems are increasingly orchestrated through algorithms that optimize charging and discharging based on electricity prices, grid conditions, and asset health. Organizations like the U.S. National Renewable Energy Laboratory provide insights into how such digital optimization can enhance the value of storage in modern power systems.

These developments are giving rise to new business models in energy-as-a-service, mobility-as-a-service, and virtual power plants, where batteries become not just hardware but key nodes in data-driven ecosystems. South Korean companies, with their combined expertise in batteries, electronics, and software, are well-positioned to participate in and shape these emerging markets, creating additional layers of value beyond cell manufacturing.

Strategic Outlook: South Korea's Next Chapter in the Battery Age

Looking ahead, South Korea's dominance in battery technology appears secure but not unchallenged. Competition from Chinese, Japanese, American, and European firms is intensifying, and the policy environment is becoming more complex as governments pursue industrial strategies that blend decarbonization goals with economic security. For South Korea, maintaining leadership will require continued investment in next-generation technologies, diversification of raw material sources, and deepening of global partnerships, all while navigating geopolitical tensions and increasingly demanding ESG expectations.

For the global business community that turns to DailyBusinesss for analysis on trade, investment, and world markets, the Korean battery story offers several key lessons. It demonstrates how a focused industrial strategy, anchored in technological depth and export orientation, can position a relatively small country at the center of a critical global value chain. It illustrates the importance of aligning corporate strategy with macro trends in energy, climate, and digitalization. And it underscores how AI, advanced manufacturing, and sustainable finance are converging to reshape the foundations of economic growth.

As electric vehicles become the default choice in markets from the United States and Germany to China and Australia, and as grid operators from Canada and the United Kingdom to South Africa and Brazil rely more heavily on storage to integrate renewables, South Korea's batteries will continue to underpin the functioning of the modern economy. The country's ability to innovate, scale, and collaborate across borders will not only determine its own prosperity but also influence how the world manages the twin transitions to a low-carbon and digitally integrated future.

For decision-makers tracking these shifts, following developments in South Korea's battery sector is no longer a niche interest; it is a prerequisite for understanding the evolving landscape of global business, finance, and technology, and it will remain a central theme in the global coverage provided by DailyBusinesss.

Smart Cities Integrate AI for Urban Management

Last updated by Editorial team at dailybusinesss.com on Monday 23 February 2026
Article Image for Smart Cities Integrate AI for Urban Management

Smart Cities Integrate AI for Urban Management in 2026

The New Urban Operating System

By 2026, artificial intelligence has moved from being a promising technology to becoming the de facto operating system of the world's most advanced cities. From New York and London to Singapore, Seoul and Barcelona, urban leaders are no longer asking whether AI should be integrated into city management, but how deeply it should be embedded into every layer of urban infrastructure, governance and daily life. For readers of DailyBusinesss.com, whose focus spans AI, finance, business strategy, markets and the future of work, this shift represents one of the most consequential structural transformations of the global economy in decades, with implications for investment, regulation, risk, and competitive advantage across regions from North America and Europe to Asia, Africa and South America.

Smart cities in 2026 are not defined merely by sensors and connectivity; they are increasingly characterised by integrated AI platforms that process vast flows of real-time data from transport networks, energy grids, buildings, public services and digital transactions, turning cities into adaptive systems that can anticipate demand, optimise resources and respond dynamically to disruptions. As municipal governments, technology giants and infrastructure investors race to shape this new urban paradigm, the central question for business and policy leaders is how to harness AI's efficiency and innovation benefits while preserving trust, privacy, resilience and social cohesion. In this context, DailyBusinesss positions itself as a guide and interpreter of these shifts, connecting developments in AI and automation with their financial, economic and geopolitical consequences.

AI as the Core of Urban Infrastructure

The most advanced smart cities now treat AI not as a layer added on top of existing services, but as a foundational infrastructure comparable to roads, power grids or water systems. According to analyses from organisations such as the World Economic Forum, which explores how digital technologies reshape urban systems, AI-enabled platforms increasingly orchestrate traffic management, emergency response, energy balancing and public maintenance in a coordinated fashion rather than as siloed domains. This systemic integration allows cities to move beyond pilot projects and proofs of concept toward full-scale operational AI, with measurable impacts on congestion, emissions, safety and service reliability.

In practice, this means that city control centres receive continuous streams of data from connected vehicles, traffic cameras, environmental sensors, public transport, utilities and building management systems, and use machine learning models to predict demand surges, identify anomalies and recommend interventions. Readers who follow the broader evolution of digital infrastructure on DailyBusinesss technology coverage will recognise that urban AI platforms now resemble cloud-native enterprise architectures, with microservices, APIs and data lakes enabling interoperability between vendors and agencies. Cities such as Singapore, documented by institutions like the MIT Senseable City Lab, have become benchmark cases, where AI informs everything from land-use planning to predictive maintenance of public housing.

Data, Connectivity and the Urban Digital Twin

Underpinning AI-driven urban management is a dense fabric of connectivity and data, increasingly organised around the concept of the "digital twin" - a virtual representation of the city that mirrors its physical assets and real-time conditions. In 2026, leading cities in the United States, United Kingdom, Germany, the Netherlands and the Nordics are investing heavily in 5G and emerging 6G networks, edge computing and interoperable data standards to support these digital twins, enabling AI models to ingest, process and act upon information with minimal latency. Organisations such as the International Telecommunication Union (ITU) and the European Commission have been instrumental in defining frameworks for data governance and interoperability, which in turn shape how urban AI ecosystems evolve across regions.

For businesses, the rise of urban digital twins opens new markets in simulation, analytics, risk management and real estate optimisation, as investors and operators can model the impact of policy changes, infrastructure investments or climate shocks before committing capital. Readers of DailyBusinesss investment insights will note that infrastructure funds and sovereign wealth funds are increasingly evaluating cities' data and AI capabilities as part of their due diligence, treating digital maturity as a core determinant of long-term asset performance. As more cities in Asia, from Tokyo to Bangkok and Singapore, embrace digital twin strategies, global standards and best practices will increasingly shape cross-border investment flows and partnerships.

AI-Driven Urban Mobility and Logistics

One of the most visible domains where AI has transformed urban management is mobility. In 2026, advanced traffic management systems in cities such as Los Angeles, Berlin and Shanghai use AI to coordinate traffic lights, adjust signal timing based on predicted congestion, prioritise public transport and emergency vehicles, and manage curb space for ride-hailing, delivery and micromobility services. Research shared by organisations like the OECD's International Transport Forum highlights how AI-driven traffic optimisation can reduce travel times, emissions and accidents, while also enabling more efficient use of existing road capacity, delaying or eliminating the need for costly new infrastructure.

At the same time, the rapid growth of e-commerce, on-demand delivery and autonomous vehicles has made last-mile logistics a critical test case for urban AI. Platforms that combine routing algorithms, demand forecasting and dynamic pricing are helping logistics operators and city authorities coordinate deliveries, reduce congestion and limit environmental impact, particularly in dense urban cores in Europe and Asia. For professionals tracking the intersection of technology and business on DailyBusinesss tech coverage, this shift is creating new ecosystems where automotive manufacturers, cloud providers, mapping companies and start-ups collaborate and compete to control the data and algorithms that orchestrate urban movement.

Energy, Sustainability and the Climate Imperative

In parallel with mobility, energy and sustainability have become central arenas for AI-enabled urban transformation. With cities responsible for a significant share of global energy consumption and greenhouse gas emissions, AI-based optimisation of electricity grids, district heating, building operations and distributed energy resources is now a strategic priority for governments in Europe, North America, Asia and beyond. Organisations such as the International Energy Agency (IEA) have highlighted how AI can support demand response, integrate variable renewable energy, and improve the efficiency of industrial and commercial loads, helping cities progress toward net-zero targets.

Smart buildings equipped with AI-driven management systems can adjust heating, cooling, lighting and ventilation based on occupancy patterns, weather forecasts and real-time energy prices, while city-wide platforms coordinate electric vehicle charging, battery storage and rooftop solar. For readers of DailyBusinesss sustainable business section, the convergence of AI, clean energy and climate policy is reshaping how property developers, utilities, manufacturers and financiers structure their projects and partnerships. Learn more about sustainable business practices through resources offered by organisations such as the World Resources Institute, which provide guidance on aligning AI-enabled solutions with climate resilience and equity goals.

Financing the AI-Enabled City

The integration of AI into urban management is capital-intensive, requiring investments not only in hardware and software but also in cybersecurity, data platforms, change management and workforce training. As a result, the financial architecture of smart cities has evolved rapidly, with multilateral development banks, infrastructure funds, pension funds and corporate investors collaborating with municipalities through public-private partnerships, outcome-based contracts and new forms of digital infrastructure financing. Institutions such as the World Bank and regional development banks have developed frameworks to assess the economic and social returns of AI-enabled urban projects, helping cities in emerging markets in Africa, South America and Southeast Asia access capital while managing risk.

For the finance-oriented audience of DailyBusinesss finance coverage, this raises important questions about valuation, revenue models and risk allocation. AI-enabled services often blur the lines between traditional utility infrastructure, software-as-a-service and data monetisation, requiring new approaches to pricing, performance guarantees and regulatory oversight. Financial regulators and central banks, including the Bank for International Settlements, are increasingly examining how digital infrastructure and AI-driven services interact with financial stability, systemic risk and capital flows, especially as cities become hubs for fintech, digital assets and real-time payment systems.

Crypto, Digital Identity and Urban Transactions

The intersection of smart cities, AI and crypto-assets has become one of the most dynamic and contested areas of innovation by 2026. While speculative trading in cryptocurrencies has moderated in many jurisdictions due to stricter regulation, the underlying technologies of blockchain, digital identity and tokenisation are increasingly being explored for urban applications. Some cities in Europe, North America and Asia are piloting blockchain-based land registries, digital identity systems and tokenised incentives for sustainable behaviour, using AI to detect fraud, optimise rewards and personalise services. For readers following developments in crypto and digital assets, this convergence represents both a new frontier of opportunity and a complex regulatory challenge.

Central bank digital currencies (CBDCs), under exploration by institutions such as the European Central Bank and the Bank of England, are also likely to play a role in the future of urban transactions, enabling programmable payments for transport, energy and public services that can be integrated with AI-driven platforms. Learn more about digital currency research from the International Monetary Fund, which has been analysing the macroeconomic and financial stability implications of CBDCs and stablecoins. As cities experiment with these tools, they must balance innovation with privacy, inclusion and cybersecurity, ensuring that AI-enhanced transaction systems do not exacerbate existing inequalities or vulnerabilities.

Employment, Skills and the Urban Workforce

The integration of AI into urban management is reshaping labour markets in ways that are particularly relevant to the employment-focused readers of DailyBusinesss employment coverage. On one hand, AI-driven automation is reducing the need for certain routine tasks in public administration, transport operations, maintenance and customer service; on the other, it is creating new roles in data science, cybersecurity, digital infrastructure management, urban analytics and citizen engagement. The net impact on employment varies across regions and sectors, but what is clear is that cities must invest heavily in reskilling and upskilling their workforces to remain competitive and inclusive.

Organisations such as the International Labour Organization (ILO) and the OECD have emphasised the importance of lifelong learning systems, digital literacy and social protection reforms to manage the transition to AI-intensive economies. In practice, this means that city governments, universities, vocational institutions and employers in countries from the United States and Canada to Germany, Singapore and South Africa are collaborating to design curricula and training programmes aligned with the skills demanded by AI-enabled urban services. For many workers, particularly in logistics, public transport and facility management, AI is becoming a co-pilot rather than a replacement, augmenting human capabilities while requiring new competencies in oversight, interpretation and human-machine collaboration.

Governance, Ethics and Trust in Urban AI

As AI becomes more deeply embedded in city management, questions of governance, ethics and trust move to the forefront. Cities that aspire to be global leaders in innovation must demonstrate that their use of AI is transparent, accountable and aligned with democratic values, particularly in sensitive areas such as surveillance, policing, welfare provision and credit scoring. Institutions such as the UNESCO and the Council of Europe have developed ethical frameworks and guidelines for AI deployment, while the European Union's AI regulatory initiatives are shaping global norms around risk categorisation, transparency obligations and human oversight.

For business leaders and investors reading DailyBusinesss business analysis, the regulatory trajectory of AI in urban contexts is a critical strategic factor, influencing market entry decisions, product design and compliance costs across jurisdictions. Companies that provide AI solutions for smart cities must navigate a complex landscape of data protection laws, procurement rules, liability frameworks and public expectations, particularly in regions such as the European Union, where the balance between innovation and fundamental rights is under intense scrutiny. Learn more about responsible AI principles through resources from the Alan Turing Institute, which offers guidance on fairness, accountability and transparency in algorithmic systems.

Global Competition and Collaboration among Smart Cities

Smart cities have become a focal point of geopolitical competition and collaboration, as national governments view AI-enabled urban infrastructure as both an economic growth engine and a strategic asset. Countries such as the United States, China, Singapore, South Korea and members of the European Union are supporting city-level innovation through national AI strategies, funding programmes and regulatory sandboxes, while also competing to set global standards and export their technologies. The OECD and the G20 have been key venues for discussing cross-border cooperation on AI, data flows and digital trade, which in turn shape how urban platforms interoperate and how businesses scale solutions across markets.

At the same time, networks of cities, such as the C40 Cities Climate Leadership Group and the Global Covenant of Mayors, are sharing best practices on AI-enabled climate action, resilience and inclusive governance, helping cities in emerging economies learn from early adopters in Europe, North America and Asia. For readers interested in the global and geopolitical dimensions of these trends, DailyBusinesss world coverage provides context on how smart city initiatives intersect with trade, supply chains, talent mobility and regional integration. The interplay between urban innovation hubs in places like London, Berlin, Toronto, Sydney, Paris, Amsterdam, Zurich, Tokyo and Seoul will continue to shape the competitive landscape for technology providers and investors through the rest of the decade.

Founders, Start-ups and the Urban Innovation Ecosystem

Behind the large-scale infrastructure projects and government strategies, a dynamic ecosystem of founders and start-ups is driving much of the experimentation and value creation in AI-powered urban management. Entrepreneurs are building niche solutions in areas such as predictive maintenance, urban agriculture, micro-mobility, environmental monitoring, citizen engagement platforms and AI-powered planning tools, often partnering with city authorities, corporates and research institutions. Readers who follow DailyBusinesss founders and entrepreneurship stories will recognise that smart cities have become fertile ground for venture-backed innovation, with accelerators, testbeds and living labs enabling rapid prototyping and deployment.

However, the path from pilot to scale remains challenging, as start-ups must navigate complex procurement processes, long sales cycles and the technical and political risks associated with critical infrastructure. Investors and founders are increasingly aware that success in the urban AI space requires not only technical excellence but also deep understanding of public policy, community engagement and long-term governance. Learn more about urban innovation ecosystems through resources from the Brookings Institution, which analyses how cities can cultivate inclusive, resilient and competitive innovation clusters that benefit both residents and businesses.

Markets, Trade and the Business of Urban AI

The commercialisation of AI for urban management is reshaping markets and trade patterns across technology, infrastructure and services. From cloud platforms and sensors to analytics software and managed services, a complex value chain has emerged, with global technology companies, telecommunications operators, engineering firms and specialised start-ups competing and collaborating to provide integrated solutions. For readers of DailyBusinesss markets coverage, this ecosystem presents both growth opportunities and consolidation risks, as dominant platforms seek to lock in customers and data, while regulators scrutinise market power and interoperability.

International trade in digital services, governed in part by frameworks discussed at the World Trade Organization, is becoming increasingly relevant as cities procure AI solutions from foreign vendors and as data flows cross borders. At the same time, concerns about data sovereignty, national security and supply chain resilience are prompting some governments to encourage local development of AI capabilities and to impose restrictions on certain foreign technologies, particularly in critical infrastructure domains. Readers can explore broader trade dynamics in DailyBusinesss trade coverage, where the interplay between digital policy, tariffs, standards and geopolitics is shaping the environment in which smart city solutions are developed and deployed.

The Future of AI-Enabled Urban Life

Looking ahead to the remainder of the 2020s, the integration of AI into urban management is likely to deepen and diversify, moving beyond core infrastructure and services into more personalised, anticipatory and participatory forms of governance. Cities may increasingly use AI to tailor services to individual needs, from personalised mobility planning and health interventions to dynamic pricing for utilities and public amenities, while also leveraging AI to analyse citizen feedback, simulate policy outcomes and support more informed democratic decision-making. For readers across finance, technology, employment and sustainability, this evolution will have far-reaching implications for business models, regulatory frameworks and social contracts.

At the same time, the risks associated with AI in cities - from cyberattacks and systemic failures to bias, exclusion and surveillance - will demand robust governance, continuous oversight and international cooperation. Organisations such as the World Health Organization are already considering how urban design, digital technologies and AI affect public health, mental well-being and resilience, particularly in dense megacities facing climate stress and demographic change. For businesses and policymakers, staying ahead of these developments requires not only technological literacy but also a holistic understanding of economics, ethics, law and human behaviour, an approach that aligns with the cross-disciplinary coverage offered by DailyBusinesss economics insights.

Positioning for Opportunity and Resilience

For the global audience of DailyBusinesss, spanning regions from the United States, United Kingdom, Germany, Canada and Australia to Singapore, Japan, South Korea, South Africa, Brazil and beyond, the rise of AI-enabled smart cities represents both a strategic opportunity and a complex risk landscape. Companies that understand how AI is transforming urban infrastructure, services and governance will be better positioned to design relevant products, allocate capital effectively and engage constructively with city authorities and communities. Investors who integrate urban AI trends into their analysis of real estate, infrastructure, technology and consumer markets will be better equipped to identify resilient assets and avoid stranded investments.

Equally, policymakers and civic leaders who engage with business, academia and civil society can help ensure that AI-powered urban management enhances rather than undermines social cohesion, economic inclusion and environmental sustainability. As cities continue to evolve into intelligent, adaptive systems, DailyBusinesss will remain committed to providing rigorous, forward-looking coverage across news and analysis, connecting developments in AI, finance, crypto, employment, sustainability, trade and technology to the lived realities of urban life and the strategic decisions that shape the future of business worldwide.